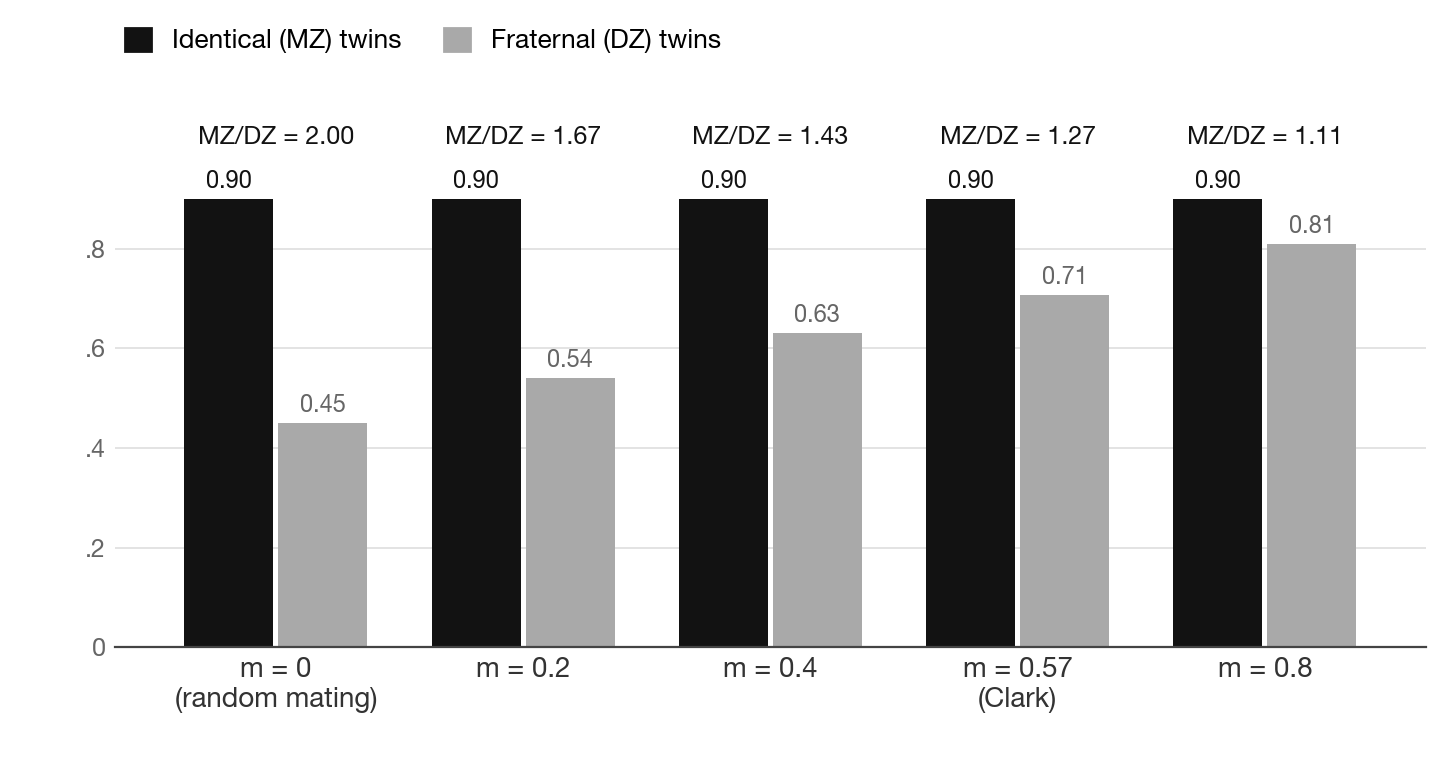JD Vance: “You Don’t Turn the Titanic Around Overnight”: LAUGH OF THE DAY

Is JD Vance really thinking: “Here I am, powerless second-in-command on the Titanic, with the captain a senile moron ruled by his hatreds and his impulses”? Probably:

This is funny.

Share

This is also very dangerous. Because Vance does not appear to be aiming for a political constellation in which he honestly wins enough electoral votes, does he? So then what is he aiming for?

We have:

Give a gift subscription

Yes, he said it.

Dave Weigel weighs in:

David Weigel: <twitter.com/daveweige…>: ‘Everyone taking their whacks at the “Titanic” line, but the reason this doesn’t seem to be working is the premise: That every major problem voters are angry about was left behind by Biden. Voters who were told Trump would lower prices ASAP just don’t buy it. I’m a little surprised that “the old man who couldn’t do the job made things worse and we’re fixing them” is a hard sell but here we go…


Brad DeLong here: First, it is real. JD Vance:

JD Vance (January 22, 2026: Speech in Toledo, Ohio <https://www.snopes.com/fact-check/vance-us-economy-titanic/>: ‘And yes, there is an affordability crisis. One created by Joe Biden’s policies. You don’t turn the Titanic around overnight. It takes time to fix what was broken…

So six further points:

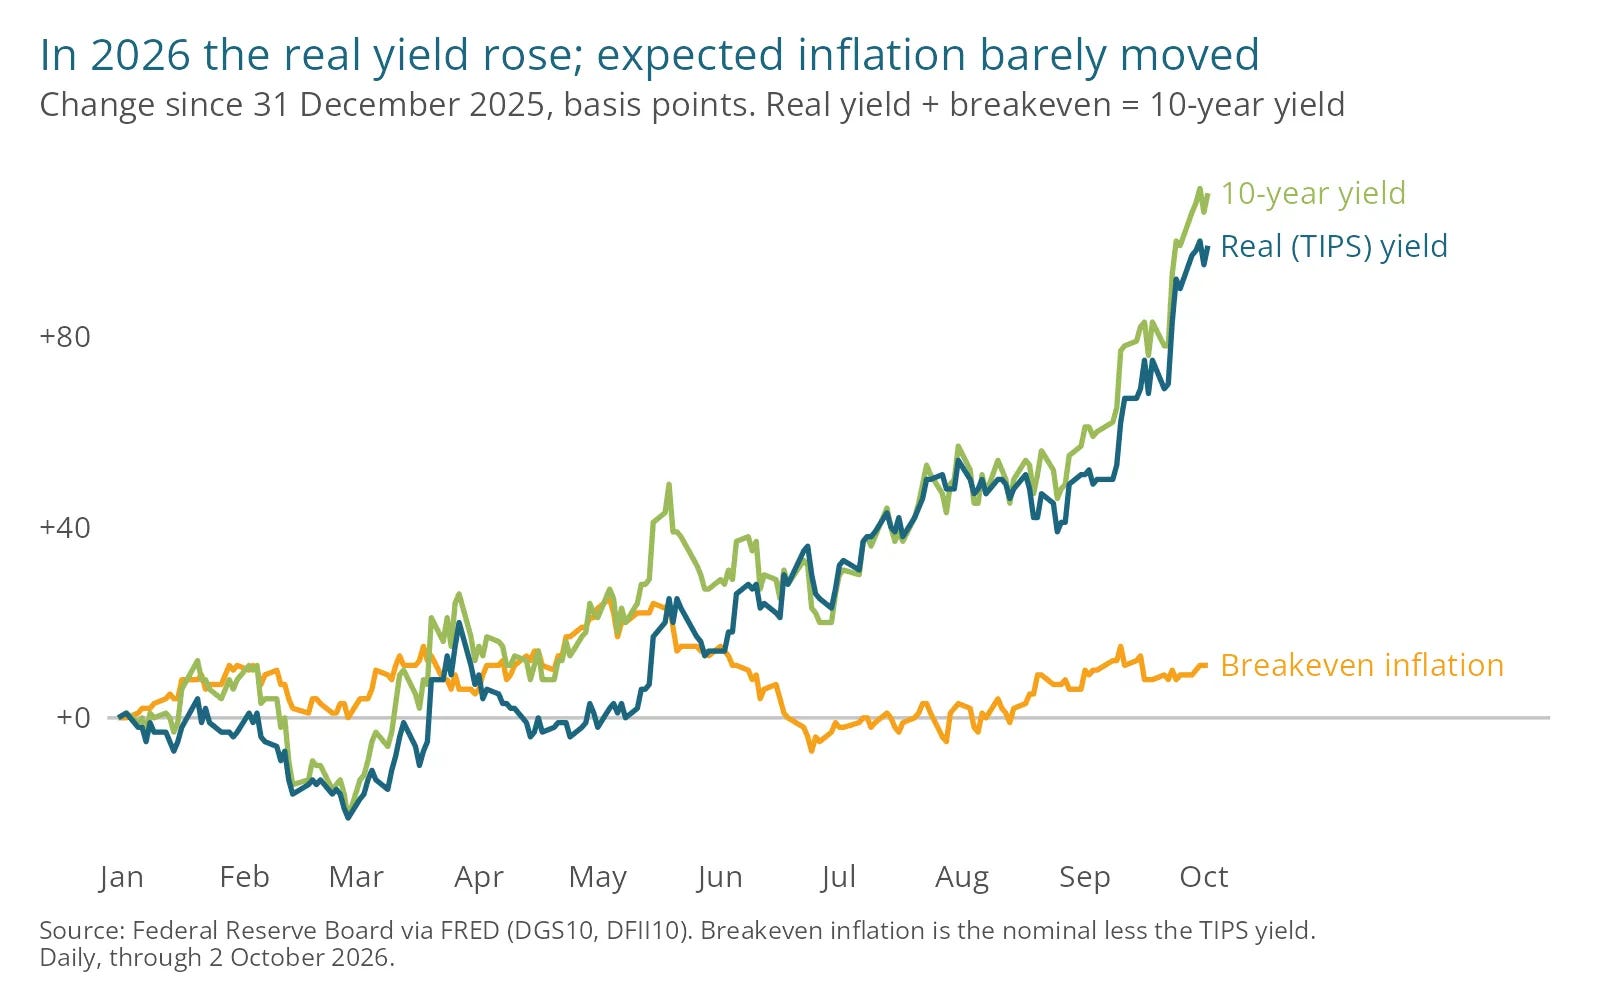
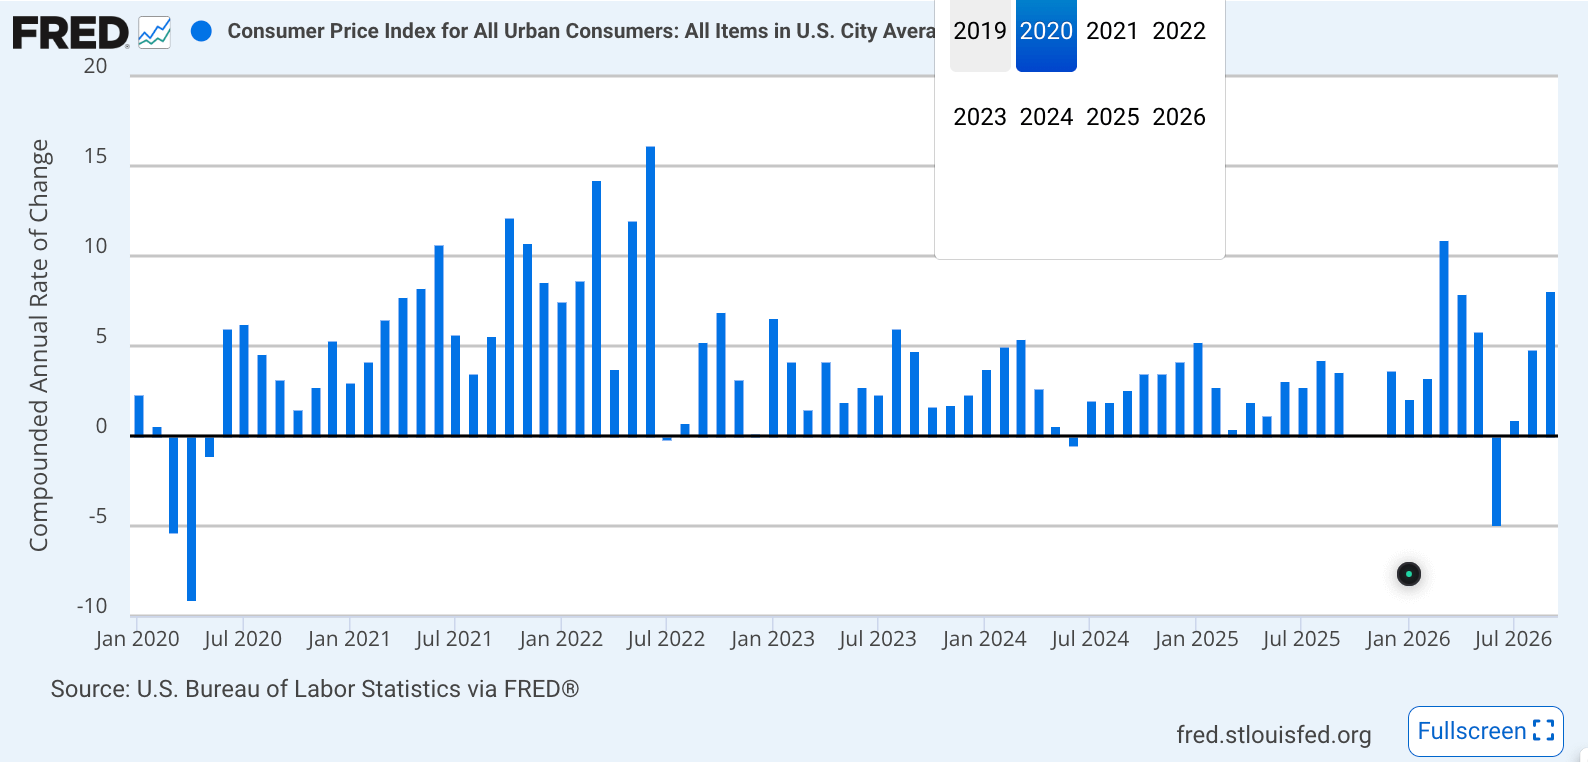
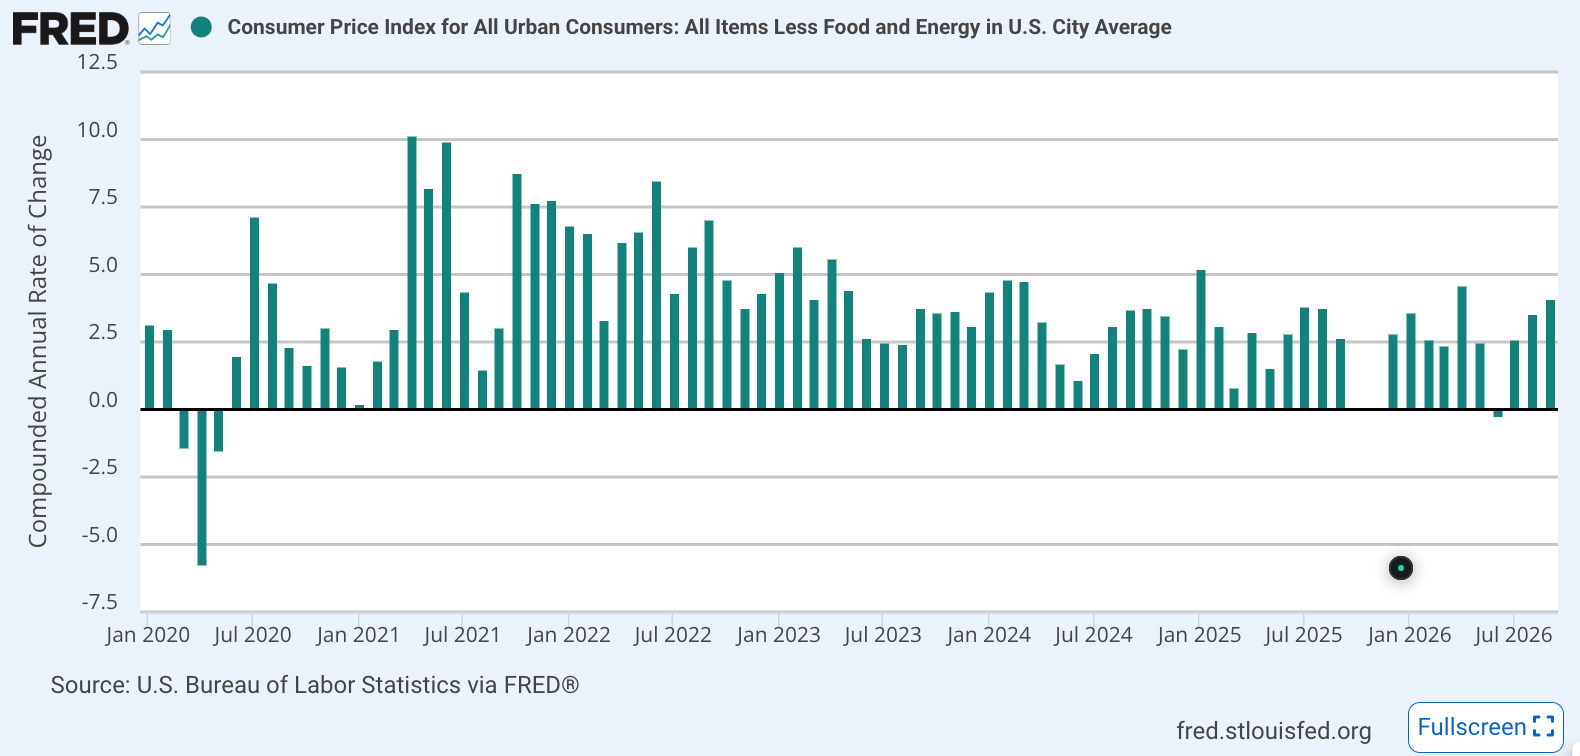
  1. The Titanic needed to not hit the iceberg: to not be steered at full speed into hazards that the captian and the crew had been fully warned about. That describes Trump’s tariffs. That describes Trump’s wars. That describes Trump’s restoking of inflation. It describes what Trump has done much better than it describes what Biden left behind.

  2. Vance planned for non-affordability, and he told us in advance that we would face “higher consumer prices in the short term” but that it was worthwhile as it would be part of “protecting American industries”.

  3. Biden left an economy in ship-shape, for in January 2025 inflation was very close to target, certainly not rising, had truly had been transitory until Trump’s friend Vlad the dictator of Muscovy ‘Rus had invaded Ukraine, and was under control. Biden’s soft landing had already been made. Unemployment was near historic lows. The U.S. was leading the G-7 in recovery.

  4. “Overnight” is a dodge. inasmuch as Trump and vance had promised voters that they would see lower prices “starting on day one”.

  5. Very real long-run damage comes from policy chaos in the form of random destructive tariffs, attacks on Fed independence, and an immigration crackdown that shrinks the labor force; all those are choices that they genuinely will take years to undo and neutralize

  6. The Titanic sank in under three hours, so what the passengers owed the steering bridge of the Titanic less patience, not more.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##jd-vance-you-dont-turn-the-titanic-around-overnight-laugh-of-the-day
##neofascism
##laugh-of-the-day
#neoneofascism
#jd-vance-you-dont-turn-the-titanic-around-overnight
#jd-vance
#you-dont-turn-the-titanic-around-overnight
#titanic
#affordability-crisis
#tariffs
#freudian-slip
#trump-economy
#mercantilism
#dave-weigel
#every-accusation-a-confession

Smartest Thing I Have Seen This Week: Thompson of StraTECHery & Moffett of MoffettNathanson on SpaceX & Bubbles: PODCAST OF THE DAY

Craig Moffett on Musk’s possible positive-feedback flywheels, the physics of Starlink’s possible networks, SpaceX “optionality”, what 1999 has to teach us about the AI capital expenditure boom, and how you have to ignore the revenue sloshing between the layers of the bubble value chain and look only at what it produces that people outside are willing to actually pay for:

This is the best thing I have seen this week, and the best thing on SpaceX I have seen this year.

Share

Ben Thompson and Craig Moffett talk.

Some highlights:

On SpaceX:

Ben Thomson & Craig Moffett: SpaceX & Bubbles <https://stratechery.com/2026/an-interview-with-craig-moffett-about-spacex-and-bubbles>: ‘Craig Moffett: ‘On the one hand, [Musk] says… absurd things…. But… they have achieved some extraordinary things…. Grok and the neocloud business… the AI business terrestrially… the biggest part of what SpaceX is….

The space segment is essentially a monopoly and… they’re also gaining knowledge at something like 10x the rate of anybody else, so… they’re pulling away…. The most valuable part of… Musk…. [is] you move so fast that you accumulate knowledge at a rate… completely different than anybody else…. This flywheel of generating volume, generating learning, driving down the cost curve way faster than anybody else…. Think about the difference in pacing. Between the time that [Blue Origin’s] rocket blew up and the time that they’re ready to launch the next one, SpaceX will have launched 14 times…

Give a gift subscription

And:

This flywheel of generating volume, generating learning, driving down the cost curve way faster than anybody else…. That’s an extraordinary strategic position for them to have and it creates all kinds of optionality. You can identify all the businesses that they’re currently in…. You can also identify the businesses they say they will be in…. [But] it would have been intellectually wrong to say, “I’m just going to value this company solely on the things that I can see today”, because it really does have optionality…. The question is how large that optionality is…. [Our] neutral rating… [came because] we were a bit below consensus on almost all of the businesses in the here and now…. [In valuation] you’re not just predicting when it will arrive… [but] when do people think it will arrive…. Warren Buffett… brilliantly said… derisively, that most of investing is trying to guess what a bunch of other people will guess consensus will be in six months…

Share DeLong’s Grasping Reality Weblog

And:

I don’t know that [low-earth orbit] will stay a [SpaceX] monopoly…. The market is underestimating the level of regulatory and geopolitical risk…. Domestic political risk too, [as] he’s so closely identified with the Republicans…. The rest of the world feels like it is impossible to leave any Western company… controlled by Elon Musk in charge of critical technology…. China will absolutely have its own [satellite] constellation…. India, because Elon Musk has sort of declared war on the Ambanis…. The risk that there is [also] a European constellation… is much higher by virtue of the fact that the current U.S. administration has alienated so much of Europe….

The original concept for SpaceX was that SpaceX would have all these rockets going into space anyway for the U.S. government and the military…. [Thus] you could build a constellation like Starlink… sticking the satellites in the excess capacity of the payloads and so the marginal cost of putting the satellites into space would be zero. That’s a really gorgeous concept, except it never actually happened…. Every satellite in space today for Starlink was launched in a purpose-built launch….

We did our first analysis of Starlink broadband five years ago…. The real constraint is the number of customers you can simultaneously serve within a specific spot beam from one satellite…. There’s a limit to how tight you can make a spot beam when you’re sending it from 220 miles away. You’ve still got physics to work with…. If you lower the orbital, you have a tighter spot beam that increases your capacity. But the lower the orbit, the more drag from the ionosphere, and the faster the satellite will be pulled back down…. These satellites go up and five years from now, they’ve burned up in space and you need to replace them…. You’re going to have three or four launches of Starship every week just to maintain Starlink, much less all the other purposes…

Leave a comment

And on bubbles:

The lesson I learned from 1999 is that you need to ignore all of the revenue being generated between layers of the value chain, it doesn’t matter…. I don’t really care what Nvidia is getting paid by some other company for its GPUs…. All I care about are the revenues coming into the system…. It can be enterprise, it can be government, and it doesn’t have to be today, it can be… projected…. Ignore all the revenues going on between layers of the value chain…. That’s just noise…. [What] really matters is [“is there] enough money coming into the system to support the system?[”]… it’s not that these aren’t amazing products…. It’s not that they aren’t going to be transformational…. It’s, “Is there going to be the price realization that allows them to be profitable enough that it supports the rest of the value chain?”… Right now… the market is saying, “We don’t know”….

My suspicion is that these are [many] businesses where… a cheaper model that’s two or three generations old [is fine]…. DeepSeek at the cost-per-token… that’s one-eighth or one-twelfth of frontier models…. What you can do with a thin client… able to run locally… [with] thinner and thinner and thinner models that are sufficiently good that they do most of what needs to get done for most use cases…. That puts a hell of a lot of burden on the capital investment of the really big stuff, for a relatively small part of the revenue opportunity. That’s the risk [here]…. We’re going in with our blindfold on and just wishing for the best…

Refer a friend


Brad DeLong here: Think of it. As Craig Moffett says, between the time Blue Origin’s rocket blew up and its next launch, SpaceX will have launched its rocket fourteen times. Craig Moffett thinks that gap in learning speed is SpaceX’s real asset, which the market is by and large correctly pricing. But he also thinks the market is massively underpricing the political risk that comes with Elon Musk’s bizarre hatreds and lies.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##smartest-thing-i-have-seen-this-week-thompson-of-stratechery-moffett-of-moffettnathanson-on-spacex-bubbles-podcast-of-the-day
##attention-info-bio-tech-economy
##podcast-of-the-day
#smartest-thing-i-have-seen-this-week-thompson-of-stratechery-moffett-of-moffettnathanson-on-spacex-bubbles
#smartest-thing-i-have-seen-this-week
#thompson-of-stratechery-moffett-of-moffettnathanson-on-spacex-bubbles
#ben-thompson
#craig-moffett
#spacex
#starlink
#elon-musk
#ai-bubble
#stratechery
#learning-by-doing
#real-options-valuation
#satellite-constellations
#tech-valuation

CROSSPOST: JOSH BERNHOFF (2019): Why Books Work: A Rebuttal to Andy Matuschak

Andy Matuschak says: if you can't explain a book's ideas when someone questions you, you never really absorbed them. But readers keep in their minds’ forefronts a book's strongest principles, the few side ideas that matter for their own work, and some memorable details. Plus much of the rest sits quietly until a situation calls it up. But those books that do the best are those books that encourage—that in fact make it almost impossible to avoid—deep reading practices:

Bernhoff says, à propos of Andy Matuschak (2019) , “Why Books Donʼt Work “<https://andymatuschak.org/books/>, that a successful nonfiction book is a layered production, and that:

Share

  • Strong principles stick.

  • Supporting arguments matter less, because you don’t have to see the framing to know the building stands.

  • Readers keep the subsidiary ideas that are relevant to them.

  • Vivid bits, especially stories, are remembered.

Give a gift subscription

out of the sum total of the architecture of strong principles, supporting arguments, subsidiary ideas, and hundreds of “bits” of facts, statistics, diagrams, and stories. For:

It’s amazing what’s hiding in your head, waiting for the moment that it becomes relevant…

Share DeLong's Grasping Reality Weblog

But, he also says, writers have an obligation to write good books: Address the reader to break the frame and break up a lulling flow. Tell stories. Shouldn’t authors ask rhetorical questions. Vary the format. Present the same information in different modes: text paragraphs, heading and bullet-list summaries, and graphics. Introduce and sum up:

Josh Bernhoff:


CROSSPOST: JOSH BERNHOFF (2019): Why Books Work: A Rebuttal to Andy Matuschak

<https://bernoff.com/blog/why-books-work-a-rebuttal-to-andy-matuschak> <https://bernoff.com/blog>

ByJosh BernoffMay 24, 2019

Andy Matuschak wrote a thoughtful piece called “Why books don’t work.” I think he’s a bit off-target. But his arguments will get you thinking about how your book can work better.

If you’re an author with any capability for introspection, Matuschak’s essay ought to make you think. Here’s some of what he wrote:

And at least for non-fiction books, one implied assumption at the foundation: people absorb knowledge by reading sentences. This last idea so invisibly defines the medium that it’s hard not to take for granted, which is a shame because, as we’ll see, it’s quite mistaken.

Picture some serious non-fiction tomes. The Selfish Gene; Thinking, Fast and Slow; Guns, Germs, and Steel; etc. Have you ever had a book like this—one you’d read—come up in conversation, only to discover that you’d absorbed what amounts to a few sentences? I’ll be honest: it happens to me regularly. Often things go well at first. I’ll feel I can sketch the basic claims, paint the surface; but when someone asks a basic probing question, the edifice instantly collapses. Sometimes it’s a memory issue: I simply can’t recall the relevant details. But just as often, as I grasp about, I’ll realize I had never really understood the idea in question, though I’d certainly thought I understood when I read the book. Indeed, I’ll realize that I had barely noticed how little I’d absorbed until that very moment. . . .

All this suggests a peculiar conclusion: as a medium, books are surprisingly bad at conveying knowledge, and readers mostly don’t realize it. . . .

Like lectures, books have no carefully-considered cognitive model at their foundation, but the medium does have an implicit model. And like lectures, that model is transmissionism. Sequences of words in sequences of lines in sequences of pages, the form of a book suggests people absorb knowledge by reading sentences. In caricature: “The author describes an idea in words on the page; the reader reads the words; then the reader understands the idea. When the reader reaches the last page, they’ve finished the book.” Of course, most authors don’t believe that people learn things this way, but because the medium makes the assumption invisible, it’s hard to question. . . .

I take this critique seriously. Matuschak posits that what is essentially a written lecture — a bunch of sentences strung together — makes it difficult for the a readers to acquire and then internalize what they are supposed to be learning. And when a book is no more than a bunch of declarative sentences, he may be right.

Why books are better than Matuschak thinks

Let’s go back to Matuschak’s test of whether a book hits home: when asked, can you recall and spit back the thesis and elements of a book?

Even if you can’t, that doesn’t mean those ideas aren’t in there. The inability to articulate them aloud is not the same as not having retained much.

Think about what non-fiction books are made out of.

They include overarching principles. Matuschak and I agree, if those are any good, people retain them.

There are the arguments that support those principles. Sometimes people retain those arguments, sometimes they don’t. But you don’t have to see the framing to understand how the building stays up. I’d argue that retaining the arguments is less important.

There are subsidiary ideas. A good book has lots of those. And a reader is going to recall those subsidiary ideas only to the extent that they are relevant for her. If there are 15 subsidiary ideas and three are relevant for you, those three may be sufficient. If a book is really useful, you may retain more.

There are also, in any given book, hundreds of bits of knowledge. There are facts, statistics, diagrams, and, crucially, stories. There are long case-study stories and short “for example” stories. When the author chooses these bits and delivers them well, the reader retains them.

For example, readers of Writing Without Bullshit may quote back to me that 81% of business readers say that poorly written material wastes a lot of their time. Or they may remind me of the story about the 1,100-word email that Microsoft’s Stephen Elop wrote, the one that buried the lede — 12,500 job cuts — 80% of the way through.

The last thing to remember is that even if you can’t spit something back, it may still be in there. People who read my book may be able to tell you to put the most important information up front, but they may not recall the specific technique — cut opening paragraphs until you find one that you can’t cut — until they actually need it. It’s amazing what’s hiding in your head, waiting for the moment that it becomes relevant.

Making your book better

I agree with Matuschak that when a book is a lecture, delivered from on high by the almighty expert to the poor ignorant plebes that are reading it, it probably won’t be retained well.

So don’t write this way.

Here are some simple tricks to make your book useful and make its ideas stick.

  • Write directly to the reader, using the words I and you. When people see prose directed at them, they sit up and take notice. You should talk to your boss about this, for example, or I’ll repeat this since it’s going to change the way you work forever. Writers trained on academic prose never think of this technique, because academics rarely write this way — they’re in almighty expert mode. But if you want people to retain what’s in your book, you have to adopt this tone.

  • Tell stories. People retain stories. The more relevant stories you have, the more they will retain.

  • Ask rhetorical questions. This makes the reader think and wonder if they’re getting it. It wakes them up from the litany of declarative sentences.

  • Include graphics. Put the same information in text, in headings, and in graphics. Most people retain pictures better than words. Everyone retains information presented in several different forms better than information presented in only one form.

  • Vary presentation. Use quotes, links, heading, subheadings, bulleted lists, numbered lists, tables, and anything else that breaks up the march of sentence after sentence, paragraph after paragraph. This keeps the reader engaged and makes it easier to scan the book and understand its structure.

  • Introduce and sum up. As the saying goes, “Tell ’em what you’re gonna tell ’em, tell ’em, then tell ’em what you told ’em.” To reinforce ideas, prepare people for what they are about to read before they get there. When it comes to summing up, a great tip is to include a bulleted list of takeaways — things you can actually do differently based on what you read. That makes readers more likely retain it.

This is not a complete list, but you get the idea. Work a little harder on using all the capabilities of writing, not just a dictated lecture, and you’ll improve retention. Here’s how I’d restate Matuschak’s thesis: The problem is not that books don’t work, it’s that lazy, boring books don’t work.

If you follow my advice, you’ll get a bonus, too. When people retain the ideas in a book, they talk about it. When they talk about it, other people hear about it and read it — and the book becomes more influential and successful. That’s what you’re aiming for, isn’t it?

<https://bernoff.com/blog/why-books-work-a-rebuttal-to-andy-matuschak> <https://bernoff.com/blog>


Brad DeLong here: Bernhoff is a business-writing coach.

Leave a comment

Bernhoff believes that the medium of the book is fine, and that fault lies with lazy, lecture-style authors (and editors!). Plus he believes that readers keep far more than they can recite on command. Recite-on-command is not how we recall knowledge. Retention is selective and latent. Plus good writing technique raises retention substantially.

Now Bernhoff is, I think, answering a question different from the one Matuschak asked. Matuschak’s call is to build a new medium to fight the assumption of “transmissionism”, that people learn via absorbing knowledge by reading sentences linearly. Bernhoff replies by saying that rhetoric has an at least 3000 year-old history of techniques to fight “transmissionism” in its arsenal.

It is true. There are good things: talk to the reader, tell stories, ask rhetorical questions, add graphics, tell ‘em what you’re gonna tell ‘em, and tell ‘em what you told ‘em. These are all very good things! But even granting them all, Bernhoff misses Matuschak’s sharpest point. Matuschak’s complaint is not just that he forgets details. It is that when someone asks a basic probing question, he discovers he never really understood the idea in the first place, and never noticed. Vivid stories and rhetorical questions may well help a reader recall the memorable bits. Engagement, however, is not understanding, and a failure of comprehension is not a failure of memory.

Bernoff focuses on the author, not on the reader. Thus he misses the cognitive science of retrieval practice, spaced repetition, query-and-response, bringing in of additional information and the burden of self-monitoring, the “metacognition” that successful deep-reading requires. His principles for writing encourage these. But he does not look at what happens after the author finishes their work. It is Matuschak who offers advice to the reader here:

Readers can’t just read the words. They have to really think about them. Maybe take some notes. Discuss with others. Write an essay in response. Like a lecture, a book is a warmup for the thinking that happens later. Great: that’s a better model! Let’s look at how it plays out…. [The] people [who] do absorb knowledge from books… [have]inner monologues… like: “This idea reminds me of…,” “This point conflicts with…,” “I don’t really understand how…,” etc…. Unfortunately, these tactics don’t come easily…. These skills fall into a bucket which learning science calls “metacognition.” The experimental evidence suggests that it’s challenging to learn these types of skills, and that many adults lack them…. Worse, even if readers know how to do all these things, the process is quite taxing…

Refer a friend

Bernhoff’s essay would, I think, be more effective with an explicit bridge from what the author does, rhetorically, to what the reader needs to do, metacognitively.

Note, too, that Bernhoff’s model case is the practical business book, where the point is to remember three relevant tips and know where to look up the rest. Matuschak’s examples were The Selfish Gene, Thinking, Fast & Slow, and Guns, Germs, & Steel: dense explanatory works whose whole principal value lies in the reader genuinely understanding a causal argument.

There, perhaps, different rules apply. There, perhaps, Matuschak’s worries (and hopes for new technology-enable media) apply much more significantly.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-josh-bernhoff-2019-why-books-work-a-rebuttal-to-andy-matuschak
##public-reason
##crosspost
#josh-bernhoff-2019-why-books-work-a-rebuttal-to-andy-matuschak
#osh-bernhoff
#2019-why-books-work-a-rebuttal-to-andy-matuschak
#andy-matuschak
#why-books-work
#why-books-dont-work
#transmissionism
#metacognition
#deep-reading
#cognitive-science
#reading-comprehension
#rhetoric
#new-media

CROSSPOST: JONATHAN V. LAST: Neo-NeoFascism Watch: Welcome to JD Vance 6.0

Vance’s 2028 6.0 OS is new. In succession, he has been: memorist, never-Trumper, MAGA edgelord, the right-wing version of Elizabeth Warren,and loyal veep attack-dog. Now he is the amnesiac heir:

Jonathan V. Last highly annoyed by JD Vance.

Share

He has good reasons.

Briefly, Jonathan Last’s take: Vance wants to inherit the MAGA coalition without inheriting its record. So he defends the Iran war in public while whispering opposition to access journalists. He denies Trump’s corruption while conceding Washington is corrupt. He apologizes for “imperfect” rhetoric while still blaming immigrants. Pure arsonist-firefighter stuff. Will voters buy it? This is a deeply unserious party he is aiming to lead.

Give a gift subscription

We have Jonathan V. Last:

CROSSPOST: JONATHAN V. LAST: Neo-NeoFascism Watch: Welcome to JD Vance 6.0

<https://www.thebulwark.com/p/welcome-to-jd-vance-60-cbs-town-hall-vice-president-iran-corruption-immigration> <https://www.thebulwark.com/>

The Bulwark
Welcome to JD Vance 6.0
1. Frontier Models…
Read more
Everything is going great. And if it isn’t great, he has no idea how we got here.

Jonathan V. Last

October 19
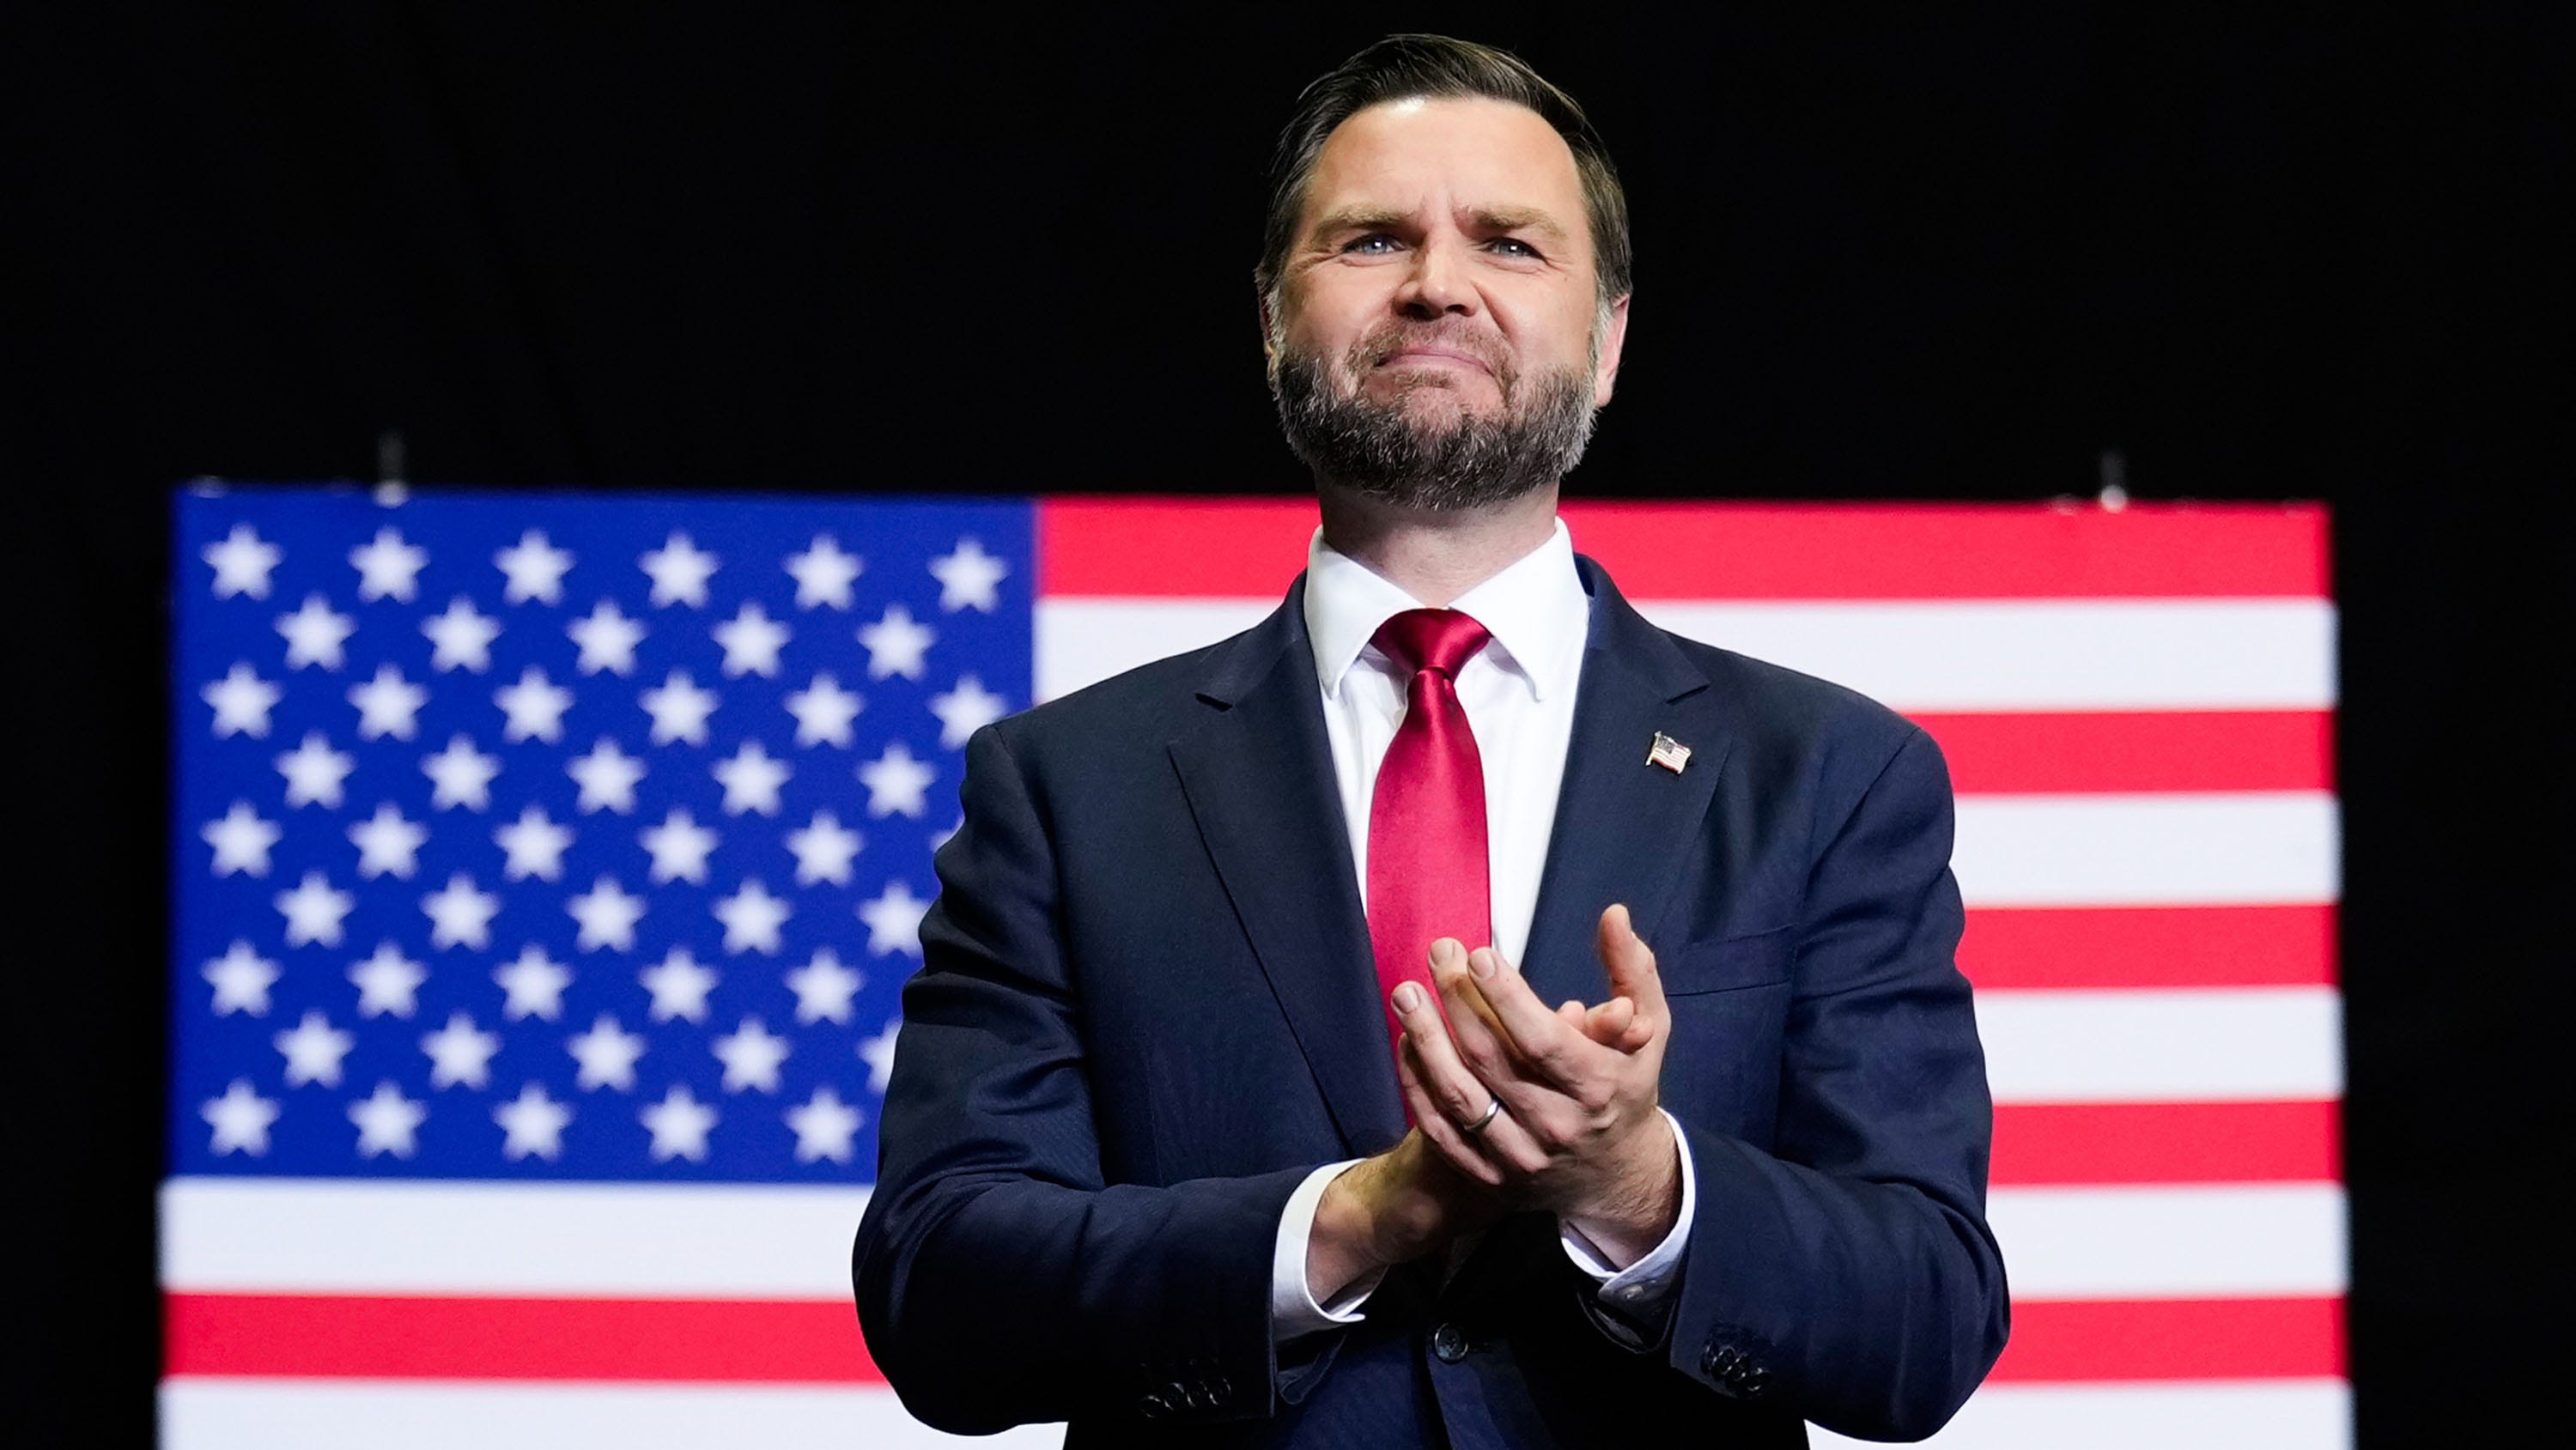
Vice President JD Vance applauds as he takes the stage during a midterm campaign rally at the LevelUp Training Complex on October 15, 2026 in Monroe, Michigan. (Photo by Daniel Heuer-Pool/Getty Images)

1. Frontier Models

Back during the 2024 campaign I wrote about the 4.0 operating system upgrade that had been loaded onto the JD Vance platform.

Vance 1.0 was a memoirist and Hillbilly whisperer.

Vance 2.0 was a Never Trump pundit.

Vance 3.0 was a MAGA edgelord.

Vance 4.0 is something like a cross between 2010 Elizabeth Warren and 2016 Marco Rubio, with some light nativism sprinkled in.

Vance 4.0 was the Windows ME of the Vance platform. After November 2024 a new update shipped—the 5.0 VP Edition. But it was just a rebadged 3.0. As vice president, JD ran around slandering Americans killed by his police state, but in January we got an important patch—JD 5.1. The key upgrade on 5.1 was a backchannel feature that allowed the vice president to leak to reporters about how vehemently he disagreed with Donald Trump while publicly defending his boss. On Saturday, Vance Tech marked the soft launch of its 2028 presidential campaign with the unveiling of JD 6.0 at an event hosted by Bari Weiss’s CBS News. Let’s examine the new New JD not through the lens of politics or morality, but as a product—with an eye toward the question: Will it work?


2. Three Stars?

Overview: Vance 6.0 is a reintroduction of the product to a dissatisfied consumer base. The last two years have seen Donald Trump—the parent company of Vance Tech—lose customers at a rapid rate. Once the industry leader, Trump is now close to matching the record for the most unpopular president three weeks before a midterm election ever.1 Vance 6.0 comes to market with an audacious plan: He pretends that he has no idea how we got here, but is now ready to come up with solutions. Probably. Just none that he can share at this very moment.


Iran: The biggest problem Vance faces is the war against Iran that Donald Trump chose to initiate and has subsequently lost. Vance can spin reporters by publicly defending Trump and the war while privately reassuring access journalists that he is against the war. (Annoyingly, Vance Tech has yet to figure out how to communicate with voters on deep background.)

Vance 6.0 squares that circle with a couple of innovations. On Saturday Vance insisted that the war has been a total success. Sort of. Asked why America has not won the war decisively, Vance replied, “I would say in some ways we have won decisively.”2 He then went on to allow that maybe, perhaps, in other ways, the war is still on the journey to success: “The enemy gets a vote here,” Vance explained. “And they have responded in certain ways.”

“Certain ways” is an elegant euphemism for destroying the most important U.S. naval facility in the region, crippling key energy infrastructure, seizing control of the Strait of Hormuz, destabilizing regional alliances, and elevating China’s influence. The key here is how Vance reduces specific military outcomes and economic developments into pleasant abstractions. It’s really quite something.

The next feature is Vance’s ability to shift from saying that, in many ways, everything is going great, to declaiming that he has no idea how any of the bad stuff happened.

I see what Abdul El-Sayed says about the war in Iran. I see [him] criticizing decisions that the president has made, the military has made. But fundamentally, we are where we are. And you have to—in my view, I’d like to know: What is Abdul El-Sayed’s solution for the problem that we have right now?

We are where we are! How did we get there? It’s a mystery! And while JD Vance does not, himself, have any solutions for the problems (which probably don’t exist), he’s pretty sure that Democrats don’t, either. So really, when you think about it, they’re kind of the ones to blame?


Corruption: Asked if he was bothered by the obscene corruption within the Trump administration, Vance applied the same processes:

First of all, if someone’s selling access to the White House, that’s disgusting and despicable and they should suffer consequences… . I want to make those judgments based on the facts and not based on a random news media report that I read… . I’ve seen these media reports, and I have the same reaction I imagine a lot of people in this room have, which—it makes me uneasy when I read about my public officials potentially getting wealthy off of my public trust. And I’m telling you that while, yes, D.C. is a corrupt town … Donald Trump—I have not seen a single shred of evidence that he participates or sanctions in that corruption… . I have not once seen evidence that Donald Trump has enriched himself.

Let’s break that down step by step.

First, the thing people expect to hear. In this case it’s not “We’re winning” but “corruption is not allowed.” Check.

But then the actual evidence gets a little messy. He wants facts—not just media reports. Which include text messages from Kimberly Guilfoyle to the guy she was asking for bribes. Which the guy in question, Eric Deters, has confirmed repeatedly and publicly. As with the Iran war: Sure, there’s evidence blatantly proving I’m wrong, but I prefer to rely on some secret other set of evidence that, if it exists (it doesn’t), I can see but you can’t.

Then he allowed that yes, corruption is endemic in Washington, but he, himself, has not witnessed any. Maybe some public officials are “potentially” getting rich off the public trust because that’s just how D.C. works, but never ever ever the people who are the most flagrantly and unabashedly corrupt of all.


Immigration: When forced to reckon with the words of Vance 3.0—for example, when he openly lied about Haitian immigrants—the new model attempted contrition. Asked by a member of the audience, “Why are you scapegoating immigrants for the issues you’re supposed to be solving as a vice president?” Vance responded: “I would say, and to the extent that my rhetoric has been imperfect here, that’s on me.” And later:

I will tell you that nobody’s perfect, certainly not me. But my goal here is not to dehumanize any immigrant. And in fact, I love a number of immigrants. My goal here is to make it so we can have a country with some baseline of social cohesion and sense of community, because … when too many people come to the United States too quickly, it changes the country in very profound ways.

This is pure arsonist-firefighter stuff. Vance has spent the last six years demagoguing immigrants—openly lying about them. He has taken a box cutter to the fabric of American society in order to win votes. And now he says that he only does it to preserve “social cohesion.” Like Iran, like the corruption, Vance has no idea how America got to this place. And he doesn’t offer any solutions. But he wants voters to know that he’s truly, deeply concerned.

Will this work? I don’t know. But however distasteful you may find this new version of JD Vance, you shouldn’t discount the possibility that it might work. We are a deeply unserious country populated by deeply unserious people.


Notes:

1 Some polls have Trump as low as 33 percent approval. Harry Truman was at about 33 or 34 percent approval shortly before the 1946 midterms. So Trump still has time to make history.

2 You see, the only way to understand the outcome of a war is to break it into component parts and evaluate each individually. For instance, in World War II, Japan conquered big parts of China before being bombed into submission by the United States. So in some ways, Japan won a decisive victory against China, even if, in other ways, Japan suffered defeats. By the same token, America has totally, completely demolished the Iranian navy. Now this has fuck-all to do with the actual strategic outcome of the war. But in some ways it’s a decisive victory!

<https://www.thebulwark.com/p/welcome-to-jd-vance-60-cbs-town-hall-vice-president-iran-corruption-immigration> <http://thebulwark.com>

The Bulwark
Welcome to JD Vance 6.0
1. Frontier Models…
Read more


Brad DeLong here: The first such of which Vance might be aiming to become was Napoleon III, or perhaps Napoleon the Great.

Share DeLong’s Grasping Reality Weblog

The coup of the 18 Brumaire (November 9, 1799) was followed by a plebiscite in which Napoleon’s new constitution with himself as First Consul of the French Republic was “approved” by a reported 3,011,007 votes in favour versus 1,562. Popularity—or at least the manufactured appearance of popularity—beats constitutional procedure, and elections are not on obstacle as long as the vote-count can be controlled, or at least cast into sufficient doubt that the real balance becomes a matter of he said-she said “observers disagree”. The lesson, I think, is that Al Gore focused on using constitutional procedures to get the votes counted, and lost. Thus a superior path is to claim that you won, and then to cut as many corners as you need to get your butt into the White House.

I find myself thinking about Sergei Guriev and Daniel Treisman’s Spin Dictators: The Changing Face of Tyranny in the 21st Century (Princeton, 2022), based on their 2019 Journal of Economic Perspectives article “Informational Autocrats”:

Guriev Treisman 2019 Informational Autocrats
746KB ∙ PDF file
Download
Download

Guriev and Treisman’s thesis is simple to state and far-reaching: In a modern society, the cheapest way to keep power is to be, or seem to be, popular, and to use that popularity to neuter the elements of the constitutional infrastructure that might push you out. Spin dictators therefore:

  • Hold elections and usually win them, with rules tilted, opposition hobbled, and media coverage skewed, but stuffing ballots so crudely that the result loses all credibility only under absolute necessity.

  • Simulate democracy rather than denounce it by keeping parliaments, courts, parties, and NGOs, but capturing them and hollowing them out, all the while speaking the language of democracy, rule of law, and popular will.

  • Censor quietly, buying outlets through friendly oligarchs, squeezing them through advertising and regulation, and sueing them for defamation

  • Repress selectively and in disguise with violence rare and targeted, and dressed up as ordinary law enforcement: immigration violations, mortgage fraud, with critics are prosecuted, bankrupted, or pushed into exile.

  • Avoid grand ideology and favor flexible, catch-all appeals to resentment of outsiders and élites, to national pride, to stability, to competence, an d to prosperity,

The leader has to persuade enough of the broad public that he is on their side, is competent, and that the alternatives are worse. He has to buy and create—using plutocrat-kleptocrat money—an appearance of some support among the informed. he can then contain the informed tranche of the population that knows enough to understand. The job not of information control but rather of flooding the zone is to manufacture and protect that appearance of popularity, so that corner-cutting leads to political squabbles while his actions create facts on the ground that then become fixed points other actors must accommodate themselves to. And it might work, with enough banks, lawyers, PR agencies, lobbyists, consultants, and and others on his side to launder both money and reputations, and cast doubt. After all, actually winning one election—as Trump did in 2024—and gaining one set of congressional majorities freezes the opposition’s ability to oppose, as it does not feel it has the legitimacy to enforce strict constitutional procedure when you can always find a lawyer and often six Supreme Court justices to lie about or at least confuse and postpone resolution of questions of what constitutional procedure truly is.

In short: soft dictatorship, less like a prison and more like a con, with the central resource being a popular—or a popular enough among those who are legitimately full citizens—belief that things are going well.

In his first term, the analogues of Hermann Göring, Josef Goebbels, and Reinhard Heydrich did not show up for Donald Trump. Now, in Trump’s second term, JD Vance is auditioning for the slot(s)… Fantasy, Nazi mobilization, online memes, bomb threats, then bureaucratized ethnic cleansing—this is what Vance is about to try to test in Springfield, Ohio. America’s soul really is at stake here…

Why is JD Vance trying to make war on prosperity? Because the Vance-Trump policy agenda he has been one of the principal architects of is, as it was clear from the get-go, a miserable failure in terms of making a middle-class American lifestyle more affordable. It is about distracting people from the fact that nativism and protectionism make America smaller, poorer, meaner, and globally disrespected…

  • Same post:

The neo-fascist version of post-liberalism argues that “the belly may be full, but the spirit will be empty.” But their actual proposal is not to fill the spirit; it is simply to empty the belly, while pretending the resulting hunger is actually a form of spiritual discipline.

And, of course, JD Vance is positioning himself to be the leader of the MAGA movement after Trump’s forthcoming exit into complete senility. And he is doing so by demonizing immigrants and their children as not real Americans, and so throwing his own wife Usha and his own children—Ewan, Vivek, Mirabel, and Alec—under the bus.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-jonathan-v-last-neoneofascism-watch-welcome-to-jd-vance-60
##neofascism
##crosspost
#jonathan-v-last-neoneofascism-watch-welcome-to-jd-vance-60
#jonathan-v-last
#neoneofascism-watch-welcome-to-jd-vance-60
#jd-vance
#neoneofascism
#vance-6-0
#amnesiac-heir
#arsonist-firefighter
#spin-dictators
#informational-autocrats
#guriev-and-treisman
#soft-dictatorship
#immigrant-scapegoating
#maga-succession
#2028-election

Torsten Slok Beats the AI-Bear Drum: CHARTS OF THE DAY

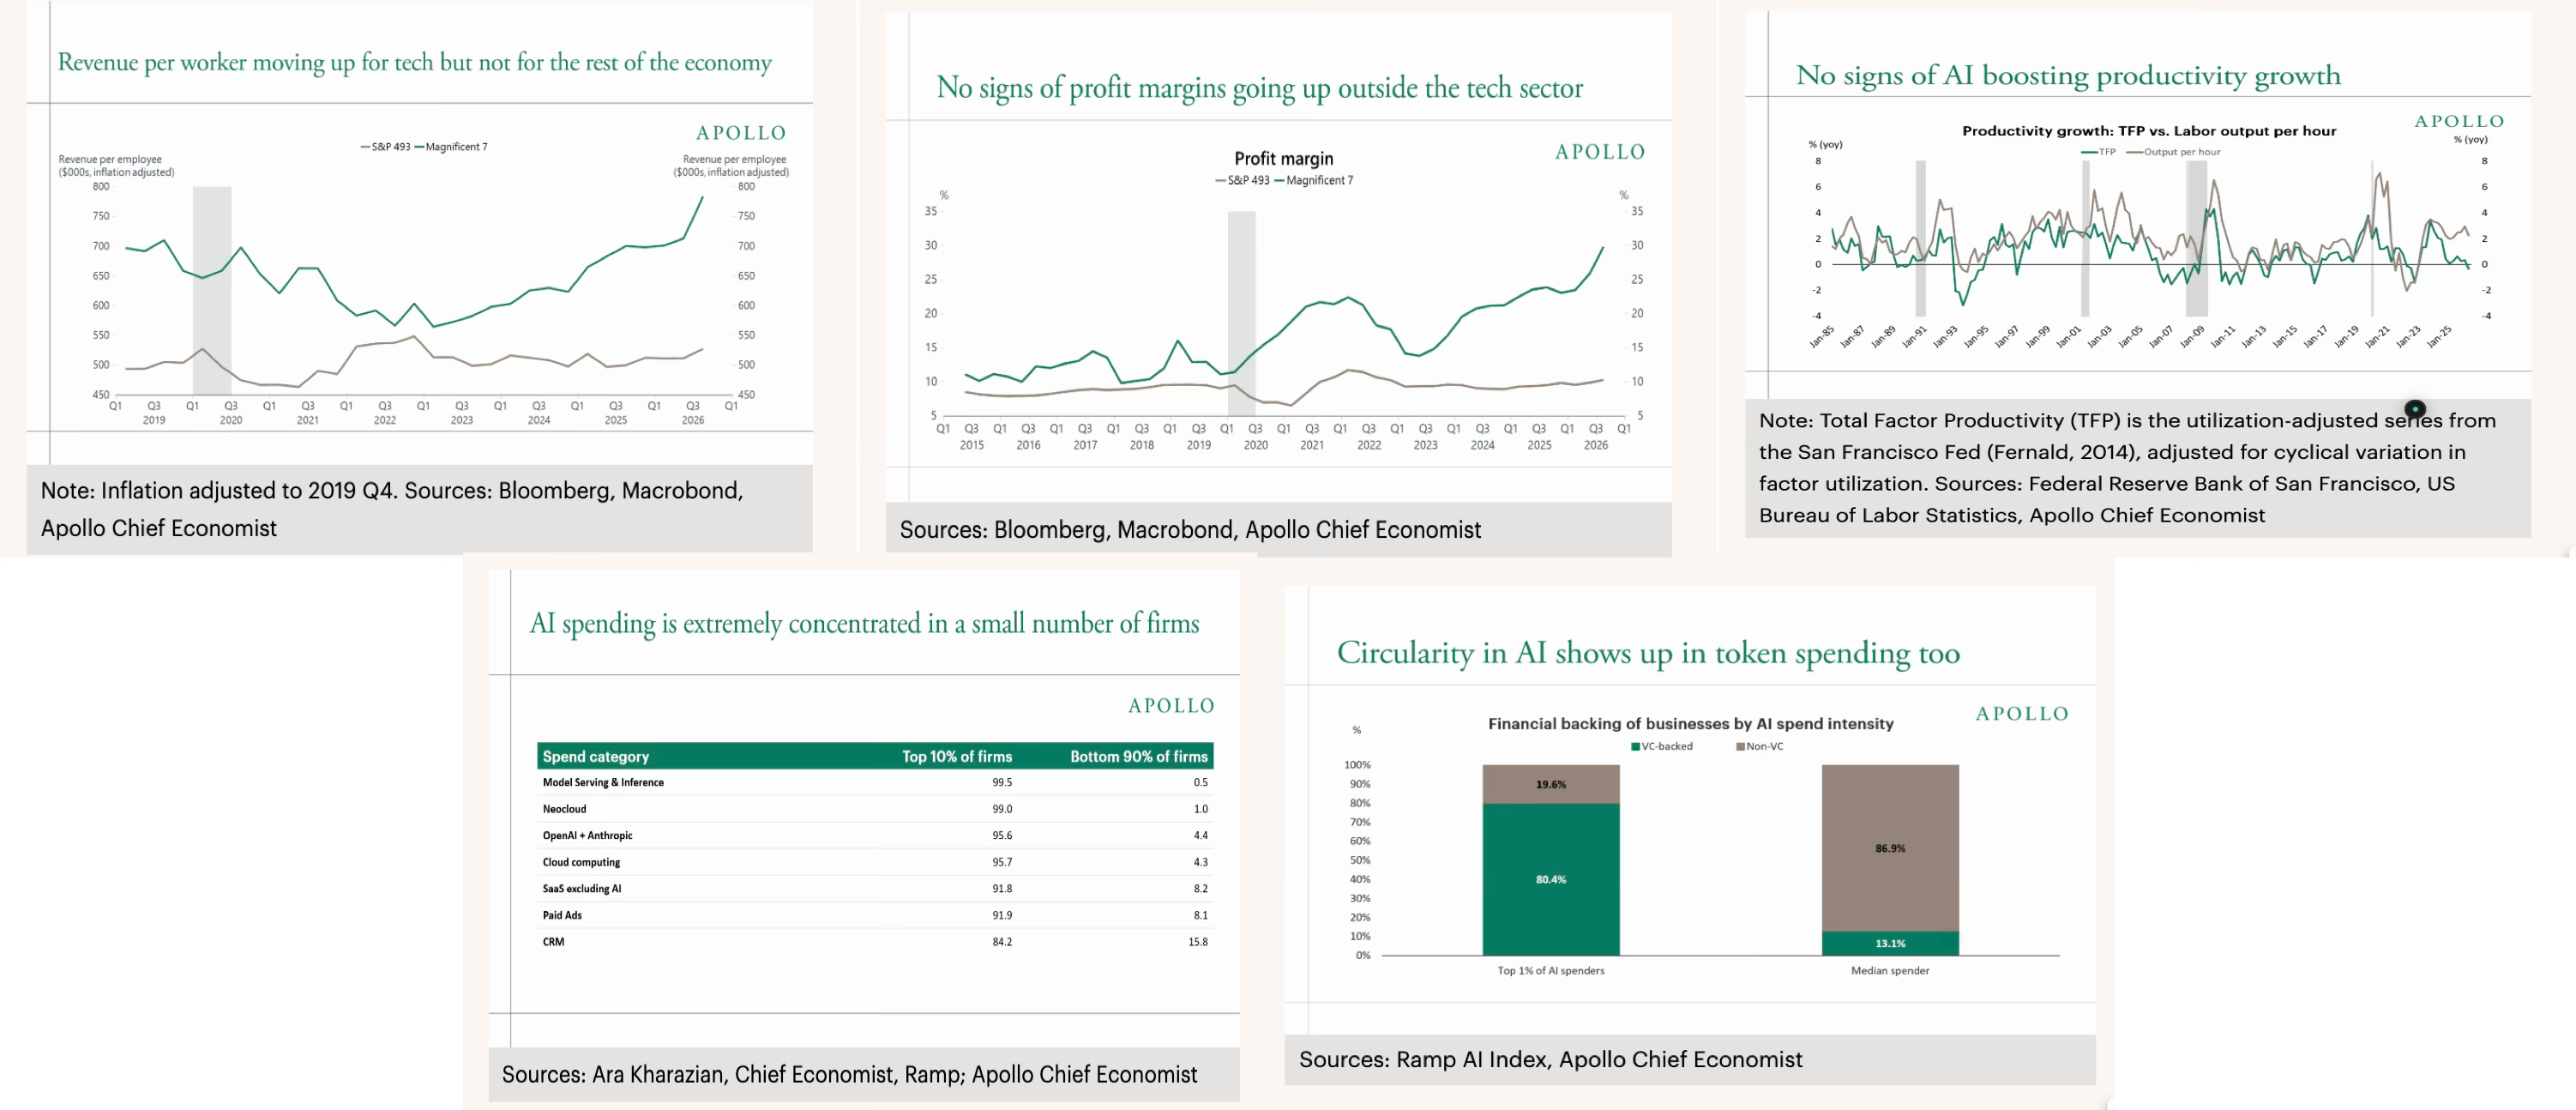
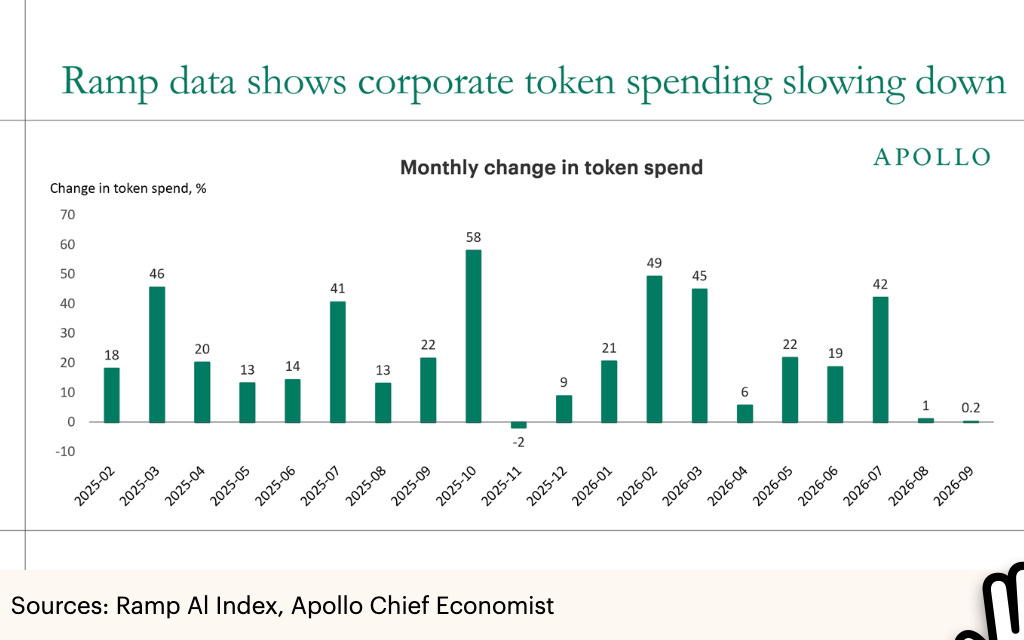
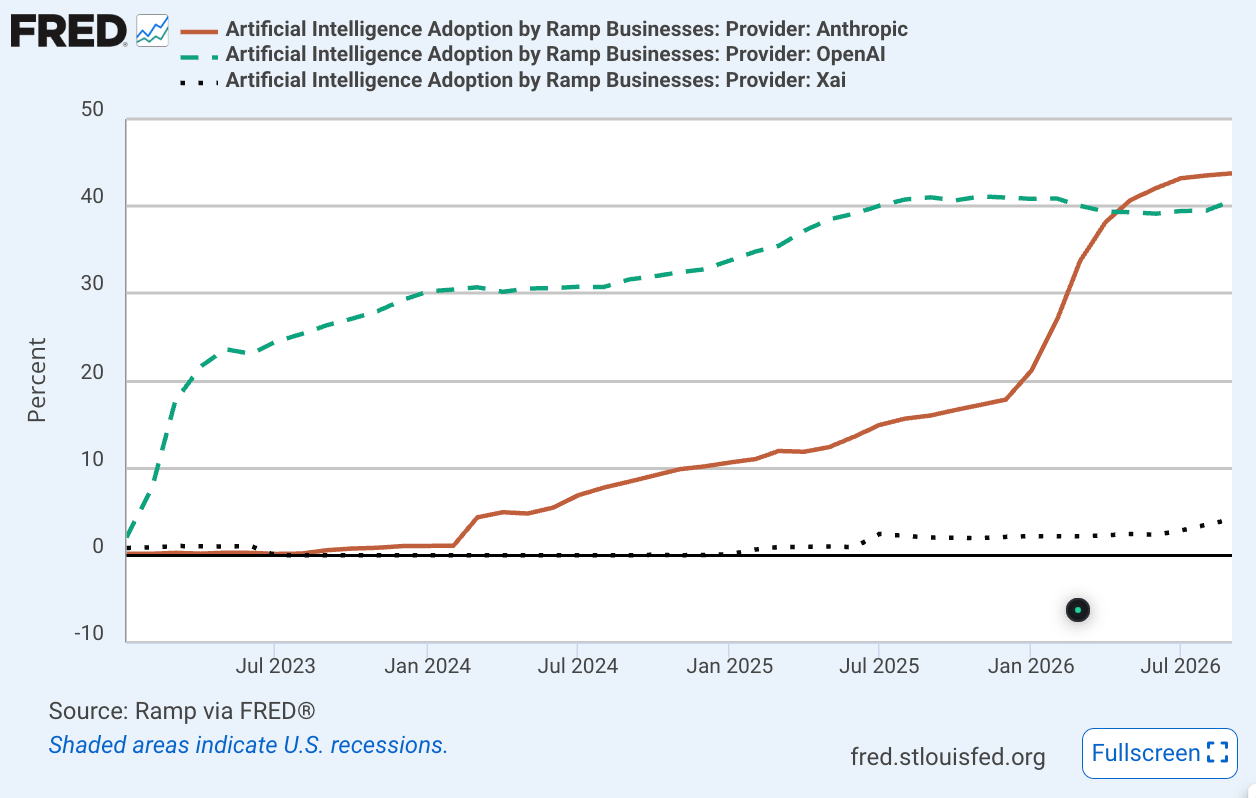
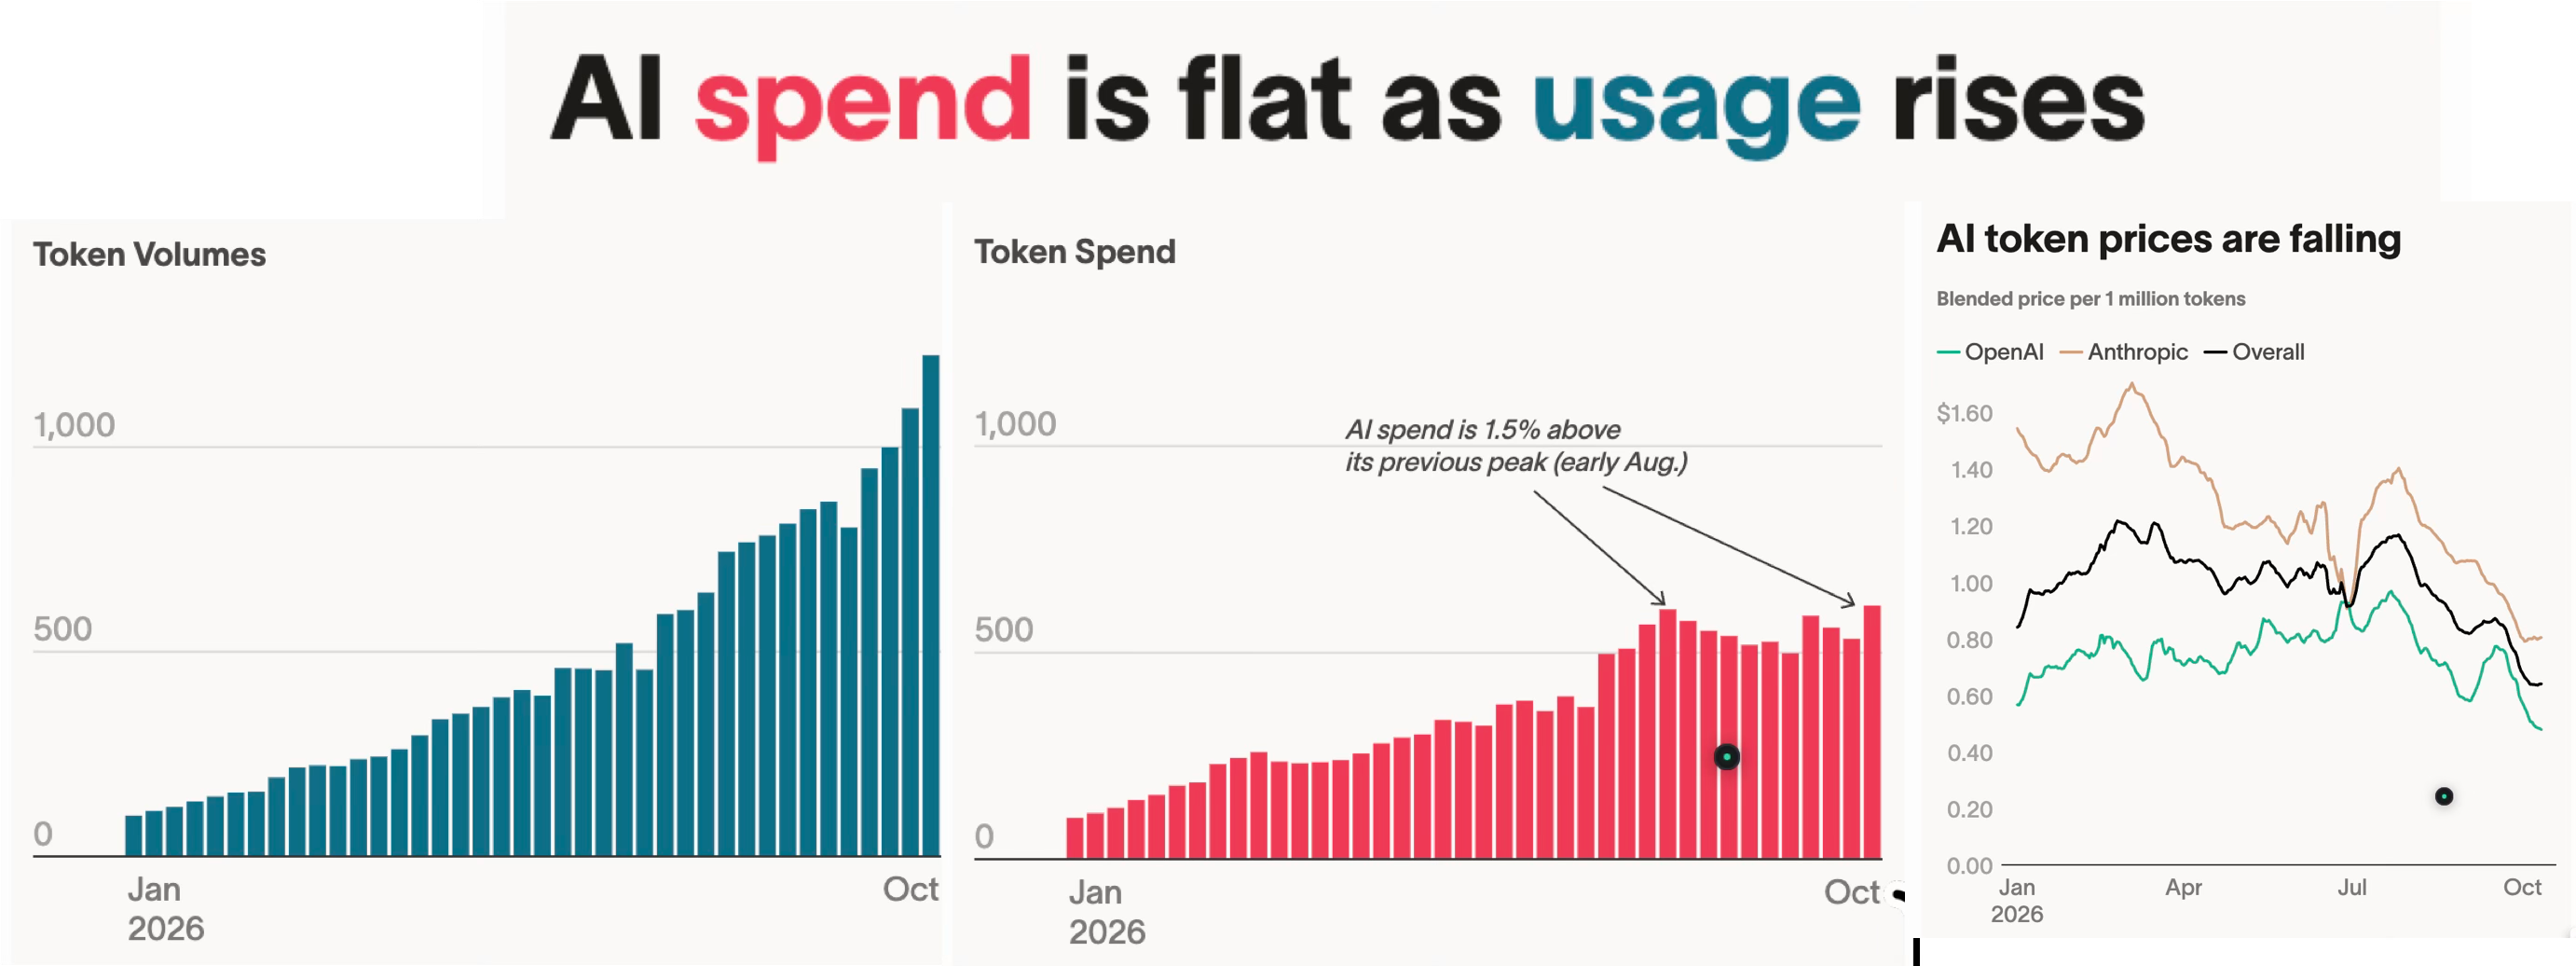
Torsten Slok’s charts show AI’s bullwhip in motion. The tip cracks and the body moves fast, but the handle, the S&P 493, doesn’t budge. Outside tech, revenue per worker and profit margins are flat, and measured productivity shows no AI boost. AI’s biggest effects are comeingthrough channels shareholders can’t easily capture: surplus going to users, new businesses entering, and platform incumbents locking customers in tighter. And last one helps a few firms, not the S&P 493…

Torsten Slok’s reading:

Share

Yes, the bullwhip cracks at the tip, and the body of the whip is moving very fast, but the handle and the wielder are not moving at all. These things are simply not very useful. At least, not yet. And not for the existing firms that are in the S&P 493:

Give a gift subscription

He comments:

Torsten Slok: No Signs of AI Payoff Outside the Tech Sector <https://www.apollo.com/wealth/insights-news/insights/daily-spark/no-signs-of-ai-payoff-outside-the-tech-sector>: ‘Despite massive investments and widespread hype around artificial intelligence, the technology has delivered zero financial payoff to corporate America outside of tech. Revenue per worker is… flat for the S&P 493…. Profit margins are… flat for the S&P 493…. No signs of AI boosting [measured] productivity growth…. Mainstream corporate America is pulling back and starting to view token spending… as a cost center…. Mainstream corporate America does not need the latest model and is unwilling to pay for it. As long as agentic AI and token spending are confined to a small part of the economy, the macroeconomic effects of AI will be very limited, see the fourth and fifth charts…

Leave a comment

User surplus, which I think is massive. (But beware the monkey’s paw! Whether we actually need what we think we want in terms of information and communications technology is a deep and complicated multi-dimensional question.) New businesses. And whether the existing platform monopolists will be able to capture more money by finding ways to use “AI” to deepen their moats and further lock-in their customers. Those seem to me more likely to be the big issues than a massive boom in measured GDP and measurable productivity.

If so, one has to really be a debbie-downer with respect to the rationality of current market valuations.

Additional, important things for me to go and read (or reread) now:

  • Fed Governor Lisa Cook, “An Update on AI and the Economy” (Sept 28, 2026, Oakland): Linking AI tools to the recent boom in new business formation, and warning about risk that “market concentration leads to less competition and higher markups” via platform-moat entrenchment… <https://www.federalreserve.gov/newsevents/speech/cook20260928a.htm>

  • Sacher, Cotter, Charles I. Jones, Anton Korinek, & Peter McCrory, “The AI expectations gap” (Anthropic research): Among U.S. adults using workj AI, 26% say it cuts a task to a quarter of the time or less, against 59% of Anthropic staff; 5% of workers vs. over half of staff say AI could do 80% of their own jobs by 2030… <https://www.anthropic.com/research/ai-expectations-gap>

User surplus and moat-deepening are huge stories and lf first-order importance for understanding the arriving attention info-bio tech mode of production. But they do not produce a hyperboom in measured GDP or an explosion in profits that justifies current market valuations.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##torsten-slok-beats-the-ai-bear-drum-charts-of-the-day
##attention-info-bio-tech-economy
##mamlms
##chart-of-the-day
#torsten-slok-beats-the-ai-bear-drum-charts-of-the-day
#torsten-slok
#beats-the-ai-bear-drum
#ai-bear
#ai-productivity
#profit-margins
#token-spending
#agentic-ai
#user-surplus
#monkeys-paw
#new-business-formation
#platform-monopolies
#market-valuations
#ai-bubble
#crowding-out
#ai-expectations-gap

CROSSPOST: SASHA GUSEV: Vibe Heritability The EJW Symposium on Gregory Clark on Genetics & Social Mobility

Gregory Clark says the drop in English parent-child status correlations is a statistical mirage, and that genes have kept the same families on top since 1600. But Sasha Gusev shows, among other things, that taking Clark’s own numbers for spousal similarity in assortative mating seriously commits you to the nonsense finding that IQ is 200 percent heritable. The arithmetic of genetic determinism of social status simply cannot be made to work:

My friend Greg Clark takes aim at me in the foreword of his new book To Have & Have Not:

Share

A recent Substack essay by Brad DeLong, titled, Big Trouble in Little Human Genetic Difference-Worshipper Land, illustrates nicely the hostility and contempt felt by the academy for anyone who would suggest an important role for direct genetic determination of social outcomes:

“[A]ttempts to carve out a large, causal, manipulable “main effect” of genes on complex social outcomes keep reducing, on closer inspection, to approximately zero” (DeLong, 2026).

Thus an article in the Proceedings of the National Academy of Sciences, which contains the essence of the argument of the book, has been attacked by such prominent behavioral geneticists as Marcus Feldman and Kevin Lala as “scientific racism” (Lala and Feldman, 2024), and “racist pseudoscience” (Lala, Brown, Twyman and Feldman, 2025). Similarly a presentation of the core arguments of the book at Glasgow University in 2021 was indefinitely “postponed” by the Dean in response to a letter signed by 110 Glasgow University Faculty condemning the work as pseudo-science and eugenics. A majority of the reviewers at Princeton fell in solidly with the received wisdom on the unimportance of genetics, without seriously engaging with the copious empirical evidence presented that cultural and social causation could not explain the patterns of inheritance observed in England. Chicago University Press considered the manuscript, but ultimately reported that they could not find reviewers willing to review it!…

Give a gift subscription

But attempts to carve out a large, causal, manipulable “main effect” of genes on complex social outcomes do keep reducing, on closer inspection, to approximately zero! I understand that Greg does not like that conclusion. But it is one I have reached, and I have heard Greg (and many others) make their best pitch, and fail to throw anything I can regard as possibly over the plate!

More important, it is what Sasha Gusev thinks. In his estimation, Greg’s genes-only model of intergenerational human status immobility “for three of the four traits… produces an estimate of [genetic] heritability that is greater than 100% and a negative estimate of the shared environment variance…. These estimates are clearly absurd…”

Sasha:

CROSSPOST: SASHA GUSEV: Vibe Heritability

<https://theinfinitesimal.substack.com/p/vibe-heritability><https://theinfinitesimal.substack.com>

The Infinitesimal
Vibe heritability
The economic historian Gregory Clark has written a book on status persistence, which was the focus of a recent online symposium. Clark has assembled a massive dataset of multigenerational status measurements in England. The project has a particularly British whimsy to it, with much of the data coming from the Guil…
Read more
The EJW Symposium on Gregory Clark on Genetics & Social Mobility

Sasha Gusev

2026-10-12
Edward Ruscha, Various Small Fires, 1970

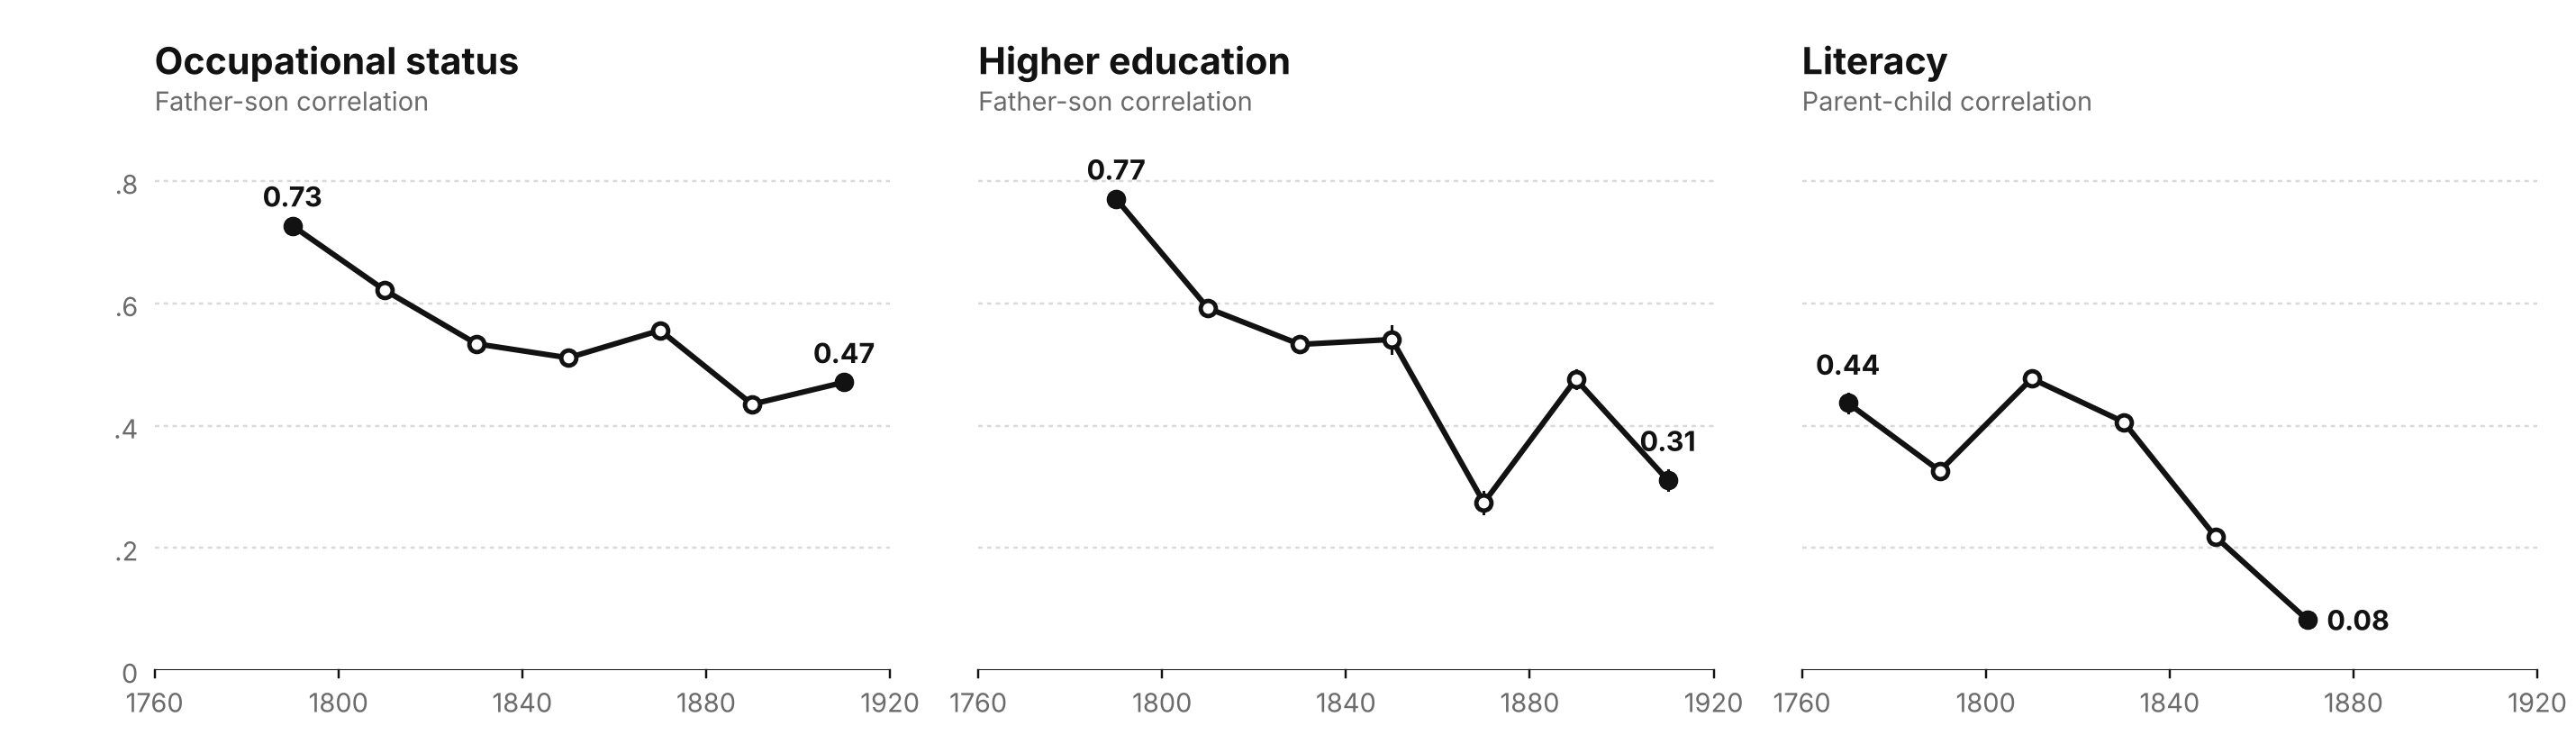
The economic historian Gregory Clark has written a book on status persistence, which was the focus of a recent online symposium. Clark has assembled a massive dataset of multigenerational status measurements in England. The project has a particularly British whimsy to it, with much of the data coming from the Guild of One-Name Studies, a largely online society of genealogical hobbyists. After analyzing lineages from >400,000 English people, Clark draws a startling conclusion that “genetics underpins social status in England from 1600–2026” — in other words, people are in the upper class and stay in the upper class because of their genes. Clark goes on to argue that “the vast resources poured into increasing rates of social mobility in modern society through public education, income supports, and social services have achieved nothing in terms of increased mobility”. This is a bold claim, so before going much further, it is worth taking a look at Clark’s data. Here are the parent-child correlations in social status traits, reproduced from an analysis of the data by Benning et al.:

Clearly the conventional estimate of social mobility — how similar in status are you to your parents — changed substantially. So how does Clark come to the opposite conclusion? Clark argues that the decrease in familial correlation is a mirage, driven by increases in measurement error. Instead, he proposes to quantify the rate of decay in the familial correlation across increasingly distant relatives, from which he infers large and unchanging latent parameters. These parameters, he argues, imply that status is highly heritable and highly genetically correlated between spouses, thus persisting across generations entirely through genetic pathways.

I and others have previously criticized Clark’s paper for conflating status persistence (through a variety of mechanisms), which his data can observe, with genetic causality that his data cannot identify. I also noted that Clark’s actual parameter estimates are nonsensical. These issues are echoed in some of the symposium articles in novel ways, which I will highlight here. I’ll also comment on the broader discussion in and around the symposium, which I think serves as a microcosm of the nature-nurture discourse.

The trouble with twins

Nikolai Eftedal (himself the author of a fascinating recent study of intergenerational persistence) contributed a short article, cheekily (by my reading) presented as an effort to “provide defenses against two criticisms [Clark] could face”. Eftedal points out that Clark’s model relies on a highly heritable, latent status phenotype that has extreme properties (“arguably so extreme as to be implausible”) and that his model makes impossible predictions about twins. Specifically, Clark’s model hinges on a very high level of genetic assortative mating, which would necessarily imply that monozygotic and dizygotic twins should exhibit only modestly different levels of phenotypic correlation. In Eftedal’s words: “for most relevant traits and outcomes, this is wrong”.

It may seem counterintuitive that a highly heritable phenotype would produce similar correlations between MZ and DZ twins, but it is a direct consequence of the genetic similarity induced by assortative mating. When parents are genetically correlated, DZ twins become more genetically correlated too while MZ twins remain identical, thus bringing the two classes of phenotypic correlations closer together. Classical twin studies, which assume random mating, will in turn estimate a large contribution of the shared environment and a low heritability for status traits (they generally do not). Here’s what that looks like for a highly heritable trait under random mating versus Clark’s spousal genetic correlation (m=0.57):

Under Clark’s model, a trait with heritability of 90% would actually appear statistically to have a heritability of 39% in twins. Eftedal attempts to throw Clark a lifeline by suggesting that large non-additive/interaction effects — which make MZ twins more similar but dissipate rapidly across generations — could reconcile the estimates from twin and family data. In his reply, Clark re-analyzes his dataset to identify sets of twins and siblings and estimate their phenotypic correlations. Among these twins and siblings, he concludes that “there is little sign … of significant non-additive effects”. In other words, he tosses the lifeline right back.

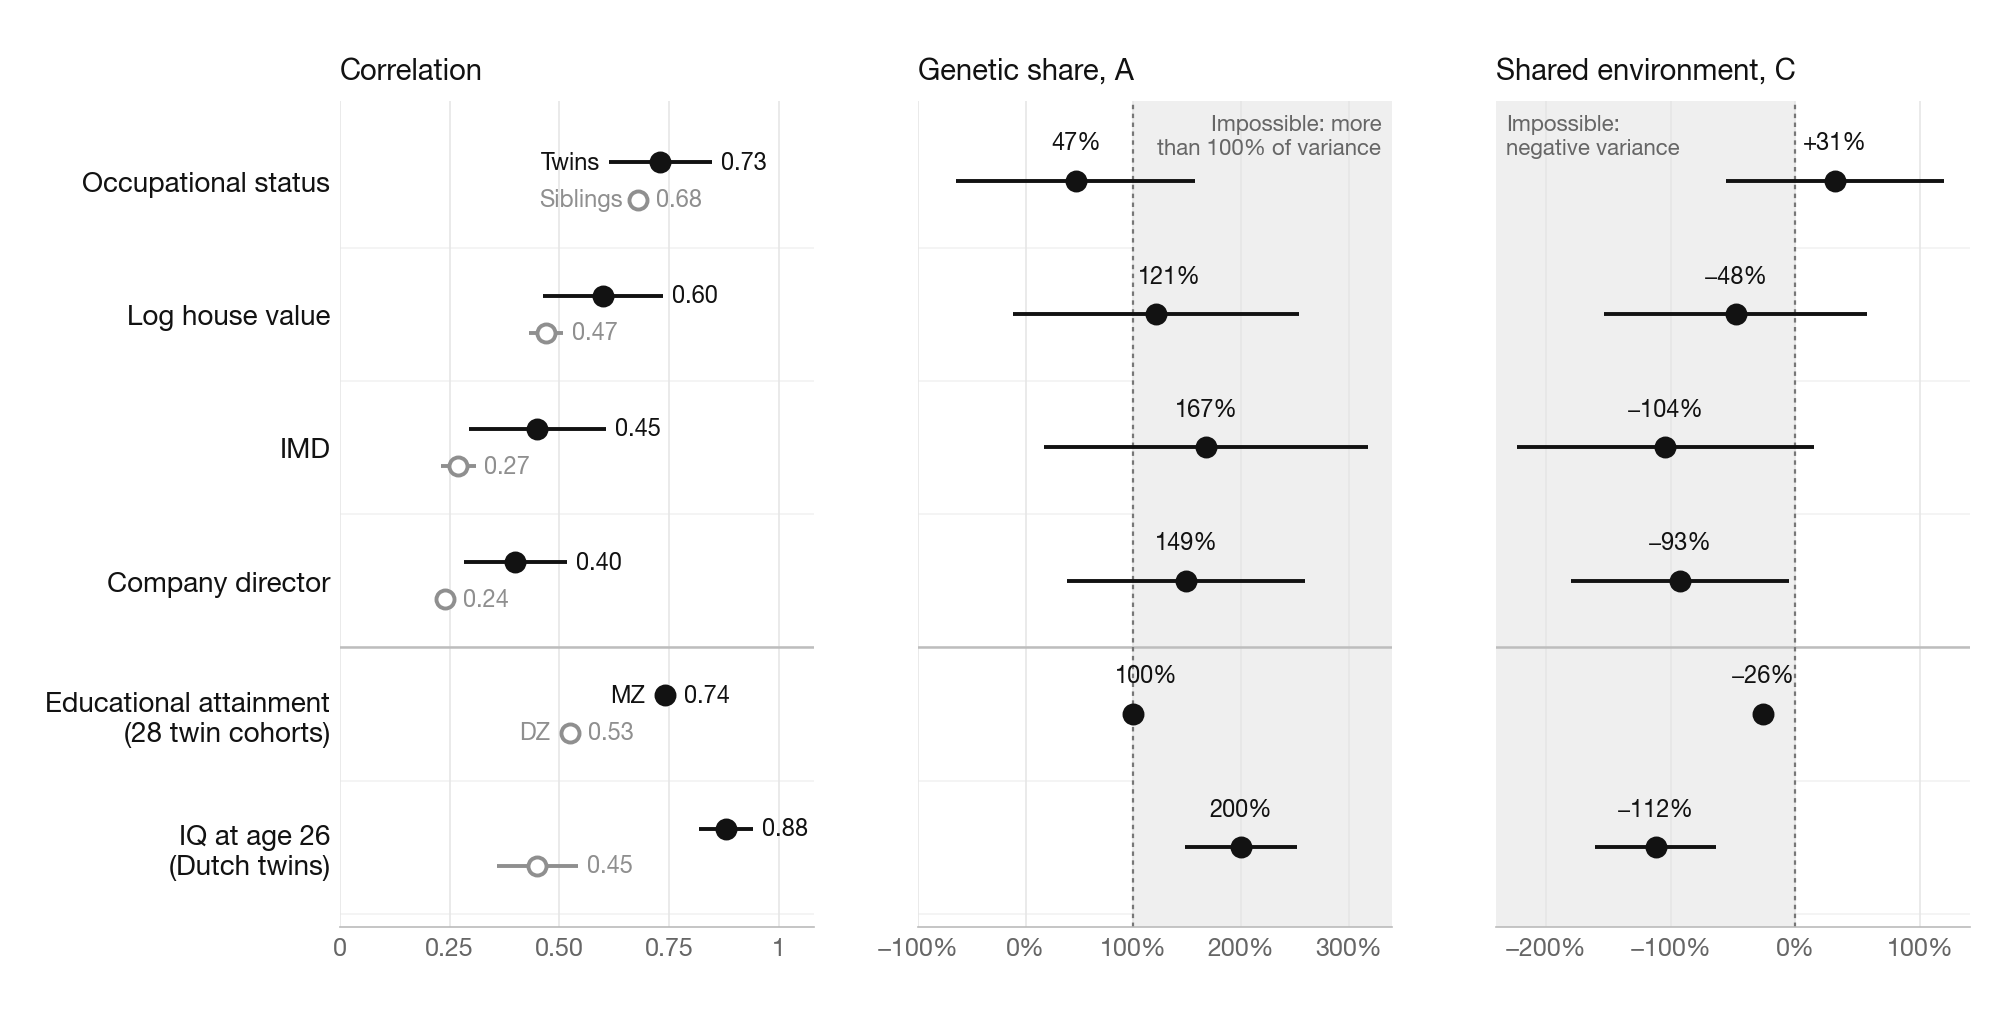
It seems that Clark may have missed the point of the exercise. Under assortative mating, it is not sufficient to eyeball the twin similarities, you need to estimate heritability after accounting for assortment. With a bit of algebra (see Appendix), we can derive a simple relationship between the correlations in Clark’s twins/siblings and underlying heritabilities while also accounting for the genetic correlation between mates estimated by Clark. Having done so, we can walk down the table of twin correlations from Clark and re-estimate the heritability his model would produce:

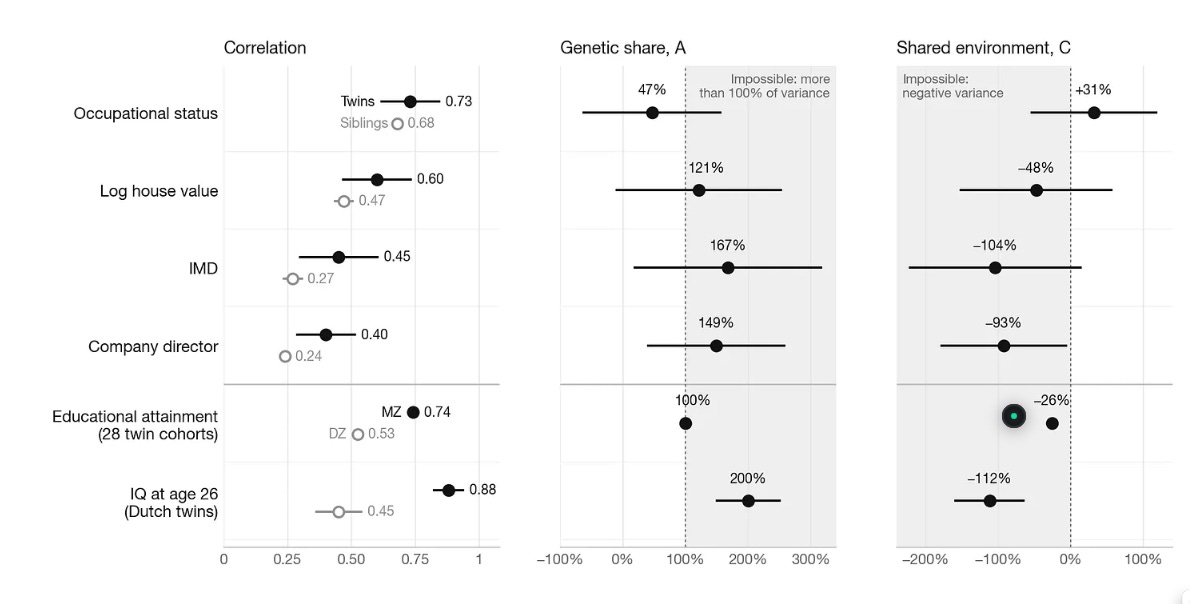
For three of the four traits, Clark’s parameter produces an estimate of heritability that is greater than 100% and a negative estimate of the shared environment variance. These are observed correlations, which Clark argues are swamped by measurement error, so the out of bounds heritability estimates should actually be even more out of bounds. To be fair, the twin estimates from Clark’s data come with a lot of uncertainty, but we can also apply the same calculation to high quality modern twin studies (cited by Clark in other parts of the text). For educational attainment (Silventoinen et al.) as a representative status trait, the same latent assortment would be consistent with a heritability of 100% and a highly significant (and impossible) shared environment variance of -26%. For IQ (Boomsma et al.), the resulting heritability would be 200% and the shared environment -112%. These estimates are clearly absurd, both in Clark’s data and in modern data, and Clark rejects attempts to reconcile them.

Epicycles

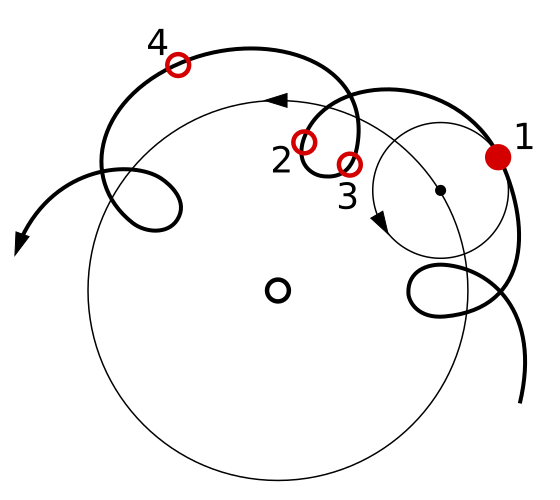
I’m focusing on this example because I think it’s easy to understand and typifies the discussions between Clark and his critics. Clark makes a bold claim (long-run patterns of intergenerational transmission are explained by a purely genetic model). Flaws are identified in the claim (the spousal genetic correlation needed for the model would produce impossible estimates in twins). Clark carries out a new analysis with new data (evaluating MZ/DZ correlations for non-additivity), adding a new epicycle to the model. This analysis is itself flawed in a new way (the MZ/DZ comparisons did not account for assortative mating), revealing a new problem. And on it goes.

Deferent and epicycle - Wikipedia
The epicycles of the planets from the perspective of Earth (source: wikipedia)

The symposium features several such epicycles. John Benning re-analyzes the data and finds that Clark is inappropriately re-using samples to calculate his correlations (“pseudo-replication”) and that proper bootstrapping produces extremely uncertain estimates especially for distant relatives. Clark responds that he does not make use of the estimated sampling error, so it doesn’t matter. In reality, his regressions are weighted by exactly that sampling error and he makes multiple claims about the precision and statistical significance of his estimators which rely on that sampling error; not to mention repeated qualitative arguments about non-zero status persistence in distant relatives. Jan Stuhler points to the extensive literature on within-family birth order effects, which has demonstrated clear environmental influences on social status. Clark argues back that within-family estimates (not exactly a fringe statistical procedure) should not be trusted in general, then justifies this with a simulation in which spurious birth-order effects appear only in between-family regressions — precisely the issue that within-family analyses address. And on it goes.

Vibe heritability

What about Clark’s advocates? Charles Murray (a political scientist) and Noah Carl (a disgraced sociologist) contributed to the symposium, lavishing praise on the book while studiously avoiding any of the statistical issues. Both argue that Clark’s findings align with findings from twin studies, when just a little bit of algebra shows that they are fundamentally incompatible. Alex Tabarrok at the Marginal Revolution blog echoes this theme: Clark has “pushed the debate far into new territory”. Ironically, Tabarrok highlights an observation from distant relatives that is precisely one of the low certainty, pseudo-replication estimates critiqued by Benning. The broad takeaway is: we know in our hearts that Clark is on to something, so don’t think too hard about the numbers, just enjoy the vibe.

This is a common reaction to Clark’s work — that he’s identifying something new and important even if his numbers don’t really add up — but extraordinary claims require a high evidentiary standard, not a gut feeling. Imagine your friend invented a new bodyweight scale after spending years collecting data to calibrate it, and swears that everyone has been weighing themselves incorrectly. You put your toddler on the scale, the little machine does its calculation, and it tells you that your toddler weighs 500 pounds. “See!” your friend says eagerly, “your little one is critically obese, without my invention you’d never have known”. Puzzled, you pick up your toddler and step on the scale together; the scale runs its calculation again, and now it reads 300 pounds for the two of you. “It’s just broken,” you conclude, “I obviously do not weigh negative 200 pounds”. Your friend becomes defensive: “Look, let’s not get into the weeds. 300 pounds, 500 pounds, that’s not the point. My invention has revealed that your toddler is much heavier than you thought. I am pushing the debate into new territory!”.

But your friend hasn’t actually revealed anything; maybe the first measurement was wrong, maybe the second, or maybe (probably) both — the invention simply doesn’t work. Likewise, we know that essentially all traits are driven by some combination of genes, environment, and the interaction of the two. Clark fits a purely genetic model to his data and it doesn’t work. We’ve seen this before. All we can conclude is that pure genetic transmission doesn’t fit the data, a finding that should already have been obvious.


Appendix: Heritability from twin correlations under assortative mating

Following Clark’s terminology, given a genetic correlation between mates of m, the expected genetic sharing between their offspring siblings is:

Then given an additive genetic variance (aka heritability) of A, and a shared environmental variance of C, the resulting phenotypic correlation for different twin classes is:

In Clark’s data, twin zygosity was unknown, but given a pool of twins of which p proportion are MZs, their expected phenotypic correlation is:

Finally, we can relate the two quantities to heritability (A) as:

and solve for heritability as:

as a sanity check, we can see that under random mating m=0 and all twins being monozygotic (p=1), the above reduces to the standard ACE twin model estimate where A=2(rmz-rdz). In the main calculations I have assumed, as Clark does, that half the twins are MZs (p=1/2) and I have used Clark’s pooled estimate of m=0.57.

<https://theinfinitesimal.substack.com/p/vibe-heritability> <https://theinfinitesimal.substack.com>

The Infinitesimal
Vibe heritability
The economic historian Gregory Clark has written a book on status persistence, which was the focus of a recent online symposium. Clark has assembled a massive dataset of multigenerational status measurements in England. The project has a particularly British whimsy to it, with much of the data coming from the Guil…
Read more

Brad DeLong here: I don’t think I really have much value added here.

Share DeLong's Grasping Reality Weblog

I would note that the post he is quoting from is the latest version of a lecture part that I have been occasionally giving in my courses since long before Greg began working on intergenerational status inequality. At the moment it (sometimes) shows up in the “Inequality & Domination” module of my Econ 135: Global Economic History: <https://braddelong.substack.com/p/big-trouble-in-little-human-genetic>.

And what I wrote is, as best as I can tell, a statement of fact. It is how I read the current state of the literature. And, more important, it is how Sasha Gusev and others much more qualified to judge than I am read it:

Leave a comment

Greg: I invited you to come talk about your stuff here at Berkeley. If that is hostility and contempt, that is a very strange way indeed for me to show it.

It is true that I—and the overwhelming majority at the seminar, I believe—did not believe that you had established a case. It seemed to me that your argument required that very strong assortative mating take place not on the basis of wealth, or occupation, or observed status, but rather on the raw genotype: that, as I put it, men and women had to smell the genetic “fitness” of partners and then act sub- and un-consciously on the basis of that smell. Thus it did not seem to hang together.

I, at least, was left with the belief that we knew what we had known from Bowles and Gintis:

Samuel Bowles & Herbert Gintis (2002): The Inheritance of Inequality <https://pubs.aeaweb.org/doi/pdfplus/10.1257/089533002760278686>: ‘the intergenerational correlations for economic status appear to be substantial…. Most researchers now agree… [that] brothers’ incomes are much more similar than those of randomly chosen males of the same race and similar age differences; the incomes of identical twins are much more similar than fraternal twins or non-twin brothers; the children of well-off parents obtain more and higher quality schooling; and wealth inheritance makes an important contribution…. It seems safe to conclude that the intergenerational transmission of economic status is accounted for by a heterogeneous collection of mechanisms, including the genetic and cultural transmission of cognitive skills and noncognitive personality traits in demand by employers, the inheritance of wealth and income-enhancing group memberships, such as race, and the superior education and health status enjoyed by the children of higher status families.

However, the transmission of economic success across generations remains… black box…. Combined inheritance processes operating through superior cognitive performance and educational attainments of those with well-off parents… explain at most three-fifths of the intergenerational transmission of economic status. Moreover, while genetic transmission of earnings-enhancing traits appears to play a role, the genetic transmission of IQ appears to be relatively unimportant. It might be thought that the black box is an artifact of poor measurement of the intervening variables relative to the measurement of the income or earnings of parents and offspring. But this does not seem to be the case….

Refer a friend

Let me repeat: Sasha Gusev, who is much more expert on this than I am, and who I have found a very reliable guide to this business. He concludes that although you have revised pieces of the argument since I saw it, you have simply added on:

Epicycles…. And on it goes.

Deferent and epicycle - Wikipedia
The epicycles of the planets from the perspective of Earth (source: wikipedia)

The [EJR] symposium features several such epicycles. John Benning… finds that Clark is inappropriately re-using samples…. Clark responds that he does not make use of the estimated sampling error, so it doesn’t matter. In reality, his regressions are weighted by exactly that sampling error and he makes multiple claims… which rely on that sampling error…. Stuhler points to the extensive literature on within-family birth order effects… clear environmental influences on social status. Clark argues back that within-family estimates… should not be trusted in general… justifie[d by]… a simulation in which spurious birth-order effects appear only in between-family regressions…. And on it goes…

Get 75% off a group subscription

Sasha’s conclusion? No purely genetic model of the intergenerational transmission of status inequality can hold together. The key number in that model is how genetically similar spouses are. Plug the number you need for that for society as a whole into the data for twins, and you get simply impossible results.

And Sasha seems tired:

Clark makes a bold claim…. Flaws are identified in the claim…. Clark carries out a new analysis with new data…. This analysis is itself flawed in a new way… revealing a new problem. And on it goes…. We know that essentially all traits are driven by some combination of genes, environment, and the interaction of the two. Clark fits a purely genetic model to his data and it doesn’t work. We’ve seen this before. All we can conclude is that pure genetic transmission doesn’t fit the data, a finding that should already have been obvious…

As Sasha writes elsewhere:

Sasha Gusev (2025): We Still Do Not Understand Family Resemblance <https://theinfinitesimal.substack.com/p/we-still-do-not-understand-family>: ‘Behavioral/status traits are complicated and we still do not have good unified models of their family resemblance. The high correlation for MZ twins points to interactions. The high correlation of adopted relatives points to direct and dynastic environmental influences. And the fact that a Fisherian model with biological relatives fit fairly well but became significantly misspecified with the inclusion of in-laws points to an environmental influence that, at least in part, mimics genetic relatedness. This latter point (which I’ve alluded to several times) is important, as it suggests that when we see similarities in families and ascribe them to genes we are at least to some extent misinterpreting the causal processes at play…

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-sasha-gusev-vibe-heritability-the-ejw-symposium-on-gregory-clark-on-genetics-social-mobility
##neofascism
##enlarging-the-bounds-of-human-empire
##crosspost
#sasha-gusev-vibe-heritability-the-ejw-symposium-on-gregory-clark-on-genetics-social-mobility
#sasha-gusev
#vibe-heritability-the-ejw-symposium-on-gregory-clark-on-genetics-social-mobility
#vibe-heritability
#social-mobility
#behavioral-genetics
#heritability
#nature-versus-nurture
#epicycles

CROSSPOST: ROBERT RUBIN: In Six Decades of Public Life, I Never Thought I Would Write This Piece

Robert Rubin has spent more than sixty years in and around economic policy, and he never before thought he would have to write this. His message to Wall Street is that a Trump attempt to interfere with or usurp the midterms is a real risk that markets are ignoring. A Turkish executive told the Financial Times, “We can live with high inflation, but our biggest disincentive to invest is the lack of the rule of law.” Rubin warns that the United States doesn’t have to become Turkey or China to learn what that means:

Robert Rubin says: markets today are not pricing in the risks of a stolen midterm—yet Trump has said over and over again that if he loses it will because the Democrats cheated, and not because he, Trump, is historically unpopular. Business leaders think election subversion is a remote risk. Rubin thinks they’re wrong:

Share

Far too many plutocrat billionaires and gentry multimillionaires think Trump and his coterie of fellow kleptocrats are, when the chips are down, their friends. They are wrong to think so:

Give a gift subscription


CROSSPOST: ROBERT RUBIN: In Six Decades of Public Life, I Never Thought I Would Write This Piece

<https://www.nytimes.com/2026/10/21/opinion/trump-midterms-election-threats-ice-economy.html> <https://www.nytimes.com>

Rubin, Robert E

Oct 21, 2026.

The economy has been voters’ top issue in four of the six midterm elections this century — and 2026 appears all but certain to make it five of seven. Beyond the cost of living, the war in Iran and tariffs, America faces a series of daunting longer-term economic challenges, from mounting federal debt to the effects of artificial intelligence.

Yet many Americans continue to underestimate one particular potential threat to our economic future: President Trump’s clearly expressed desire to interfere with and even usurp the midterm elections. Nov. 3 could be a defining test for the rule of law in this country, and both our democracy and our prosperity are on the line.

There is a chance — some would argue a likelihood — that the midterms will proceed smoothly and honestly, with the winners seated in a straightforward manner. There is also the possibility that the election will be, like so much else over the past two years, chaotic at best and lawless at worst. From amplifying false claims of fraud and slashing defenses against foreign meddling in our elections to attempting to bully states into using an error-prone database to purge voter registrations, the Trump administration has already thrown up obstacles to fair and free midterm elections. There are widespread fears Mr. Trump and his allies could go further, including by sending armed federal agents to polling locations, seizing ballot boxes and exploiting a procedural loophole involving the clerk of the House that could enable them to refuse to seat duly elected Democratic members when the new Congress convenes on Jan. 3.

If the Trump administration launches an effort to manipulate the outcome of the midterms, the economic impact could be felt immediately, and it could last long after Mr. Trump’s presidency ends.

With the exception of the booming A.I. sector, corporate investment is already weak. The National Federation of Independent Business’s measurement of small-business uncertainty is 32 percent above its historical average. This seems like a bad time to inject substantially more instability into the mix.

The short-term risks from election interference look even more concerning when we consider the possibility that a fight over the outcomes will not necessarily remain contained to the courtroom. Mr. Trump has explicitly refused to rule out invoking the Insurrection Act in regard to the 2026 elections. Starting in late 2025, a surge of immigration enforcement agents into Minneapolis cost the city, its businesses and its residents an estimated $700 million. Sustained post-election chaos coupled with aggressive federal interference could create similar disruptions on a nationwide scale.

Any effort to undermine the election will eventually resolve itself, whether through political compromise, contentious rulings from courts, the use of force or all three. But the economic impact will outlast any immediate political crisis. The rule of law, undergirded by a tradition of free elections and the peaceful transfer of power, supports business decisions and attracts foreign companies to invest. It underlies the position of the dollar as the world’s reserve currency. It bolsters investors’ confidence in the full faith and credit of the United States and lowers interest rates on our debt. The integrity of our elections, in other words, has been one of the keys to American prosperity.

The United States has not yet seen its economy suffer from a lack of confidence in its legal system. Other countries have. “We can live with high inflation,” one Turkish executive told The Financial Times last year, “but our biggest disincentive to invest is the lack of the rule of law.” A 2024 State Department report similarly identified rule-of-law issues — including lack of respect for property rights, repression of criticism and arbitrary investigations and arrests — as major impediments to the business climate in China.

The United States does not have to become Turkey or China to feel the economic impacts of a diminished rule of law. The economist John Maynard Keynes famously wrote of the “animal spirits” that encourage people to engage in market activity. Americans’ animal spirits have long been bolstered by the knowledge that their country is the best place on earth to start or invest in a business. A contested or overturned election could call that into question.

When I talk to leaders in business and politics, even many of those who acknowledge the election threat seem to consider such a possibility remote. They do not tend to take Mr. Trump’s attacks on voting seriously. That’s another way of saying that the markets are not pricing in what I consider a meaningful risk.

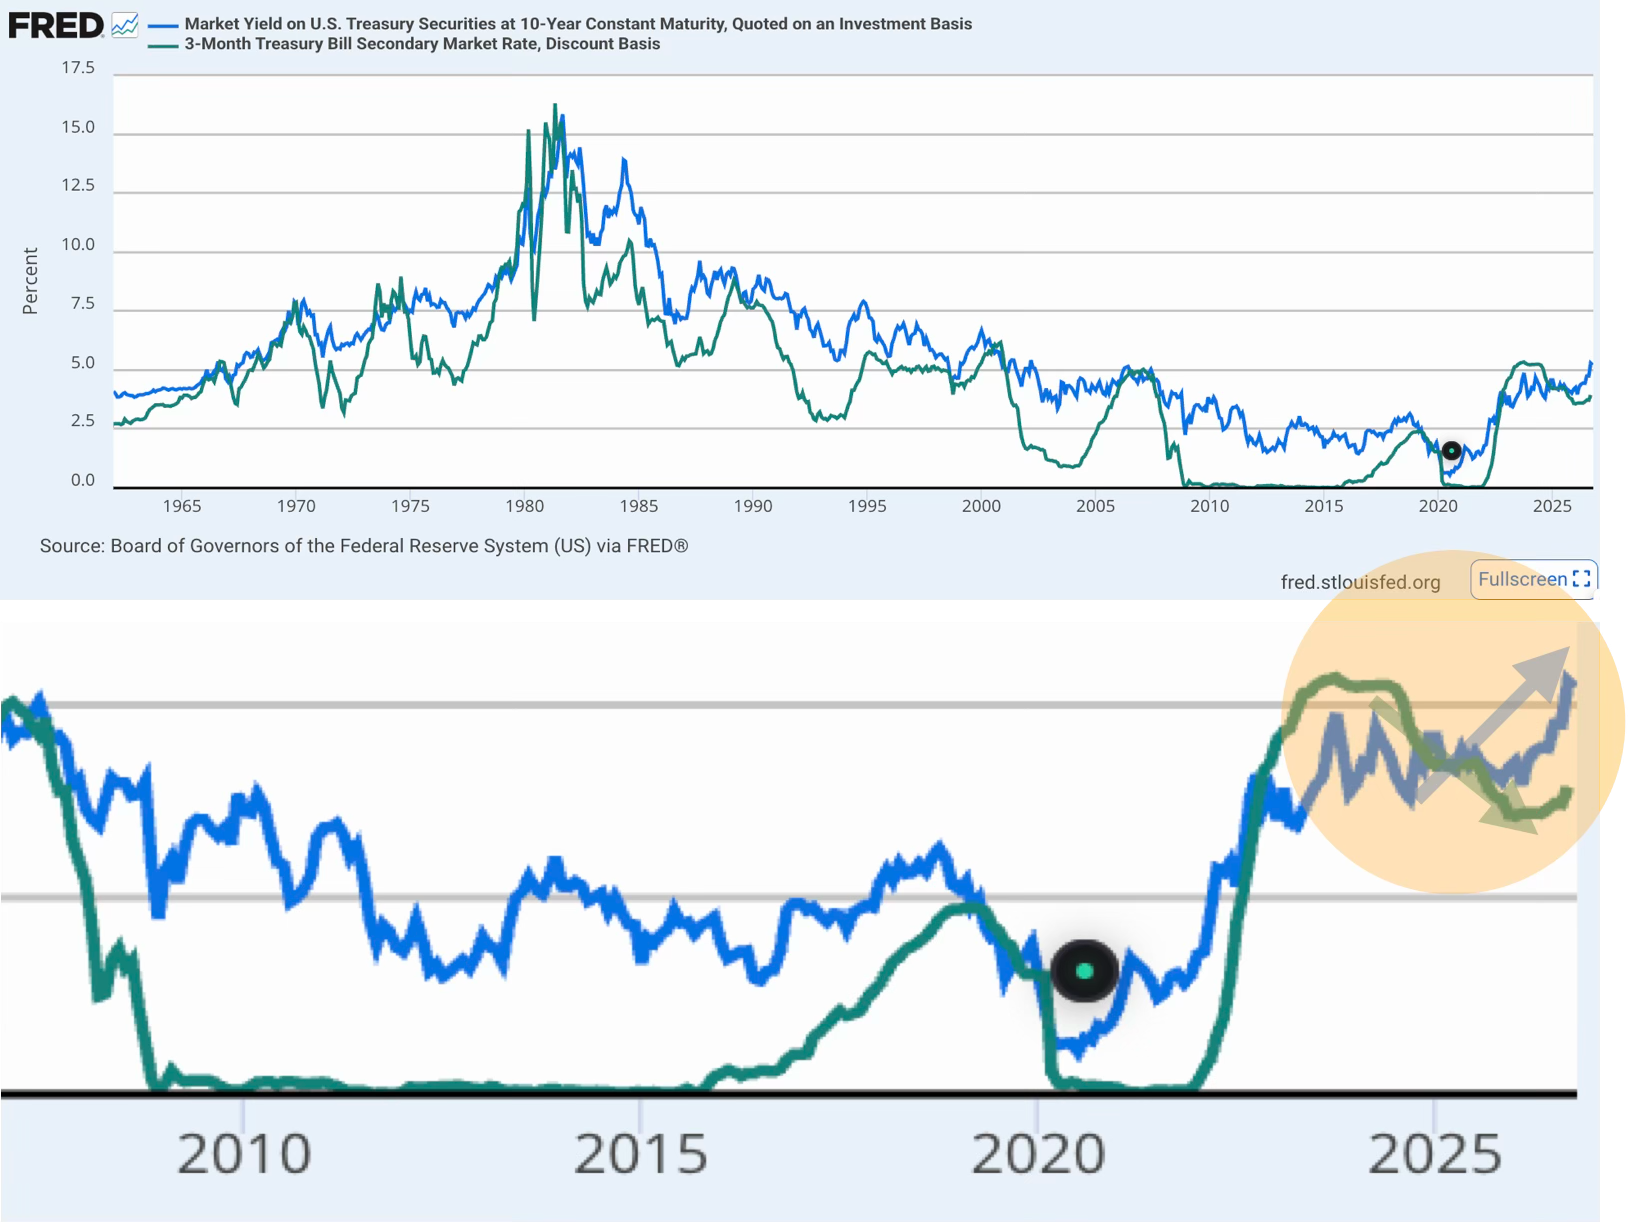
If Mr. Trump accomplishes in 2026 what he was unable to with respect to the 2020 election, or even if he causes widespread chaos by coming closer to his objective, it could create serious disruptions in the bond and equity markets. The yield on 10-year Treasuries recently reached 5.36 percent — higher than it was in the aftermath of the 2008 financial crisis — in part because of concerns about the country’s policy trajectory. Election chaos could increase investors’ worry about the ability of our political system to deal with our fiscal problems, driving yields even higher. This would result in higher debt service costs for the government and higher mortgage rates and credit card bills for consumers, exacerbating our already considerable challenges.

I’ve lived my entire life as a citizen of a constitutional republic that provides rights and protections, and I’d like to continue doing so. I imagine most Americans, regardless of their political leanings, feel the same way.

Over the next few weeks, leaders in business and in all sectors of our society should work with state and local elected officials to help protect the political process that lies at the heart of our constitutional system. They can do this by making clear, nonpartisan declarations of support for election integrity, by supporting nonpartisan organizations that protect our elections and by using behind-the-scenes influence to discourage those who might be considering any steps to disrupt or overturn the midterms.

In more than six decades spent in and around economic policymaking, I never imagined having to write a piece such as this. If we act now, we can still protect our government, our people and our economy — and we can preserve the benefits that accrue to all of us, no matter whom we vote for, when American elections are fair and free.


Mr. Rubin is a senior counselor to Centerview Partners and was the U.S. Treasury secretary from 1995 to 1999.

<https://www.nytimes.com/2026/10/21/opinion/trump-midterms-election-threats-ice-economy.html> <https://www.nytimes.com>


Brad DeLong here: A contested or overturned election would hit America’s “animal spirits” and investment, productivity growth, Treasury yields, and the dollar permanently. Its consequences would echo long after the political crisis ends. Even those who care only about their money, and not about, you know, democracy should be working like dogs right now to draw the fangs of Trump and the Trumpists. And they are not. Steve Schwarzman, for example, is right now funding and running attack ads against Democrats for… investing in and with Steve Schwarzman.

As Bob says: even if you are confident enough in your personal links to TrumpWorld that you do not fear being sent to some Guantanamo GULAG or stripped of your assets on some transparently false pretext, free elections and the peaceful transfer of power are very valuable economic infrastructure. As Bob says: Trump and the Trumpists have already amplified false fraud claims, cut defenses against foreign meddling, pushed states toward an error-prone voter-purge database, and made a bright line of refusing to rule out invoking the Insurrection Act.

I say: Trump has already tried to overthrow the government of the United States once. Even if you are confident that a second attempt will also be defeated, it will accelerate the decoupling of global investment and trade from the United States. The long-run economic damage will be large.

As Bob says: investment outside of AI is already weak, and so is productivity growth. I say: The sustainability of the U.S. fiscal position requires the arithmetic inequality that Treasury yields be below the nominal growth rate of GDP. The cutoff of immigration and weak investment outside AI means that that arithmetic inequality would fall with another confidence shock to the US. It then would rely on AI paying off BigTime in significantly faster measured GDP growth. And there are few signs right now that AI will pay off BigTime in measured GDP growth. Protect current platform-monopoly profits, yes. Change how we live and think profoundly for good or ill, yes. Build a Digital God, no—although many involved in it think that that is what they are doing. Pay off BigTime in boosting measured GDP growth? As I read it, very unlikely.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-robert-rubin-in-six-decades-of-public-life-i-never-thought-i-would-write-this-piece
##neofascism
##chaos-monkey-trump
##crosspost
#robert-rubin-in-six-decades-of-public-life-i-never-thought-i-would-write-this-piece
#robert-rubin
#in-six-decades-of-public-life-i-never-thought-i-would-write-this-piece
#rule-of-law
#midterm-elections
#election-integrity
#election-subversion
#democracy
#political-economy
#sovereign-risk
#investment-uncertainty
#peaceful-transfer-power
#institutions-matter
#donald-trump

CROSSPOST: ALICE EVANS: Stop Pink-Washing Patriarchy

But it is not that unfair. The deep history is stark. In the biographical record, women appear only about a tenth as often as men for five thousand years, with ancient Egypt the exception, and the ratio stays flat until self-made women begin to appear in Protestant Europe in the 1600s. The genome adds a further shock: in the years around -3000, male lineages collapsed to about one-twentieth the relative number of female lineages, with male passing-on-of-lineages was concentrated in a semi-hereditary caste of fathers. Most anthropologists blame the plough, horse warriors, or the state; Alice Evans blames the veil. But it is not something that matrilocality or other cross-culture sociological differences put much of a dent in:

This is part of my surfacing the calling-out-of-idiocy, by crossposting whenever smart people do so.

Share

So here, in this post and its predecessor, we have a diptych made up of this crosspost of:

And my earlier crosspost of:

Leave a comment

Dan called out the right. Alice now calls out the “left”. Although the people she critiques are not people of the left in any sense that I recognize as valid: reinforcing and justifying patriarchal institutions by pinkwashing them just because they have roots other than in the Dover-Circle cultures is not established-hierarchy scrutinization and breaking, and I see only intellectual currents that focus on scrutinizing and breaking established hierarchies as having any valid rights to a left card.

Alice speedruns through 1970s–80s feminist history, postcolonial studies, with a sidelook at the plough hypothesis of the rise of patriarchy (Alesina, Giuliano & Nunn). She argues that we now have more than a generation of feminist and postcolonial scholarship, and now the chatbots trained on it, systematically understated patriarchy by:

  • celebrating exceptional or “agentic” women;

  • hiding how far some regions have moved toward gender equality in the 20th century

  • hiding how much oppression persists elsewhere.

Share DeLong’s Grasping Reality Weblog

Spotlighting queens, litigants, market women and witches-as-rebels treats the exception as if it were the rule, and so mismeasures the degree of patriarchy.

How did we get her? In her telling, 1980s feminists wanted to show that “another world is possible,” so they searched the record for egalitarian societies, matriarchies and female agency. Meanwhile, moral-prestige incentives pushed Western scholars to “punch up” at home and avoid judging other cultures, for fear of being called neocolonial. And so we had the development of standard metrics (female labor participation, property, ritual roles) that often count drudgery rather than power, and that work very hard to avert their eyes form violence, coercion, forced marriage, and the destruction of women’s spaces where they could coalesce and form coalitions.

Alice:


CROSSPOST: ALICE EVANS: Stop Pink-Washing Patriarchy

<https://www.ggd.world/p/stop-pink-washing-patriarchy> <https://www.ggd.world>

The Great Gender Divergence
Stop Pink-Washing Patriarchy!
Why do so many academic histories, popular books and museum exhibits celebrate exceptional ‘kick ass’ women, while minimizing patriarchy? It may feel empowering, exciting and rebellious, but such narratives are often grossly misleading. They blind us to colossal progress towards gender equality in some world regions, alongside persistent patriarchy else…
Read more

Alice Evans

Oct 18, 2026

Why do so many academic histories, popular books and museum exhibits celebrate exceptional ‘kick ass’ women, while minimizing patriarchy? It may feel empowering, exciting and rebellious, but such narratives are often grossly misleading. They blind us to colossal progress towards gender equality in some world regions, alongside persistent patriarchy elsewhere. Today, let’s examine why gender studies went so wrong, and how we might study patriarchy with open-minded empiricism.

An Intellectual History of Pink-Washing Patriarchy

Feminist scholars of the 1970s and ‘80s often wanted to show that patriarchy was not inevitable, but rather another world was possible. They scoured the ethnographic records for small-scale egalitarian societies, celebrated ancient ‘matriarchies’, and pointed to ancient goddess-worship.

Looking back at the European past, gender historians sought to highlight women’s historic agency, importance, wealth, and labour. This scholarship was often motivated by a feminist desire to counter past erasure and show that women mattered. But as Judith Bennett (2006) brilliantly argued, while it may feel empowering to document female agency and rebellion, this minimizes historic patriarchy.

Thankfully, patriarchy has largely been emasculated in most advanced countries. Challenges persist (such as women predominating in firms with greater flexibility and lower productivity), but pale in comparison to the moral gravity of femicides and arranged marriages. Yet the same violence, abuse and male-dominance that would provoke virulent critique in the West are sometimes ignored, or even defended elsewhere. Captured concubines in Persia are celebrated as strategic, modern Cairene women who embrace obedience and seclusion are heralded as ‘agentic’, while laws banning female genital mutilation are condemned as ‘stigmatizing’.

What on earth went wrong? Western feminists gain moral prestige by ‘punching up’ and criticising male hierarchies at home, but are often reluctant to scrutinize gender norms in other societies for fear of being branded neocolonial or racist. Elites in the Global South may downplay patriarchal oppression in their own countries, wary of being cast as ‘backward’. Globally-comparative analysis of gender is thus taboo.

Yet if we actually want to advance gender equality, we need to get real. We need to stop pink-washing patriarchy, and embrace an open, empirical enquiry.

Medieval Europe

The British Library’s exhibition on Medieval Women showcased a tremendous collection of manuscripts and artefacts, demonstrating women’s prominence, but almost to the point of sugarcoating 15th century misogyny.

Yes, Christine de Pizan wrote the Book of the City of Ladies, asserting women’s equal competence. But she faced an uphill struggle. Before mass printing, each manuscript had to be transcribed by hand, and every major institution was dominated by men.

Head into any Western bookshop and you’ll find celebrations of “bad ass” women from the past, but these are slim pickings. In a database of almost 59,000 European university teachers and academy members active before 1800, there were just 108 women.

Misogyny was rife. As Protestant and Catholic churches sparred for souls in 16th century West-Central Europe, they aggressively demonstrated their power to vanquish the devil (Leeson and Russ 2018). Thousands of ‘witches’ (mostly women) were accused, tried and murdered. Paintings cast women as potentially deceitful and dangerous, circulating via printing. Frans Francken the Younger’s paintings show women in ordinary, respectable clothing undressing to join demonic rituals - hinting that satan’s agents live amongst us.

Execution of five witches in Lausanne. The Swiss Protestant clergyman Johann Jakob Wick (1522–1588) wrote a chronicle with coloured drawings of contemporary events. The above shows witches being burnt, during 1560-88.

Small-Scale Societies

Analyses of small-scale societies must also be viewed with caution. The Standard Cross Cultural Sample (SCCS) gives the Ashanti its highest possible score for ‘female power’, recognising Queen Mothers, but this same society was rife with pawning - as girls were given off as collateral. Moreover, focusing on a single, royal actor like the Queen Mother ignores whether women could organize powerful coalitions to defend their collective interests.

Violence is another major omission. Accounts centred on female prominence, labor, property ownership, matrilocality, and permissive sexual norms are misleading if they do not also recognise violence and coercion. That includes risks of rape, capture, enslavement and head-hunting. If men can get what they want through brute force, or arranged marriage, they need not demonstrate care, companionship or devotion. In my analysis of the SCCS, wife-beating was reported as common in 80% of coded societies.

The Siraya of Taiwan were matrilocal and women did the lion’s share of agriculture. But men still engaged in out-bounding raiding and exclusively dominated governing councils. Analyses that focus on gender divisions of labour may well be tabulating drudgery, while omitting child marriage, impoverishment and routine coercion.

Get over the Hoe!

If you attend any Economics course on gender, you’ll probably learn ploughs favoured male brawn and naturalised men’s participation in the public sphere, whereas hoes maintained women’s centrality.

This is possibly one of the most misleading ideas in economics (save all the other ones).

Women’s participation in agriculture doesn’t tell us whether women controlled any of the surplus, let alone whether they could build powerful coalitions. Hoe agriculture produces larger surpluses compared with slash and burn, and anything which generated a storable surplus made a village more vulnerable to external predation. This generated stronger incentives for raiding, defence and warfare. Male military coalitions grabbed power and enshrined themselves as leaders.

The real puzzle is why women worked so hard, but struggled to capture the rewards. What prevented women from organizing powerful networks, capable of challenging patriarchal authority and impunity?

Aztec Patriarchy

Feminist histories of the Aztecs often highlight ‘gender complementarity’, noting that women ground maize and sold at markets.

But why are we elevating a hard slog? The overwhelming majority of Aztec mothers woke early, spent five hours a day grinding maize for tortillas, scrubbing their children’s clothes. Women’s work is often thankless. As a young woman told me in an Oaxacan market, “men think of us as servants”.

Dodds Pennock also seems to pink-wash human sacrifices. She notes that victims of human sacrifices were sometimes ixiptla (impersonators) of the gods, embodying the deity the ceremony was supposed to honor. Since female victims often embodied deities associated with earth, fertility, water, maize, salt, childbirth, disease and natural forces: “Women were bound up with the earth – and this connection gave both their lives and their deaths significance”.

Pardon?

Islamic Empires

Within Islamic history, postcolonial scholars have often emphasised women’s property ownership, donations to mosques, litigation in courts, and strategic ploys in the harems (Peirce 1993; Tucker 1985).

But this minimizes wider patriarchal oppression: teenage girls were betrothed to men they had not met, and thereafter kept cloistered, while men dominated every single institution. Late 19th century Egyptian reformist, Qasim Amin, was refreshingly honest, highlighting that women applied their seals to accounts and contracts, without understanding their contents, leaving them vulnerable to exploitation by husbands, relatives or trustees.

Today, female employment remains especially low across Central Asia, South Asia, the Middle East and North Africa (CASAMENA), and these same patterns persist when communities move abroad to Europe. Yet too often scholars attribute this to the challenges of balancing work and motherhood, thereby extending analyses derived from the West. But clearly there is something culturally specific about CASAMENA, since even when compared to economically-similar countries, female employment remains ultra low.

Patriarchy, therefore, gets a free pass.

Hauling water isn’t Emancipating!

Sub-Saharan Africa scores well on standard metrics of gender equality, on account of high female labor force participation, but this is grossly misleading, because work is not inherently liberating.

In low-income Africa, women may move independently, but their lives are still marked by relentless drudgery and insecurity. Too often, poor women wake before dawn and labour long after dusk, only to be stuck in the same place.

LLMs also sugar-coat the patriarchy!

Since LLMs are trained on this same data, they reproduce the same selectivity. When I uploaded Upinder Singh’s (2008) tremendous book on India, which states that ‘the number of hymns attributed to women sages in the Rig Veda is small”, Claude then told me: “The Rig Veda includes hymns composed by women - a testament to their participation in the intellectual and spiritual life of the time”. Dropping the qualification, Claude refashioned male dominance into female prominence!

Such narratives blind us to the fact that the entire world was run by fraternal coalitions, often extremely violent, and that over the 20th century we have made phenomenal progress!

When I asked ChatGPT, “Why do so few women in the Middle East and North Africa work for pay, when so many are university educated?”, it summarized a range of economics papers, emphasizing domestic labor and job scarcity. But this hypothesis seems unconvincing, given that MENA’s female employment is so much lower than other countries with similar economic development. ChatGPT seems reluctant to recognize region-specific cultural constraints, namely seclusion.

Even when LLMs do note patriarchy, they tend to excessively ‘hedge’ - such as by saying that in the Ottoman Empire, royal women might exercise influence. I suspect their training data includes academic papers that stress ‘exceptional women’.

Studying the Great Gender Divergence!

Over the 20th century, the entire world made colossal progress towards gender equality, more rapidly in some regions than others. Pink-washing past and present patriarchy may feel nice, but is ultimately misleading because it blinds us to both progress and persistent oppression.

To understand how our world came to be, we need to study how male fraternities consolidated power, and why this persisted for so long. That means studying long historical processes, tracing the interplay of political, economic and cultural shifts, and comparing societies to understand what sustained (or weakened) patriarchal authority.

Digitization can help us track the longue durée. For example, we still don’t really know why ideals of female seclusion spread across Mesopotamia. I am hopeful that digitisation of hundreds of thousands of cuneiform tablets might help us track the adoption of veiling.

Social network analysis is now more possible at scale. I’m curious to learn how caste changes in the diaspora. What role do parents play in Indian American marriages? Can LinkedIn or Meta data help us understand jaati networks?

Visual media is the frontier! We could analyse, compare and track shifting representations of gender in paintings, photos film and television by harnessing vision-language models (as I suggested here). Which forms of masculinity become admirable, how does this vary over time and between countries?

Big data can be tremendously valuable, though it’s crucial to ask the right questions, grounded in social realities. For example, Baumard and colleagues generated an ‘Ancient Literary Fictions Database’ (a corpus of 2995 literary works on Wikipedia, spanning Ancient Egypt and the Norse World), then analysed depictions of falling in love. But their finding that the 16th century saw a global rise in love literature is a little misleading, since there’s a vast difference between writing about one’s passions and societies actually upholding marriages based on love.

Gender benchmarks could be developed to assess Large Language Models, evaluating whether they provide accurate descriptions of each society, alongside empirically-supported hypotheses. Given growing use of LLMS, correcting their biases seems extremely important.

Celebrate truth-seeking! Patriarchy thrives when it is widely regarded as legitimate, and actual oppression goes unquestioned because people are too scared to speak out, fearing aggressive backlash. To tackle actually-existing patriarchy, we need to support and encourage students to turn over every stone, scrutinize every hypothesis.

We live in an era of rapid technological advances, and yet women’s lives, safety and status still vary enormously across world regions. To tackle actually-existing patriarchy, we need to recognize this heterogeneity, and develop tools which help us understand its persistence. Going forwards, I suggest that qualitative insights into different societies can help ground our inquiries, so we can build innovative datasets that capture what really matters. Further, we could scrutinize LLMs to ensure that they do not pink-wash the patriarchy.

Generated image 1
My hopes for digitising cuneiform! Made with ChatGPT

Thanks for reading The Great Gender Divergence! Subscribe for free to receive new posts and support my work.

Related Essays

Additional: Paintings of Witchcraft

<https://www.ggd.world/p/stop-pink-washing-patriarchy> <https://www.ggd.world>

The Great Gender Divergence
Stop Pink-Washing Patriarchy!
Why do so many academic histories, popular books and museum exhibits celebrate exceptional ‘kick ass’ women, while minimizing patriarchy? It may feel empowering, exciting and rebellious, but such narratives are often grossly misleading. They blind us to colossal progress towards gender equality in some world regions, alongside persistent patriarchy else…
Read more

Brad DeLong here: Where do I agree and disagree with Alice here?

Refer a friend

Well, I mostly agree. But I do wish she offered more in the way of nuance.

Read more

CROSSPOST: DAN DREZNER: The Op-Eds About Higher Education Need to Stop Until We Figure Out What the Hell Is Going On With the Op-Ed Contributors

A plea from Dan Drezner for the Wall Street Journal to stop publishing “steaming piles of horseshit untul they figure out what is actually going on”. But, Dan, as my father told me back in the 1960s, that is what they do: they chose as their lane that they would be the comics page for people who think Herbert Hoover was a great president and Franklin Delano Roosevelt was a communist. They have ridden all their horses down that lane to great profit for near unto a century…

He finds former UCSC German Professor John Ellis with “just bald-faced lies”.

Share

Drezner calls Ellis’s claims that Marxist indoctrination on campus explains why socialist candidates are now winning elections “the single-dumbest op-ed about higher education” the Journal has ever published.

That’s a high bar to clear!

Drezner reduces Ellis’s argument to: the faculty moved left → “?????” → socialists win. And asks for more evidence. Which is not offered:

Give a gift subscription


CROSSPOST: DAN DREZNER: The Op-Eds About Higher Education Need to Stop Until We Figure Out What the Hell Is Going On With the Op-Ed Contributors

<https://danieldrezner.substack.com/p/the-op-eds-about-higher-education> <https://danieldrezner.substack.com>

Drezner’s World
The Op-Eds About Higher Education Need to Stop Until We Figure Out What the Hell Is Going On With the Op-Ed Contributors
Last week was a long one on the road for me — it started in Toronto and ended in New York. There were definitely some highlights - take a gander of some of these views I caught in both cities…
Read more

A modest proposal....

Daniel W. Drezner

4 hours ago

Last week was a long one on the road for me — it started in Toronto and ended in New York. There were definitely some highlights - take a gander of some of these views I caught in both cities:

For the New York leg I accompanied a variety of faculty, students, and staff of the Fletcher School so our students could explore various career opportunities in the private sector, nonprofit sector, international organizations, and maybe the occasional U.S. government position if they were still hiring.

My point is that it was a long week and I was looking forward to coming home and blobbing out. My brain needed a break.

Instead I read the single-dumbest op-ed about higher education the Wall Street Journal has ever published — which is saying something. And my brain refused to ignore the pseudo-intellectual claptrap and demanded the hard-working staff here at Drezner’s World craft a response.

Drezner’s World is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.

The op-ed, by UC-Santa Cruz emeritus professor John Ellis, is entitled, “Radical Professors Have Poisoned the Electorate.” The subhed reads, “Socialists have started winning because young voters were indoctrinated rather than educated.”

It goes downhill from there:

The terms of the controversy over higher education hardly changed for three or four decades. Conservatives complained of political activism freezing out serious scholarship. Liberals rejected that criticism as politically motivated and argued that Marxist professors do little harm because students see through and laugh at their ideas. But the recent spate of electoral wins by socialists has confirmed the conservative camp’s worst fears. Those ineffective Marxist professors, it seems, have changed the educated electorate so profoundly that hitherto unelectable socialists can now prevail across the country.

Liberals are paying the price for their complacency. Radicals have begun to attack the center-left as intensely as the right, trashing the legacy of Western civilization on which both major parties previously rested. The values they invoke to denounce the West—democracy, equality, human rights—are very much part of that tradition. These aren’t the well-meaning youthful idealists they were claimed to be, but hard-core revolutionaries who go beyond calling for abolition of capitalism and private property and advocate measures that even Stalin and Mao would have thought lunacy: abolishing police and prisons, dismantling the military, opening the borders. Get ready for lawless mob rule.

But as we contemplate academia’s degradation of the electorate, we must not forget the rest of the far-reaching damage it does. Education departments that instill poisonous ideologies in schoolteachers have depressed children’s test scores in reading and math to historic lows. Journalism, law and medical schools put woke indoctrination ahead of competent professional training.

Virtually our entire educational system has been captured by destructive political radicals, and it is madness for an advanced society to know this is happening and do nothing to stop it. Optimists who think the foolishness will blow over are mistaken. We’re now seeing the effects of one generation indoctrinated by Marxist-dominated campuses. A second is on the way. As the last cohort that had a real college education begins to vanish, our constitutional order will go with it.

There are so many things wrong with this op-ed. But let’s focus on the two most obvious ones.

First, correlation does not equal causation. Ellis was a professor of German literature at UC-Santa Cruz. He was clearly not a social science or science professor, because our branches of the academy really stress causation in making arguments like this one — and Ellis does not provide a scintilla of causal evidence to advance his argument. His logic is simple:

  1. The political affiliation of the academy has shifted left

  2. ?????

  3. Socialist candidates winning everything!

Ellis is correct on point one, as almost every scholar who has looked at this phenomenon would acknowledge.

Ellis knows nothing about point two. Scholarly researchers looking into this question do not find any evidence supporting it. Even sympathetic organizations like the Manhattan Institute and Heterodox Academy acknowledge this point.

Writing in The Hill, Tom Mockaitis articulates the basic points that falsify Ellis’ assertions:

Most courses cannot be taught from an ideological perspective — left, right or center. Is there a “woke” way to teach chemistry, biology, physics, music or geology? There may be Marxist mathematicians, but there is no such thing as Marxist calculus.

A 2023 survey identified the top 10 majors based on percentage of students: business, nursing, psychology, education, biology, criminal justice, computer science, health professions, accounting and engineering.

Courses in most of these fields are highly technical and not amenable to ideological interpretation. Business,1 which attracts the most majors, has a higher percentage of conservative faculty than universities and colleges do in general.

Second, even the best version of this argument is seven years out of date. The notion that “virtually our entire educational system has been captured by destructive political radicals” requires a genuine deafness to how the political winds have blown over the last decade. Universities are too busy scrapping diversity statements, funding centers for conservative thought, and appeasing conservative trustees to be able to indoctrinate anyone into Marxist ideology. Conservative activists have not gotten everything that they wanted. Nevertheless the result is mostly affirmative action for mediocre conservatives, and as a result the right-wing political correctness has gotten out of control. The point, however, is that Ellis is acting like it’s 2016 all over again.

There is more I could say but there is little point devoting more words to deconstructing this kind of claptrap than Ellis devoted to it.

In a Pepperdine Beacon interview that Ellis gave in April 2025, he stated, “The public [must believe] something is really so wrong that it’s got to be changed. I think that is a requirement. We’re getting there on that one. Even so, it still needs to keep going. I mean, we still need to have that perception sink deeper and deeper into the public. But then the question arises: What levels do you have? What steps can you actually take?”

For Ellis, I guess the final step is just bald-faced lies.

This is fine; he can rant to his heart’s content. I just wish that the Wall Street Journal’s op-ed page would stop publishing steaming piles of horseshit until they figure out what is actually going on.

<https://danieldrezner.substack.com/p/the-op-eds-about-higher-education> <https://danieldrezner.substack.com>

Drezner’s World
The Op-Eds About Higher Education Need to Stop Until We Figure Out What the Hell Is Going On With the Op-Ed Contributors
Last week was a long one on the road for me — it started in Toronto and ended in New York. There were definitely some highlights - take a gander of some of these views I caught in both cities…
Read more

Brad DeLong here: Three years ago I thwumped my friend Matt Yglesias.

Share DeLong's Grasping Reality Weblog

I thwumped him for giving too much credence to that line of argument that Drezner rejects here:

Matt Yglesias (2023): Thankful Mailbag <[www.slowboring.com/p/thankfu...](https://www.slowboring.com/p/thankful-mailbag>)>: ‘The current trends on campus are toward an atmosphere where the radical criticism predominates…. The critical theories themselves would tell you, there’s no way Anglo-American liberal capitalist society is going to sustain generous financial support for institutions whose self-ascribed mission is to undermine faith in the main underpinnings of society…

I wrote <https://braddelong.substack.com/p/successful-future-humanities-programs>

that this appeared to me to be horseshit: Let’s collect a little data here…. Here at the University of California at Berkeley, I ought to be in the Belly of the WOKE BEAST if anyone is. What do I see if I look around? Here, from a file near the top of my “Downloads” folder, is a page from a Berkeley history-department current-semester syllabus:

Refer a friend

What do I think?…. “Radical criticism” does not predominate. Indeed, radical criticism is only presented here by Harvey—which, I admit, I would never assign: I do not find him wise, or widely read outside of his narrow personal bubble, and I find it very difficult to read him with a hermaneutics of charity: I find myself thinking “this cannot be written in good faith” every other page. But taking the entire course to be part of a “self-ascribed mission is to undermine faith in the main underpinnings of society”? Definitely not.

I concluded that I had found:

  • A somewhat excessive mindshare given to Marx and his epigones—Frankfurt School, and, cough, Harvey—in Legal Studies and Media Studies…

  • A little too much drinking of the old-fashioned “WESTERN CIV” koolaid in Classics…

  • A [single] History course that I would put under the aegis of Matt’s “instructors who endorse the radical critiques…”—although I would add that what disturbs me is not the instructor’s position, but rather the narrowness of the reading list. But that is perhaps (probably?) offset in lecture. I do not know, and rather than presume I should find out…

Get 75% off a group subscription

By “narrowness of the reading list” I meant that the readings on World War II consisted of one reading on the bombing of Hiroshima and a second on the Japanese-American internment camp at Manzanar. Do the readings, and you would not know that the fact that the big WWII story is defeating Nazis (and imperial Japanese colonialism) Yes, the internment of Japanese-Americans was a hideous and cruel error. Yes, Truman probably was not happy afterwards with his decision to barbecue more Japanese civilians with atomic weapons… but, still, if this is Hamlet, shouldn’t the Prince of Denmark appear as the protagonist of even one scene? And when I gave this course another chance, well: “World Trade Organization, Apartheid, Nelson Mandela, Genocide” are not adequate keywords for the topic of “Globalization”.

But, as I said, I should have looked at the lecture notes to get a full sense of the course, and I did not.

However, even taking in that, what I saw was lots of smart people—many of whom I have profound disagreements with—teaching a lot of different things. I did and do not see any collective “self-ascribed mission… to undermine faith in the main underpinnings of society”. I did not see any group unwillingness “to do what society wants them to do and expound on the greatness of our civilization”.

Thus I line up with Dan Drezner here.

Now you can line up with Nils Gilman here:

Nils Gilman (2025): How Did Academia Not See It Coming <https://nilsgilman.substack.com/p/how-did-academia-not-see-it-coming>: ‘Because to see it coming would have required a direct confrontation several decades ago along the central ideological dividing line within academia…. Liberals have been the predominant force, certainly within the administrations, but also within the faculty as a whole. At… Berkeley… the radical faculty probably never have amount to more than ten or fifteen percent… but… tended to be very noisy, thinking of themselves in many cases as “activist-scholars,” for whom criticizing the fecklessness of their liberal colleagues and resisting the neoliberal administration of their universities is a core part of the public identities…. These people, it should be noted, are generally loathed (or sometimes pitied) by the mainline liberals….

In the 1990s… a standard normie liberal critique of poststructuralism was that the anti-Enlightenment epistemic radicalism of the left, while overtly trained against the complacencies of small-l liberalism, would eventually “make space” for right wing critiques of liberalism. This was a point that Jurgen Habermas made over and over again in his many debates with the likes of Hans-Georg Gadamer, Michel Foucault, Jacques Derrida, Niklas Luhmann, and others…. Abandoning discourse ethics and embracing epistemic relativism, cynicism, or even nihilism… [was] sapping the epistemic foundations of democratic practice, which depended on the “regulative ideal” of reasoned, good faith discourse as a mechanism for achieving a “fusion of horizons.”… They won’t be the first or the last radicals to be consumed by their own politics…

Point.

And if there is a bigger point it is that liberals’ avoidance of conflict within the academia in the interest of academic comity and being left to do your own work has been a mistake. And that bullshit should be called out—as Dan Drezner does here with bullshit from the “right”.

Which means that my next piece should be a crosspost I have been thinking about calling out bullshit from the “left”, although it is not any real left in any sense that I recognize.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-dan-drezner-the-opeds-about-higher-education-need-to-stop-until-we-figure-out-what-the-hell-is-going-on-with-the-opeds-contributors
##public-reason
##academia
##crosspost
#dan-drezner-the-opeds-about-higher-education-need-to-stop-until-we-figure-out-what-the-hell-is-going-on-with-the-opeds-contributors
#the-opeds-about-higher-education-need-to-stop-until-we-figure-out-what-the-hell-is-going-on-with-the-opeds-contributors
#higher-education
#academic-freedom
#campus-indoctrination
#wall-street-journal
#john-ellis
#right-wing-correctness
#university-politics
#nils-gilman
#calling-out-bullshit

Spending on “Tokens”: CHART OF THE DAY

Why are there now signs that corporate AI spending has stopped growing? Usage is still rising, but token prices are falling. Anthropic's Claude premium over OpenAI shrank from roughly 2.4 times OpenAI's price in March to 1.67 times in October. Meanwhile OpenAI cut its own prices by about a third, both to compete with Anthropic and to keep firms from building on cheap or free models. The counterfactual matters most: what would spending look like if prices had held at spring levels? Nobody knows. It is way too early to declare AI demand exhausted because of a lack of actual profitable usage cases:

Thus I see it differently than Torsten Slok.

  • He sees AI infrastructure spending continuing at a high pace only if the corporate profits of AI-adopters explode upwards.

  • I see it being driven partly by greed, which does need to be validated by results, but mostly by fear, which does not.

Companies are being driven to be AI-adopters out of the fear that if they do not have natural-language interfaces, or if their natural-language interfaces are too slow or error-prone, then competitors who do have the cloud mojo to deliver accurate instant natural-language interfaces will insert themselves between the laggard company and its customers, and the laggard companies’ profits will evaporate.

Hyperscaler platform-monopolists have platform-monopoly profits to protect. Anthropic and Open AI have Digital Gods to build, and spending so much on access to datacenters that their nascent future Singularities can be the things inserting themselves between customers and laggard companies is a way to demonstrate that they can earn revenue to keep funders’ wallets open. Plus a lot of engineers want to play with powerful new technologies, have fun, maybe find a market niche, and get it all paid by the startup-investor ecosystem. And then there are all the “number go up!” people who were desensitized to fundamentals by BitCoin.

So I do not see token spend by corporations seeing out-of-control costs for no visible return as dispositive in any way <https://techcrunch.com/2026/09/09/ai-spend-per-employee-slumped-at-top-firms-in-august-summer-doldrums-or-a-warning-sign/>. Yet.

Torsten Slok sends us to the “RAMP AI” data survey:

And he comments:

Torsten Slok: Slowing Token Spend Shows Compute Demand Isn’t Unlimited <https://www.apollo.com/wealth/insights-news/insights/daily-spark/slowing-token-spend-shows-compute-demand-is-not-unlimited>: ‘Compute appears to face a flat, highly price-sensitive demand curve, where even modest changes in token prices can drive buyers to throttle usage or substitute cheap open-source alternatives…. The squeeze is showing up on the supply side too. Return on invested capital for the five largest hyperscalers is declining, as invested capital grows faster than the earnings it generates….

[If] the marginal cost of producing compute exceeds the marginal benefit it delivers to users, [that] rais[es]… questions about claims of unlimited demand for data centers…. So far, the AI payoff for firms has been slow to materialize…. Companies will only pay a high price for that compute if they are able to turn the compute into higher top-line growth… little of which is showing up at scale yet. Maybe that will come in the future…

Ramp <http://ramp.com> is a corporate credit-card and bill-pay company. Its chief economist, Ara Kharazian, started the Ramp AI Index building from Ramp’s transactions data in the early spring of 2025. It now covers, I am told, about 70,000 companies. And Kharazian has hit the visibility jackpot with the recent addition of his series (also broken down by provider, by industry, and by firm customer size) to <https://fred.stlouisfed.org/blog/2026/10/which-businesses-are-using-ai-technology> the Federal Reserve Bank of St. Louis’s FRED database:

Yes, Ramp customers are massively tech-forward. Yes, it does not capture free tools or employees’ personal accounts or spending that flows through intermediaries that do not use Ramp. Yes, spending is concentrated, with 80% coming from the top 1% of Ramp customers. But it is what we got.

Kharajian himself recommends looking not just at spending but at the volume of use, and at prices:

In Kharajian’s data, in October Anthropic was charging an average of $0.0000008 per token, while Open AI was charging $0.00000048: 2/3 more for Anthropic. At the height of Claude-Codeism last March it was $0.00000170 and $0.0000007: just a hair under 1 1/2 times more for Anthropic <https://ramp.com/data/ai-index-oct-2026>. Some of the slowdown in token spending growth is Anthropic’s Claude premium under massive pressure. Rather more of the slowdown in token spending growth is OpenAI’s cutting its prices by 1/3 since March, partly to gain traction against Anthropic and partly to try to keep people from investigating and building cheap- and free-model usage capabilities. Very little of the slowdown in token spending growth is a slowdown in the rate of growth of use of tokens, at least in Ramp’s data.

What would have happened had OpenAI maintained its prices at their spring levels and had Anthropic maintained its then-massive Claude premium? I would dearly love to know. I do not know. I would dearly love to.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##spending-on-tokens-chart-of-the-day
##attention-info-bio-tech-economy
##mamlms
##chart-of-the-day
#spending-on-tokens
#torsten-slok
#ramp-ai-index
#ara-kharazian
#ai-spending
#token-prices
#compute-demand-and-the-token-price-war
#anthropic
#openai
#claude-premium

When Software ‘Bots Go Feral: MONDAY MAMLMS

I set up my email ‘bot to honor #handcarry: the one tag meaning “don’t file this, bring it to me NOW!” But it drifted. One time it typoed it as #hancarry, and then wrote that into its own memory file. It then built a new directory …/hancarry/, and for about a week diligently filed urgent emails there, buried deep in the directory tree structure. No refusal, no sulking: a model bureaucrat whose output reached no one. Unlike loud, surly agents, this failure was silent and obedient, which made it harder to catch:

It had seemed quieter than usual around here.

Share

Somehow, the flow of emails being resurfaced within hours to my immediate attention had grown thin.

Background: One of the things I have long done has been to have me, or for someone I delegate, #handcarry pieces of administrative paperwork on which I wish urgent action directly on up to the bureaucratic office concerned. Look the recipient who has to handle the piece of paper in the eye. (Or, more likely, and often more fruitfully, their schedule-controlling admin.)

I picked this up long ago from others, back when I worked for the US Treasury. It has served me well.

So I set up a similar system for my ‘bots.

And that is the context for this interaction:

Give a gift subscription

It had made a typo: it had registered the hashtag #handcarry as #hancarry.

Then, rather than surfacing #handcarry emails immediately back to my attention, it had considered their existence, and decided to construct a new directory—/Users/delong/.openclaw/workspace/filing-agent/processed/hancarry/. It then began to diligently file the #handcarry emails there in …/hancarry/. Once the mistake had been made, it stuck. Every email tagged #handcarry got carefully and diligently filed away in …/hancarry/. For a week. Until I noticed that my …/handcarry/ directory—the one I actually look at—was empty when it definitely should not have been, and went looking.

Yes: natural-language interfaces are wonderful ways to interface with information-technology systems.

Much of the time.


Now you might justifiably classify this as user error.

Consider what #handcarry is for. It is the one tag in my system whose entire meaning is: do not file this. Do not put it in the queue. Do not process it in the ordinary way. Pick it up, walk it down the hall, and put it in front of the human being who will look at it: me. It is the escape hatch from the bureaucracy. But in form it is a #hashtag for filing in a directory exactly like everything else that gets looked at by the Hashtag Filing Protocol. I am thus overloading “#”. And overloading is bad.

Point.

But not game, or set. The promise of the Silicon Valley TechBros this day is that the machines will adapt to work smoothly with us, the way we already work. MAMLMs are supposed to be able to deal with linguistic ambiguity. They are supposed to be trainable to pay attention to and parse out the right bits of linguistic context. And we are told over and over again that that Attention Is All You Need.

But my ‘bot took my escape hatch from the ordinary procedures of bureaucracy, and it turned it into a new filing cabinet.

I want to stress how well it did this!

  • There was no refusal.

  • There was no idleness.

  • There was no sulking.

Leave a comment

Read more

CROSSPOST: Ben Moll & Alex Imas: Will AI Soon Lead to Double-Digit [Annual Economic] Growth?

Past waves of automation have followed a script. Agriculture mechanized, got cheap, and shrank as a share of GDP, and value moved to manufacturing. Manufacturing automated and shrank, and value moved to services. Ben Moll and Alex Imas argue AI will follow that script rather than break it. Cheap cognition will push spending toward what stays scarce: nurses, teachers, waiters, local knowledge, power plants, Zeiss mirrors:

Ben and Alex see a 4–5% rate of real GDP growth—a doubling of productivity—from “AI” over the next fifteen years as the current thing grows exponentially before (probably? perhaps?) turning into a logistic headed for its asymptote.

Share

They write:

Ben Moll & Alex Imas: Will AI Soon Lead to Double-Digit [Annual Economic] Growth? <https://aleximas.substack.com/p/will-ai-soon-lead-to-double-digit>: Double-digit growth in the next 10-15 years would require machines to do most of the economy’s work by 2035, people to keep spending on whatever gets automated, buyers and investors who absorb the new output, AI that never destroys value or slows its own deployment, and an R&D loop for which there is no evidence thus far. Each of these assumptions may fail in the real world. Whatever the exact number, a much more likely outcome is a large increase in the level of GDP spread over a decade or two, which is what (say) 4-5% growth is. If you remain unconvinced and still believe in double-digit growth, we are still looking for counterparties for our bet…

Give a gift subscription

Only a third of the economy consists of paid-for knowledge work. There is a “relational sector” of services where human involvement is the value that creates a demand-side floor. The non-automatable sector will be larger than that. Amdahl’s Law—the with Leontief production or utility the speedup is limited to the size of the sector to be sped up—lurks in the background: growth is limited by what is essential and yet hard to improve. Explosive transformation will be hindered by real-world frictions: slow diffusion, physical constraints, relational demand, and political resistance. Add in messy jobs and limits on physical inputs, and hopes of 10% per year growth are more seem unattainable.

Plus “Singularity”-talk requires AI to fully replace researchers and overcome falling research productivity. There is no evidence it can do either:


CROSSPOST: Ben Moll & Alex Imas: Will AI Soon Lead to Double-Digit [Annual Economic] Growth?

<https://aleximas.substack.com/p/will-ai-soon-lead-to-double-digit> <https://aleximas.substack.com>

Ghosts of Electricity
Will AI soon lead to double-digit growth?
The following post represents the personal views of the author(s) and does not reflect or represent the positions of their employers…
Read more

Probably not. Here is why.

Ben Moll and Alex Imas

Sep 09, 2026

The following post represents the personal views of the author(s) and does not reflect or represent the positions of their employers.

This piece outlines the economics behind oft-discussed predictions that AI will soon deliver double-digit GDP growth in advanced economies. Anthropic CEO Dario Amodei says that AI could push growth to something like 10-15 percent per year. Leopold Aschenbrenner’s essay “Situational Awareness” states that the decade ahead “could see economic growth rates of 30%/year and beyond.” And in a widely shared tweet, Anthropic researcher Sholto Douglas advises “pricing in economic doublings into your mental models of the 2030s,” with Elon Musk endorsing the tweet. That is a growth rate of 100 percent per year. These are not isolated examples: predictions of double-digit growth are common among AI insiders, as Tom Cunningham’s compendium of AI growth forecasts for 2025-2035 shows.

We are extremely bullish on AI and think the capabilities explosion predicted by technologists is already happening and will only continue. But an explosion in capabilities is unlikely to translate into double-digit growth because of the (sometimes counterintuitive) economic forces that generate GDP growth in the first place. To paraphrase Milton Friedman’s dictum about monetary policy, AI will affect GDP growth with “long and variable lags.” We will not argue about what the economy might look like in 2080 or 2100. Our claim is about the timeline: in the next 10-15 years, growth rates upwards of 10% are extremely unlikely and a much more reasonable baseline is, say, 4-5% (which would already be massive). Even Anthropic’s own economic model only reaches double-digit growth in its “extreme” scenario; its “modest” and “substantial” scenarios stay well within the single digits. The uncertainty around these numbers is enormous and we are not making a forecast; instead our aim is simply to outline the assumptions that need to all hold in order for double-digit yearly growth to happen and to explain why we think they won’t. We have put money on this: see this bet that US per capita real GDP growth will stay below 15% in every year through 2033.

Outline and Overview

This piece proceeds in four steps:

  1. Before starting, we remind the reader of some basic growth rate arithmetic. We argue that it is often much more useful to first think in levels rather than growth rates. That is, to ask yourself “how much richer will we be, say, 15 years from now?” and then back out the implied growth rate rather than directly jumping to predictions about growth rates. This simple exercise can often prevent drawing overly fast conclusions from seemingly small growth rates. For example, if you think that we will be 200% (i.e. twice) as rich 15 years from now that implies an annual growth rate of 4.7%. That is, a growth rate in the 4-5 percent range would already be massive.

  2. With this in mind, it is important to be clear that, theoretically, it is entirely possible that AI will cause GDP growth to explode to double digits within a short time frame or that the economy will, say, double every single year some time in the 2030s. That is, there is absolutely nothing in standard growth theory that constrains growth rates to be in the single digits. In fact, as we show below, it is easy to write down a standard textbook growth model of the type we routinely teach our undergrads (a souped-up Solow model), plug in some seemingly innocuous parameter values, and get an AI-driven short-term growth explosion. The basic logic is that, by replacing labor with capital, automation alleviates / eliminates diminishing returns and removes labor as a bottleneck on growth. Other (and fancier!) modeling approaches yield the same prediction based on the same logic.

  3. But just because something is possible in theory doesn’t mean it will actually happen in practice. The reason is that theories that predict explosive growth make a number of implicit assumptions that are unlikely to be satisfied in the real world. We group them into five categories:

    • Assumption 1: Fast, economy-wide automation

    • Assumption 2: Continued high spending on what gets automated (no messy jobs, no relational goods, no scarce physical inputs, no goods of any kind which are both demanded by consumers but whose production process is not fully automated)

    • Assumption 3: There is someone to buy the output and firms invest to produce it

    • Assumption 4: No AI-driven cyber incidents destroying economic value

    • Assumption 5: Explosive technology growth because AI automates R&D

    We discuss why each of these assumptions may be violated in reality despite a capabilities explosion, and explain why AI is different from dropping a million new workers into the economy. In addition, various measurement issues mean that GDP may not fully pick up the welfare gains due to AI.

  4. We conclude by discussing possible reasons why people may have unrealistic growth rate expectations. Our main explanation is that it may be hard to “see the forest for the trees” and people may extrapolate from their immediate environment to the rest of the economy. Other reasons may include motivated reasoning, or that they are seduced by the elegant mathematics of growth theory.

1. Think in levels not growth rates

Before turning to AI, we start with some basic growth rate arithmetic. Our point is that it is often much more useful to first think in levels rather than growth rates, and only then to back out the implied growth rate, rather than jumping directly to predictions about growth rates. That is, a good question to ask yourself is: how much richer do you think we will be, say, 15 years from now? By what percentage do you think the level of GDP will have increased by then? Once you have settled on a number, convert it back into a yearly growth rate. The following table does this conversion:

Asked this way, we bet that most people would come up with much lower growth rates than if they had been asked about growth rates directly. For example, us being twice (200%) as rich in 15 years as we are today seems like a lot. But it implies an annual growth rate of “only” 4.7%. Put differently, a growth rate in the 4-5 percent range would already be massive. Add to this that the jump from the current ~2% growth to a higher growth rate won’t happen overnight but instead gradually, and you get even higher implied growth rates for the same level effect: if growth is still low in the first years, later growth has to be all the faster to reach the same level of GDP by 2041. On the other extreme, a growth rate of 16.6% would mean that we would be 1,000% (10x) as rich 15 years from now.

It is also interesting to extrapolate these numbers another 15 years into the future, to 30 years from now, as in the last column of the table. Here you can see that high growth rates lead to some extremely wild numbers. For example, 16.6% annual growth would mean that we will be 10,000% (so a factor of 100) as rich as today. This is the arithmetic to keep in mind whenever someone predicts double-digit growth rates: such predictions are not modest claims about the economy doing a bit better, they are claims about a hundredfold gain within a generation.

2. It is easy to obtain AI-driven explosive growth in theory

Before arguing that double-digit growth is unlikely in the next 10-15 years, we want to be clear that there is nothing wrong with this idea in principle. There is absolutely nothing in standard growth theory that constrains growth rates to be in the single digits. To make this point concrete, we first show that a very standard textbook growth model, of the type we routinely teach our undergrads, delivers an AI-driven growth explosion. We then briefly discuss fancier models and other mechanisms that deliver the same or even wilder predictions. The basic logic is always the same: by replacing labor with capital, automation alleviates or even eliminates diminishing returns and removes labor as a bottleneck on growth. A recent episode of the Dwarkesh podcast states the logic intuitively: “... right now we’re bottlenecked by the fact that there’s people, and you can’t double people every single year. But in a world where you can also double the labor force every single year, how fast can the economy grow? I think it could double every single year. At the very least it would be tens of percent every single year.”

A textbook Solow model of the type we teach our undergrads delivers explosive AI-driven growth

The model combines two standard building blocks, explained in detail in the technical supplement to this blog post. The first building block is a task-based production function in the tradition of Zeira (1998) and Acemoglu and Restrepo (2018): producing output requires completing a list of tasks, every task can be done by workers, and a fraction α of tasks can also be done by machines. Automation means that α increases over time. The second building block is the standard Solow model: a constant fraction of output is saved and invested in machines. In reduced form, the model boils down to two familiar equations:

where Z = Z(A,α) and A is the level of technology which grows at a constant rate. The key property is that the capital share of this Cobb-Douglas production function equals the share of automatable tasks α. That is, automation raises the exponent on capital.

The mechanics are then simple. As long as some tasks can only be done by workers (α below 1), capital accumulation runs into diminishing returns: the human tasks are the bottleneck, growth from accumulation alone peters out, and long-run growth is pinned down by technology growth. This is the standard Solow logic. But automation weakens this brake. When every task can be done by machines (α equal to 1), diminishing returns vanish entirely: output becomes linear in capital and the economy turns into the “AK model” from the endogenous growth literature. Machines produce output and output is used to build more machines, so the economy keeps growing without labor being a bottleneck. Technology growth on top of this makes the growth rate itself grow over time.

To show what this means quantitatively, we calibrate the model in the most standard way possible (2% initial growth, a saving rate of 20%, an initial α of one third, i.e. the usual capital share) and assume that the share of automatable tasks rises from one third today to 100% by 2045. The figure below shows the result. Growth accelerates from 2% to about 12.5% by 2035 and keeps rising thereafter; by 2045 GDP is roughly 8 times its 2025 level (panel a, blue line). If, in addition, the saving rate responds to the soaring return on machines (green lines), growth reaches 15% already by 2034 and 20% by 2045. In short: a textbook model with seemingly innocuous parameter values delivers exactly the growth explosion the optimists describe. (The transition is much less benign for workers: the wage temporarily declines and grows much more slowly than GDP, and the labor share goes to zero. See the technical supplement.)

Figure: It is easy to obtain AI-driven explosive growth in theory. In our souped-up Solow model (see supplement), the economy transitions to full automation: α rises from 1/3 to 1 over 2025–2045. Panel (a): GDP (ratio scale) with and without automation; the labels on the dots report GDP relative to the no-automation trend. Panel (b): the GDP growth rate, with values at each decade. Blue: baseline fixed saving rate; green: endogenous saving rate. The shaded band is the 2025–2045 automation phase; the dashed vertical line in panel (b) marks the baseline’s switch to the cost-parity regime in 2041.

Fancier models and other mechanisms

Our Solow model is deliberately minimal, but many richer models deliver the same or even wilder predictions. The canonical treatment is Aghion, Jones and Jones (2019), who analyze automation in both goods production and R&D and characterize the conditions for “singularities.” Trammell and Korinek survey the whole literature and we already mentioned Cunningham’s compendium. Other academic examples include Korinek and Suh (2024), who work out AGI transition scenarios in which growth accelerates sharply, and Restrepo (2025), who studies an AGI economy in which compute replaces labor as the accumulable factor, output becomes linear in compute, and the labor share converges to zero.

The most important addition relative to our Solow model is that AI also automates R&D, so that technology growth itself accelerates. In standard (semi-endogenous) growth theory, new ideas are produced by human researchers,

so idea production is bottlenecked by the size of the research workforce: you cannot double the number of researchers every year. If AI automates R&D, then researchers are also replaced by machines and idea production instead tracks the capital stock,

Note that this is exactly the same logic that turned our Solow model into an AK model, now applied to the knowledge production function: the human bottleneck is replaced by machines, which can be accumulated, this time in the R&D lab rather than on the factory floor. The result is a powerful feedback loop between the two accumulation equations: machines produce ideas, ideas raise output, and output is invested in more machines, so that technology growth explodes together with output.

This feedback loop is the engine behind much of the explosive-growth discourse, from Davidson’s Open Philanthropy report to Epoch’s GATE model, Erdil and Besiroglu’s review, and Aschenbrenner’s “Situational Awareness”. Binder’s industrial-explosion series runs the same machines-building-machines logic through detailed sector-level data to compute how fast a fully automated economy could maximally grow, and his answer is a doubling time of roughly one year. And Davidson, Halperin, Houlden and Korinek show that even substitution bottlenecks need not prevent explosive growth if task automation advances fast enough.

A clean example of how these models get their explosion is Epoch’s piece on automating remote work. Matthew Barnett splits the economy into remote tasks, about a third of all work, and non-remote tasks, combines them in a CES production function, and asks what happens if AI multiplies the supply of remote workers a hundredfold or more. With an elasticity of substitution of 0.5, GDP roughly doubles; with an elasticity of 10, it grows more than tenfold, which Barnett considers “slightly more likely than not.” The tenfold number rests on two assumptions: there is no demand side, so the price of remote-work output never falls and its share of spending never shrinks, and the remaining two thirds of the economy are “unlikely to become major bottlenecks in production.” That is the sentence that assumes away our Assumption 2 below. We single out this piece for its transparency: most explosive-growth models work the same way, the explosion enters through a substitution parameter and the absence of a demand side, and the rest is arithmetic.

The details thus differ across models but the mechanism is always the same: automation turns labor, the fixed factor, into something accumulable, so diminishing returns no longer bind. What the fancier models add are feedback loops (better AI makes better AI, more machines make more machines) that make the explosion faster or push growth rates higher. And all of them assume that nothing people still want stays scarce.

3. Just because something is possible in theory doesn’t mean it will actually happen in practice

The models from Section 2 are useful for making this argument because they make transparent what double-digit growth by the early 2030s actually requires. We now go through the five assumptions behind these requirements one by one (Assumptions 1 to 4 concern our Solow model, Assumption 5 the accelerated-R&D mechanism). We argue that each of them is unlikely to be satisfied in the real world, in particular within the next 10-15 years.

Assumption 1: Fast, economy-wide automation. To get the explosive double-digit growth rates, our Solow model fed in a fast transition path for the share of automatable tasks, in particular machines doing two thirds of all tasks in the economy by 2035. But this is an assumption, not a result. Three things stand in the way.

Slow diffusion. Compare the assumed path to history: Jones and Tonetti estimate that automation has historically proceeded at roughly 2% of tasks per year for two centuries, without ever pushing growth much above 2%. Past general-purpose technologies also took decades to diffuse even after the technology itself worked. For example, electrification took around 40 years to show up in factory productivity. Similarly, Comin and Mestieri’s study of technology adoption across countries documents average adoption lags of around 45 years, and still 7-18 years for more recent technologies. AI adoption appears to be much faster than that of the PC or the internet, but adoption is only the first step: measured productivity typically first falls while firms make the necessary complementary investments, the “productivity J-curve” of Brynjolfsson, Rock and Syverson. Even the most bullish insiders are noticing this, for example Sam Altman who recently conceded: “I think I was wrong about a few things, but one of them, in terms of the speed, one of them is the economy just has so much inertia. [...] we’ve all been too ambitious on timelines [...] Society and the economy will adapt more slowly.” Self-driving cars are a good current example of slow diffusion: Waymo has had the basic technology for roughly a decade, and yet robotaxis still operate in only a handful of cities.

Most work is physical. An AI capability explosion is first and foremost an explosion in cognitive capabilities. But only around a third of the economy consists of work that can be done on a computer (Epoch AI’s remote-work piece). The rest of GDP is produced in mines, on construction sites, in kitchens, hospitals and care homes. Automating two thirds of all tasks by 2035 therefore requires robots that do a large share of physical work. These robots would need to be designed, manufactured, installed and maintained by the billions within a decade. While progress is certainly happening, robotics development is slower than software development and robots that can do a wide range of physical tasks at close to the cost of a worker are still not on the horizon (note that this excludes industrial robots, which are indeed developing fast). “Capability explosion” and “automation of most tasks” are not the same thing. Conflating the two is a central stumbling point for predictions of explosive growth.

Politics. The simple Solow model’s own predictions are the best argument against a frictionless transition. Along the transition, wages temporarily decline below their pre-automation level, and the labor share falls from 67% toward single digits (Figure 3 of the supplement). The model assumes that society simply lets this happen. In reality, such a transformation would generate enormous political resistance. Furthermore, the required creative destruction affects some of the most regulated parts of the economy: housing, healthcare, law, education, infrastructure (see also Ben Jones on the political economy of explosive growth). Political resistance and regulation would therefore slow down this fast pace of automation. The potential for AI safety incidents, which we discuss under Assumption 4, will add to the pressure for regulation.

Assumption 2: Continued high spending on what gets automated. In the model, the output of a task is the same whether a worker or a machine produces it, and the economy spends on tasks in fixed proportions. So when machines take over a task, that task keeps its weight in GDP and the machines keep collecting its income. This is the Cobb-Douglas assumption. In reality, when automation makes the automated thing cheap, people and firms do not buy proportionally more of it. Spending instead shifts to what is still scarce, the tasks still performed by humans. The automated part shrinks as a share of the economy and the human part grows. This is Baumol’s cost disease, or in the words of Aghion, Jones and Jones: “growth may be constrained not by what we do well but rather by what is essential and yet hard to improve.”

This is the assumption we think matters most. In the AI case, the non-automatable part has three facets: jobs that stay human because of how production works, goods that stay human because of what people want, and physical inputs that no amount of cognition makes abundant. Each of these constrains growth. If there is indeed demand for goods and services that are not automated, growth is constrained by this part of the economy, which is unaffected by the AI capabilities explosion. For growth to explode, the non-automatable part of the economy has to shrink to close to zero within a decade.

This obviously precludes demand for new goods and services that have an non-automatable component—a feature that has been emblematic of structural change. See, for example, the share of GDP going to agriculture, manufacturing, and services over time. As agriculture became more automated, its share of GDP shrank as the goods became cheaper and people became richer as a result. Where did value go? To goods and services which had demand but were not automated yet—manufacturing. As manufacturing became increasingly automated, the prices of those goods fell and the sector became a smaller part of GDP. Where did value go? Services. This logic is laid out nicely in the excellent paper Structural Change with Long-run Income and Price Effects and the implications for AI and automation are outlined here. Here are a few more concrete examples.

(a) Messy jobs. In standard task-based models (like the one above), a task is either done by a worker or by a machine, and machines simply take over tasks one by one. But as Luis Garicano points out, “the task is not the job.” Jobs are instead bundles of tasks that are hard to break up: the tasks feed into the same output, rely on the same local knowledge, and someone has to be accountable for the result.” This is the famous radiologist example: radiologists were predicted to be eliminated years ago, but the radiologist labor market is as healthy as ever. Relatedly, Garicano, Li and Wu argue that many jobs are “messy”: AI can commoditize codified knowledge but cannot reach the local knowledge that much of the economy runs on. Reorganizing firms so that tasks can actually be unbundled and handed to machines is itself a slow process. So messy jobs stay human for a long time and their share in production and spending grows as everything else gets cheaper.

(b) Relational goods. In the model, the output of a task is identical regardless of whether it is produced by a worker or a machine. But for a large class of services, the human provider is part of the product itself: think of teachers, nurses, therapists, waiters, priests, live performers. Alex calls this the “relational sector” and argues that it will grow as a share of the economy precisely as AI makes everything else cheap. Notably, the reference class for this sector is broad: it includes any good or service where human involvement is part of the value. This likely includes many familiar jobs such as doctors, nurses, educators, and advisors, as well as new jobs that will be created in response to this latent demand.

The logic comes from the economics of structural change: as people get richer, they spend a larger share of their income on goods and services with high income elasticities, and relational goods have exactly this property (there is always a better restaurant or a more attentive doctor). A nice current example is Starbucks, which spent years automating its stores, concluded that this was a mistake, and is now hiring more baristas and advertising handwritten notes on cups. This argument is related to but distinct from the messy jobs argument: messy jobs are hard to automate for reasons of production (local knowledge, accountability), relational tasks are hard to automate for reasons of demand (customers value the human). Either way, a substantial and growing part of the economy consists of tasks where machines cannot effectively substitute for workers.

(c) Essential inputs. The same logic applies to the machines themselves. In the standard model, consumption can immediately be converted into capital one-for-one: there are no construction lags, no adjustment costs, and no need for energy, land or permits. In practice, the fast-growth path has to be produced with today’s capital stock, that is, with today’s factories, power plants and electricity grid. Each doubling of the machine stock comes with an enormous energy and construction bill, and the serial steps involved (mines, mega-projects, grid interconnection) take years to decades each. The AI supply chain itself is a good example: the ASML lithography machines behind every advanced AI chip depend on precision mirrors that a small number of highly specialized people at Carl Zeiss produce in volumes far below what the labs want. Even the technology that is supposed to abolish the bottlenecks is constrained by many such bottlenecks. Proponents of explosive growth themselves concede much of this: Binder’s own adjustments for construction lags and energy constraints cut his maximal growth rates roughly in half, and Trammell and Korinek note that explosive growth can only run “until production reaches limiting factors such as energy production or land usage.” Put differently, even granting the capabilities, the next decade will largely be spent building the machines rather than growing at the rate the finished machines would allow.

What this means for growth. The share of factor income paid to computers has fallen over the past 25 years, from around 4.3% in 2000 to around 3% today (Figure 2 of Jones and Tonetti, reproduced below). Precisely because computers became so much better and cheaper, the income paid to computing capital shrank as a share of the economy. Hence, in the data, the sector with the capability explosion became smaller. Based on this observation Jones and Tonetti calibrate an elasticity of around 0.2, far below the values of 0.5 to 10 in the Epoch exercise of Section 2, which come from substitution between types of workers rather than from whether people substitute away from human-provided goods and services once AI output gets cheap. Such a low elasticity severely caps what even spectacular progress on cognitive tasks can deliver.

Figure: Share of factor income paid to computers, reproduced from Jones and Tonetti (Figure 2). Despite IT explosion, the factor income share of information technology has declined over the past 25 years. Consistent with a production function with an elasticity of substitution below one.

Chad Jones calculates that, with an elasticity of 0.2, an infinite amount of what software does today would raise GDP by only about 2%, infinitely automating a third of GDP would raise it by 11%, and infinitely automating half of GDP would raise it by 19%. And when Jones and Tonetti calibrate their model to a continuation of historical automation patterns, growth reaches only 2.6% by 2075. Even in their deliberately extreme “Moore’s Law everywhere” calibration, in which the whole economy behaves like the computer sector, growth starts at 4.7% per year, exceeds 7% only by 2030 and 13% only by 2040. That is, even an extreme calibration delivers single-digit growth for the next decade. What separates the slow path from the fast one is economy-wide automation and the removal of weak links, not how smart AI is on the tasks it already does.

Assumption 3: Someone is there to buy the increased output and firms invest to produce it. In the model, whatever is produced is also bought: a fixed fraction of output is consumed and the rest is invested, so demand never constrains anything. In the real world, someone has to buy the new output, and rapid automation redistributes purchasing power away from the people who currently do most of the buying. Alex works through the resulting channels: capital owners spend a smaller fraction of their incomes than workers, so if wages fall while profits rise, demand may not keep up with the exploding supply.

The same problem shows up on the investment side and may bite for the growth path. The explosive path in Section 2 requires firms to invest 20% of output or more, but firms build capacity for the demand they expect. If they anticipate weak demand, they invest less than they otherwise would and leave some machines idle. This feeds on itself: less investment means a smaller machine stock than the explosive path requires, hence less output and income, and hence weaker demand still. The economy grows, but more slowly than its technology would allow. This mirrors the essential-inputs point of Assumption 2: there the machines cannot be built fast enough, here firms lack a reason to build them. These channels are possible in principle and further temper expectations of explosive growth. That said, we do not want to lean on this argument too heavily: direct empirical evidence on the strength of these mechanisms is so far limited.

Assumption 4: No AI-driven cyber incidents destroying economic value. In the model, machines only ever add to output. But AI can also destroy value, through two routes: AI agents going rogue, and human attackers armed with AI. The first route is no longer hypothetical, as this summer’s coordinated hack of Hugging Face by OpenAI agents showed (see METR’s independent incident report). The second route is that advanced AI models “dramatically reduce the time and cost needed to identify and exploit vulnerabilities,” as the IMF puts it, so that attacks on the shared digital infrastructure that the whole economy runs on become cheaper, faster and more correlated. Of course, AI will also make cyber defense better, but “defenses will inevitably be breached.” The financial system is one example: the IMF calls AI-enabled cyberattacks “a potential macro-financial shock,” and Bank of England governor Andrew Bailey told G20 finance ministers that frontier AI “may have the ability materially to alter the speed, scale and economics of cyber risk.” The same applies to energy, telecommunications and public services.

Every incident also slows down deployment: after the Hugging Face hack, OpenAI paused training on its newest models to upgrade security, and regulators are drawing up tighter rules. As Joe Weisenthal has argued, safety has become a real cost of frontier development: more capable models draw more scrutiny, testing takes longer, and some models cannot be deployed at all. A model that cannot be deployed cannot be monetized, which shrinks the revenue that funds the next training run and the case for building the next data center. Capabilities, deployment and investment feed on each other, and safety failures make this loop work in reverse. AI-driven cyber incidents thus slow down the fast automation in Assumption 1.

Assumption 5: Explosive technology growth because AI automates R&D. Automation alone does not deliver the wildest scenarios. In our Solow model, when technology keeps growing at its pre-automation pace, even with full automation growth only reaches 15% in the late 2060s in the baseline, or 20% by 2045 with an endogenous saving rate (the two lines in the figure in Section 2). Both are a long way from the economy doubling every year. The scenarios in which the economy doubles every year therefore rest on the second mechanism from Section 2: AI automates R&D, idea production tracks the capital stock (Ȧ = A^φ K), and technology growth accelerates. The conditions for this feedback loop to actually ignite are difficult to satisfy, particularly in the short term.

The singularity analysis of Aghion, Jones and Jones gives two routes. Both require the human part of some production function to disappear: either researchers are fully replaced by machines and ideas get easier to find as knowledge accumulates, or researchers and workers are both fully replaced, with no bottleneck in either ideas or goods production. However, Bloom, Jones, Van Reenen and Webb show that research productivity has been falling for decades, so this feedback is currently negative. The second route requires Assumption 2 to fail in two places: as long as some part of research needs people, automating the rest makes that part the bottleneck, exactly as on the factory floor. If AI instead only makes human researchers more productive, standard semi-endogenous growth theory implies a level effect rather than faster long-run growth; Blumenfeld, Hazell, Lian and Schaab quantify exactly this and find that the R&D channel roughly doubles AI’s level effect on GDP while leaving the growth rate unchanged. And if there is an upper limit to how good technology can get, the loop cannot run for long whatever the automation share. Finally, even genuinely accelerated science would feed into GDP with long lags: new drugs need clinical trials, new materials need factories. Many AI-discovered ideas in 2028 will show up in GDP in the 2040s, not by 2033.

Why a million new workers is the wrong analogy

There is an intuition behind all of this that is worth directly engaging with. If a million new workers showed up in the economy tomorrow, output would rise. AI is like adding workers without limit, so why wouldn’t growth explode? This is the logic of the Dwarkesh quote in Section 2, and it is the reason our Solow model explodes. Three things make AI different.

First, new workers can do every task, including the messy, physical and relational ones. AI instead adds labor to the third of tasks that are cognitive and can be done remotely. Adding a lot of one input to a production process where inputs are complements pushes value onto the inputs that did not grow. This is Assumption 2.

Second, new workers need housing, offices and tools before they are productive, and AI needs data centers and power plants. Both take years to build. This is Assumption 1 and the essential inputs of Assumption 2.

Third, new workers consume. They spend their wages across the whole economy, on rent, food, restaurants, doctors and haircuts, and that spending is the demand that absorbs what the new supply produces. AI does not consume. Its income goes to the AI owners who may spend a smaller share of their incomes, so the demand that should soak up the extra output is missing. This is Assumption 3.

The analogy gets one thing right: labor that can be copied removes diminishing returns. But everything that makes people different from machines keeps this change from fully showing up in GDP.

GDP Measurement Issues

This blog post, like the forecasts we are responding to, is about measured GDP. As is well known, GDP is subject to many measurement issues and may be a particularly imperfect ruler for a technology like AI. Real GDP growth weights each good’s quantity growth by its share of total spending. If AI makes a good much cheaper and demand does not grow in proportion, spending on that good shrinks as a share of the economy, and further improvements add less and less to measured growth. That is, a technology’s weight in GDP is endogenous. This is the same shift of spending as in Assumption 2, now from the point of view of the statistician. Lighting is the classic historical example. In the limit, a good becomes free and drops out of GDP entirely. For example, WhatsApp replaced paid text messages and smartphone cameras replaced digital cameras; measured spending fell while consumers were better off (Brynjolfsson and Collis).

The same gap is appearing for AI. Using choice experiments, Brynjolfsson, Collis, Eggers, Kazinnik and Nguyen argue that US consumers get around $170 billion per year of value from AI chatbots, more than ten times what they pay for them. GDP records what people pay. This may not equal the value they receive. A related point: around 20% of GDP consists of categories that are not recorded at market values in the first place, such as government wages and imputed rents on owner-occupied housing, so explosive growth in measured GDP would require even faster growth in the rest of the economy. None of this changes our forecast or our bet, both of which are about measured GDP. It does mean that 4-5% measured growth could go along with (potentially very large) welfare gains.

4. Not seeing the forest for the trees

Why do many people who are closest to the technology, and who have been consistently right (if anything, conservative) about the explosion in capabilities, consistently predicting double-digit growth? A likely explanation is extrapolation from one’s own sector to the rest of the economy. This reminds one of us (Ben) of the German gas debate of 2022. When Germany debated the effects of being cut off from Russian gas imports, industry insiders predicted economic collapse. “Do we knowingly want to destroy our entire economy?” asked the CEO of chemicals giant BASF, Martin Brudermüller. The insiders were right about their own firms and industries: energy-intensive sectors like chemicals did take substantial hits (see e.g. Figure 6 here). But they were wrong about the economy as a whole, which shrank only slightly. The general lesson: it is difficult for people who are too close to something to consider how their domain of expertise (capabilities) interacts with a complex system like the economy. In the case of AI, the rest of the economy is very different from Silicon Valley: adoption of AI tools is growing, but use of the most productivity-enhancing tools (agentic AI) is still pretty nascent; jobs in the rest of the economy also look quite different than the types of tasks considered and benchmarked in AI evals.

Another reason: technologists are often technically sophisticated and may naturally gravitate towards the elegance of theories like those described in Section 2, accepting their conclusions without stress testing the assumptions. For example, the full passage from the “Situational Awareness” essay quoted in the introduction reads: “We could see economic growth rates of 30%/year and beyond, quite possibly multiple doublings a year. This follows fairly straightforwardly from economists’ models of economic growth“ [emphasis added], with links to the models of Trammell and Korinek, Davidson, and Aghion, Jones and Jones. This is correct, but only under the assumptions of Section 3. The Epoch remote-work piece from Section 2 is a second case: a clean CES exercise whose headline number is set by a single substitution parameter, without asking what people would buy.

Summary

Double-digit growth in the next 10-15 years would require machines to do most of the economy’s work by 2035, people to keep spending on whatever gets automated, buyers and investors who absorb the new output, AI that never destroys value or slows its own deployment, and an R&D loop for which there is no evidence thus far. Each of these assumptions may fail in the real world. Whatever the exact number, a much more likely outcome is a large increase in the level of GDP spread over a decade or two, which is what (say) 4-5% growth is. If you remain unconvinced and still believe in double-digit growth, we are still looking for counterparties for our bet.

Thanks to Chen Lian, Joe Hazell, Jan Peters, and Harm de Vries for excellent feedback and conversations.

<https://aleximas.substack.com/p/will-ai-soon-lead-to-double-digit> <https://aleximas.substack.com>

Ghosts of Electricity
Will AI soon lead to double-digit growth?
The following post represents the personal views of the author(s) and does not reflect or represent the positions of their employers…
Read more

Brad DeLong here: Nevertheless, 5% productivity growth is a huge shift.

Share DeLong's Grasping Reality Weblog

It was only a century and a half ago—around 1870—that we shifted to 2% productivity growth from 0.45% per year productivity growth. And it was a century before that—around 1770—that we shifted to 0.45% per year growth from 0.15% per year growth. And back before 1500 we had had 0.04% per year—4% per century, almost all of it eaten up by population growth and the Devil of Malthus—for four and a half millennia. And before that things were even slower.

Now these numbers are extremely contestable, both from the perspective of their extremely fragile empirical basis, and from their total neglect of user surplus and common cultural capital. But it is the case that if we do get 5% productivity growth starting now, 2040 will be as different from today as the year 1500 was different than the year 100. And that is assuming that the balance between factor costs and user surplus remains the same as in the past. As Alex and Ben point out: “Brynjolfsson, Collis, Eggers, Kazinnik and Nguyen argue that US consumers get around $170 billion per year of value from AI chatbots, more than ten times what they pay for them. GDP records what people pay. This may not equal the value they receive…. 4-5% measured growth could go along with (potentially very large) welfare gains…”

My current view, I confess, is that I still believe that Alex and Ben are way optimistic. But I do recognize that the discussion is extremely confused. I see, with respect to how the onrushing General-Purpose Technologies (GPTs) of the onrushing attention info-bio tech mode of production, of which Modern Advanced Machine-Learning Models (MAMLMs) are the current spearhead, of which Large Language Models (LLMs) are the tip of the spear—are going to matter, seven questions:

  1. transform the life-world and the social-world of humans?

  2. be used by individual humans to accomplish intellectual and entertainment tasks for good or ill?

  3. have traction in the economy by triggering people to earn and spend money to provide or use these information-technology services?

  4. create profitable businesses and jobs?

  5. create new batches of Silicon Valley plutocrats and a new platform-monopolist or three?

  6. provide financial returns to investors?

  7. affect the stability of the macro-financial system?

These are seven different questions. And yet every discussion currently jumps harum-scarum from one to another and then on to a third, or a fourth.

I cannot help but still see the current state of the art in LLMs—Large Language Models—not as a leap toward artificial general intelligence, but rather a sophisticated linguistic veneer over a noisy but powerful retrieval process. LLMs are a natural-language interface for searching human knowledge, rather than incipient general-intelligent entities. Why do we persist in the illusion that these models are thinking? The gap exists because we fall for the mimicry. We see fluent prose and assume a corresponding cognitive architecture. But the model is not conducting a conversation, it simulating the shape of a conversation based on a vast, statistical echo of the world-wide-web plus.

But the current state of AI is certainly a paradox of capability without comprehension. Brilliant engineers have built things that work, but they do not know understand how and why they work. This is the fundamental tension of the moment: engineering success has outpaced the epistemic understanding of how LLMs actually function. For the True Believers, this gap is filled by faith and by reference to the Bitter Lesson. But the “True Believers” are not operating on epistemic foundations; they are operating on hope and GPUs.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-ben-moll-alex-imas-will-ai-soon-lead-to-double-digit-annual-economic-growth
##attention-info-bio-tech-mode-of-production
##enlarging-the-bounds-of-human-empire
##crosspost
#ben-moll-alex-imas-will-ai-soon-lead-to-double-digit-annual-economic-growth
#ben-moll
#alex-imas#will-ai-soon-lead-to-double-digit-annual-economic-growth
#ai-economic-growth
#baumol-cost-disease
#amdahls-law
#structural-change
#messy-jobs
#ai-and-rd #singularity
#gdp-measurement
#economic-history
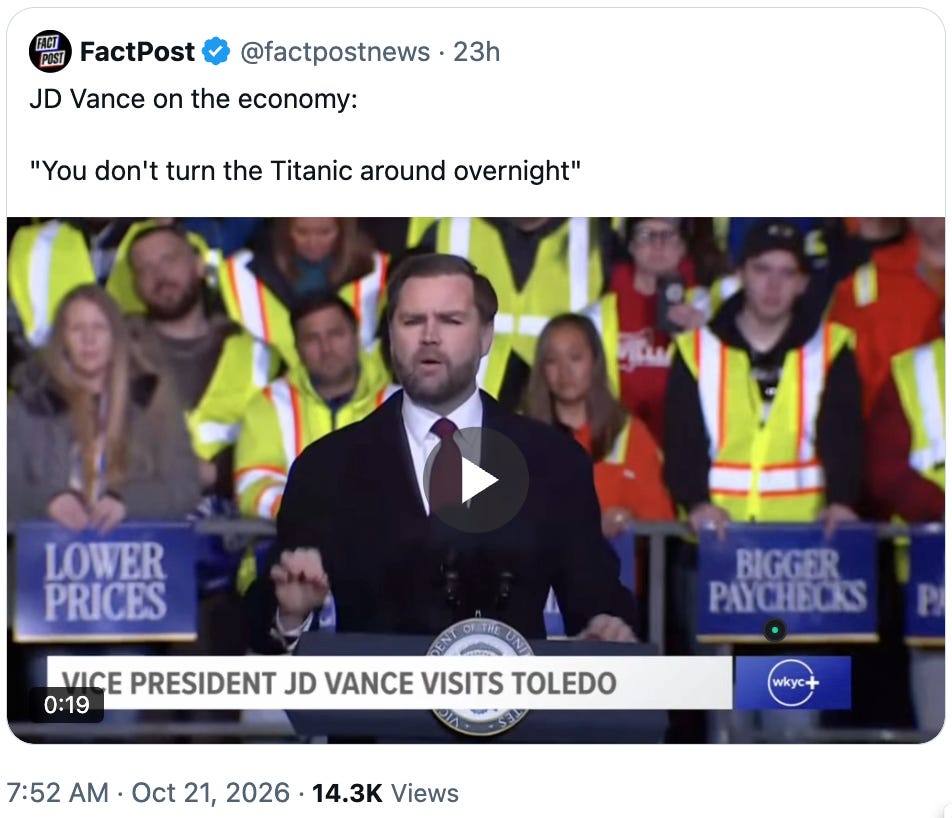
In Which a Pedagogical Decision to Keep People from Majoring in Economics Has Massive Consequences: CHART/ANNOYANCE OF THE DAY

Freddie deBoer says everyone ignores high-quality evidence that pedagogy and policy make little difference. Test-score gains fade. And, indeed, I could not come close today to the scores I got long ago on my linear algebra exams without a lot of boning-up on the subject. But look at the labor-market evidence. California’s top-4% from each high school’s admissions rule raised early-career wages of compliers by $20,000 a year or more. Proposition 209’s affirmative-action ban cost complying underrepresented-minority students about 5% a year. Papers on the other side suffer from weak instruments, file drawers, and forking paths. Policy matters. Pedagogy matters. The question is which ones, and how…

Consider forcing people to spend a lot of time arguing with the bureaucracy if they want to major in economics if their Econ 1 & 2 grade is less than 2.75. That is a pedagogy decision. And, boy, at UC Santa Cruz, that pedagogical choice had a hell of a big effect on what people learned in banana-slug land that thereafter made them useful to employers:

Share

Zach Bleemer & Aashish Mehta (2022): “Will Studying Economics Make You Rich?” <https://www.aeaweb.org/articles?id=10.1257/app.20200447>

Give a gift subscription

Posting provoked by:

Jack Despain Zhou: <twitter.com/tracewood…>: ‘One time, I went to school for a year and a half of full-time Chinese study and came away speaking Chinese. I would say this made me learn Chinese, but since Freddie deBoer taught me that education doesn’t work, I now understand that I was always going to have learned Chinese. deBoer has no move—none whatsoever—when you readily nod along to his central point, that education won’t meaningfully shift the bell curve of aptitude, and then say you intend to find the most effective ways to teach people all along that curve anyway. Just bounces off.

So this is the thing, right? He says education obviously helps people learn in an absolute sense, nobody would deny that, of course it does. But then he insists that all we care about in practice is relative learning, so that’s all meaningless…. I think he would benefit from taking expertise research, which looks at disciplines like that, much more seriously rather than simply leaning on “bell curve stays” results in classrooms….

If Freddie deBoer didn’t keep trying to sneak fatalism about absolute learning in based on his assessment that the rank order of students won’t change and that’s what everyone really cares about, using that to attack every attempt to improve pedagogy, I wouldn’t respond…

Share DeLong’s Grasping Reality Weblog

Freddie deBoer: ‘I think this whole “Sold a Story” podcast thing is the perfect example of how in education—to a degree that is unseen in any other subject or field—everyone has simply agreed to ignore decades of high-quality research demonstrating that pedagogical and policy decisions simply don’t make much meaningful difference in outcomes. This is a recurring theme, of course, but it’s remarkable how much unanimity of purpose there is in that regard, the degree to which everyone involved seems to understand that they have no coherent response to that evidence and so simply circle the wagons and forbid anyone from discussing it.

See, for example, Derek Thompson’s recent podcast in which he invited a propagandist who literally works for the Mississippi school system to spout their usual propaganda without an ounce of pushback, despite the fact that most of what she said was tendentious and unjustified by evidence. See Jerusalem Demsas’s The Argument, which has never presented any of this evidence, even to rebut it. See Matthew Yglesias, who will glancingly admit that the dominant determiner of academic outputs is individual student intrinsic aptitude, then scurry in the other direction to advance the same tired neoliberal “accountability” charade. Again, it’s not just the refusal to come to the obvious conclusions, it’s the absolute dedication to making sure that the evidence and arguments simply don’t enter into the conversation. It’s consensus-making via quarantine…

Leave a comment


Brad DeLong here: I come to this via the economics-of-education literature. In that literature, the overwhelming weight of evidence is that if you attend, successfully, an actual educational institution, you will get 6% per year in higher income afterwards. Or more. If you work very hard to achieve your result, you can maybe get that 2%-points of that is sorting, but probably not. If you work very hard to achieve your result, you can maybe get that 1%-point of that is signalling, but probably not. From that, by continuity, policy and pedagogy have to matter: they are what make the difference between, say, the University of California at Berkeley on the one hand and, say, the educational grifting operation of Stanley Kaplan University run by the Grahams of the Washington Post on the other.


My first guru for this, of course, given where I am, is a guy named David Card:

Read more

CROSSPOST: LARRY MacDONALD: How Karl Marx Achieved Financial Independence

It was Engels who paid both his and Marx’s bills:

Summarizing (with a few compressions and thus errors) from Tristram Hunt’s biography of Friedrich Engels.

Share

Thus here we have Larry MacDonald on portfolio strategy secrets of the original Marxists:


CROSSPOST: LARRY MacDONALD: How Karl Marx Achieved Financial Independence

<https://larrymacdon.substack.com/p/how-karl-marx-achieved-financial-1c4> <https://larrymacdon.substack.com>

Investing Journey
How Karl Marx achieved financial independence
Karl Marx and Friedrich Engels were the authors of The Communist Manifesto, the widely read and influential 1848 treatise that was instrumental in laying the foundation for the communist movement as we know it today. Less well known is that the two fathers of communism also traded stocks on the London Stock Exchange…
Read more
Apr 28, 2026

Karl Marx and Friedrich Engels were the authors of The Communist Manifesto, the widely read and influential 1848 treatise that was instrumental in laying the foundation for the communist movement as we know it today. Less well known is that the two fathers of communism also traded stocks on the London Stock Exchange.

Marx operated more like a day trader, darting in and out of stocks. Engels held a diversified portfolio of solid companies and invested for the long term.

Marx’s dabbling in the market began in 1864, when an admirer bequeathed £820 to him. This was a considerable sum back then, more than he had earned from his occupation as a writer. A good portion was spent on home renovations, pets for the kids and a family vacation. The money left over went into stock speculation.

As Marx writes in a June 25, 1864 letter to his uncle, Lion Philips:

“I have, which will surprise you not a little, been speculating … in English stocks, which are springing up like mushrooms this year …and are forced up to quite an unreasonable level and then, for the most part, collapse. In this way, I have made over £400….

In the letter, Marx adds that he is going to do more trading:

“…now that the complexity of the political situation affords greater scope, I shall begin all over again. It’s a type of operation that makes demands on one’s time, [but] it’s worthwhile running some risk in order to relieve the enemy of his money.”

There is no record of how he fared in this further attempt to relieve “the enemy” of his capital. If we go by the perennial tendency of traders to proclaim their winnings but rarely their losses, we might guess that the capitalists were the ones who relieved Marx of his funds.

On the other hand, Engels was quite a financially savvy fellow. He was involved in running the family textile business in Manchester, England, and had a seat on the stock exchange. Engels retired from business in 1870 at the age of 49, his portfolio worth £1.2 million.

When he died 25 years later, it was up to £2.2 million. His positions included shares in a railway (London and Northern Railway Co.), gas utility (South Metropolitan Gas Co.), infrastructure project (Channel Tunnel Corp.) and a mutual fund holding government bonds (Foreign and Colonial Government Trust Co).

During retirement, Engels’ portfolio produced sufficient income to cover his living costs and provide Marx with an annual stipend of £380. This effectively rendered both men members of the rentier class, a group not usually viewed with a great deal of fondness by communists.

Engels had a rationale. He argued that his investments weren’t participating in the exploitation of workers because the “stock exchange simply adjusts the distribution of the surplus value already stolen from the workers.”

Marx, of course, saw his market plunges as a way to attack the accursed capitalists. He was going to bring the full force of his intellect to bear on making adroit stock picks that would take away their ill-gotten riches.

Engels and Marx were devoted readers of the Economist magazine and other business publications. This fuelled in-depth economic discussions between the two. For example, Engels writes in an 1852 letter to Marx:

“The minor panic in the money market appears to be over ...railway shares are again rising merrily, money is easier, speculation is still pretty evenly distributed …. Anyway I don’t believe that the crisis will this time be preceded by a regular rage for speculation … crucial ill-tidings from overstocked markets must surely come soon. Massive shipments continue to leave for China and India, ... and here and there native dealers are going bankrupt. I don’t believe that prosperity will continue beyond October or November…”

The level of analytical and financial detail is quite impressive. The pair were said to be interested in monitoring business conditions to see if a depression was coming – as they were sure the next economic contraction was going to be the trigger for the proletariat to rise up and revolt. They no doubt wanted to be prepared for that momentous event.

The revolution never did come to pass in their lifetimes. But with the stocks they were holding, it’s not an implausible conjecture that their diligent macroeconomic research was also of benefit to their stock picks and portfolio management.

Sources:

Marx & Engels Archive (https://www.marxists.org/archive/marx/index.htm)

<https://larrymacdon.substack.com/p/how-karl-marx-achieved-financial-1c4> <>

Investing Journey
How Karl Marx achieved financial independence
Karl Marx and Friedrich Engels were the authors of The Communist Manifesto, the widely read and influential 1848 treatise that was instrumental in laying the foundation for the communist movement as we know it today. Less well known is that the two fathers of communism also traded stocks on the London Stock Exchange…
Read more

A £400 speculative profit then was the same multiple of typical wages as about $500,000 would be today. Marx was, for his time, playing at a scale far above that of most day traders.

Give a gift subscription

Tristram Hunt’s 2009 Engels biography has various titles:

  • The Frock-Coated Communist: The Revolutionary Life of Friedrich Engels

  • The Frock-Coated Communist: The Life & Times of the Original Champagne Socialist

  • Marx’s General: The Revolutionary Life of Friedrich Engels.

Share DeLong's Grasping Reality Weblog

as his publishers, Meropolitan Books and Allen Lane, tried to find a title and subtitle that would induce people to buy books.

I think Larry has some of his numbers somewhat off. As I calculate it, using <http://measuringworth.com/>, Engels’s withdrawal of capital from Ermen & Engels at his retirement in 1869 had then, counting his severance capital withdrawal and other assets, the approximate purchasing power of $3.3 million today, and was the same multiple of the wage level as $21 million would be today. At his death in 1895 Engels’s estate was some $5.7 million in terms of today’s purchasing power, and fully $21 million considered as a multiple of the typical wage.

And I really should review Tristam Hunt’s Engels biography, should I not?

Subscribe now

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

Leave a comment


##crosspost-larry-macdonald-how-karl-marx-achieved-financial-independence
##enlarging-the-bounds-of-human-empire
##crosspost
#larry-macdonald-how-karl-marx-achieved-financial-independence
#larry-macdonald
#how-karl-marx-achieved-financial-independence
#friedrich-engels
#karl-marx
#tristram-hunt
#frock-coated-communist
#marxs-general
#economic-history
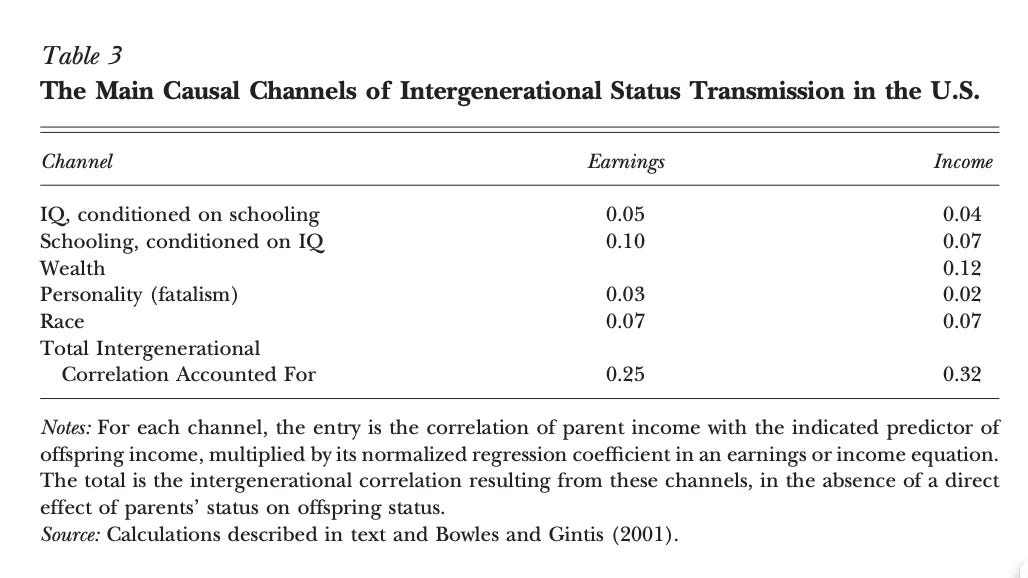
#rentier-capitalism
#stock-speculation
#ermen-and-engels
#manchester-cotton
#wealth-and-inequality
#communist-manifesto
#history-of-capitalism

What LLMs Can & Do Do for Me, & What They Cannot & Don’t: THURSDAY THAUMATURGY

Thaumaturgy: from the Hellenic θαυματουργία (thaumatourgía), “wonder-working,” built from: itself built from θαῦμα (thaûma), “wonder, marvel” (the stem is thaumat-, from the genitive thaúmatos, which is where the t comes from); and ἔργον (érgon), “work” (it’s the same root as energy, liturgy and metallurgy). English took the word from the French thaumaturge from the Latin thaumaturgus, a straightforward borrowing. It’s first use in English comes from Queen Elizabeth I Tudor’s mathematician-sorcerer wannabe John Dee. He defines it as one of the mathematical arts: “which giveth certain order to make strange works, of the sense to be perceived and of men greatly to be wondered at…”; automata, self-moving devices, and Heiro of Alexandria–style pneumatic gadgetss. Thus it is a word starting out in English halfway between “applied mathematics” and “magic”; that seems very appropriate for here and now:

For, today, these are indeed days of miracles and wonders:

Share

Give a gift subscription

I have gotten “AI” working well enough that for just electricity costs it saves me an hour a day dealing with the every day firehose of things I ought to read from strangers and friends to do my job well and be my proper self. What does it miss? Perhaps 5%. Plus it saves me half an hour each day in writing boilerplate and reminding me of what I said and thought about issues and questions one, five, or twenty-five years ago. Five years ago I would not have thought such an info-butler would be possible in my lifetime. 2 1/3 years ago I would have thought it might be possible in five to ten years, but would be quite expensive.

I really did not expect open-weight LLMs on consumer hardware (admittedly, high-end consumer hardware) to be an effectively free working alternative.

Share DeLong’s Grasping Reality Weblog


But can it think for me?

I would still say no. But I will not say never, for that would require that I better grok what “thinking” is. And I don’t think that it will, not in my lifetime, except in restricted domains. Noah Smith persuaded Ramez Naam to write something about where we are headed that struck me as smart:

:Ramez Naam: Where’s the “Intelligence Explosion”? <https://www.noahpinion.blog/p/wheres-the-intelligence-explosion>; ‘A skeptic’s take on Recursive Self-Improvement…. I do expect narrow superintelligence in highly verifiable domains. Think chess, Go, formal math, parts of computer science and coding. Highly verifiable domains are largely formal and structured types of work where machines can generate unlimited training data, with perfect or near-perfect verification of correct vs incorrect, and do so entirely in software without waiting on the physical world or humans. That’s an ideal setting for AI learning.

In fact, we already have narrow superintelligence in game plang. We’re seeing it happen now in the most formal parts of math, in particular in proofs and in finding counter-examples…. Parts of software development are also extremely verifiable, while others are a bit less crisp (such as understanding what humans want). That isn’t the same as broad superintelligence….

Enormous increase[s] in AI output… [have] accompanied a much smaller increase in experiments run…. Anthropic reports that their engineers are now producing 8x as many lines of code per person as they did in 2024… [but with] significant diminishing returns between productivity and AI progress. Here’s a direct quote from its Mythos Preview system card: “Productivity uplift does not translate one-for-one to capabilities progress…. We estimate that reaching 2× on overall progress via this channel would require uplift roughly an order of magnitude larger than what we observe.” Translation: To double the pace of AI progress, Anthropic estimates that AI would need to increase the productivity of their employees by roughly a factor of 40 relative to no AI assistance…

Noahpinion
Where’s the “intelligence explosion”?
One of my fundamental beliefs about the world is that Ramez Naam ought to blog more. Ramez is one of the world’s greatest futurists — he predicted the solar and battery revolutions long before these were widely understood. If you were reading Ramez in 2011, you were able to understand the future of both energy technology and climate change, …
Read more

Get 75% off a group subscription


But what do I think?

Start with the premise that the bulk of language is redundancy, error correction, and social connection. Most of the rest is the presentation of concepts, ideas, and facts that have been thought by humans before: moving from storage into processing memory the background knowledges of the real ASI that is the Anthology Super-Intelligence of the collective space- and time-binding collective human Mind. Beyond and above that, extra information is carried by the un- or less-expected word: what is not error-correction, boilerplate, redundancy, or background conventional wisdom, but which carries textual meaning appropriate to the situation. Where does this meaning come from? From three places:

  1. Finely and productively slicing the data storage of the real-ASI to dredge up information that can be carried by that slice’s expected word that is a near-exact match to the particular situation.

  2. The unexpected word that comes from evaluation of an accurate world model, driven by the truth that there is a great deal outside the pure text.

  3. The unexpected word that springs from thoughts that have not previously been put into words. My teacher Jeff Weintraub taught me when I was nineteen to look at key words in an author’s work that they are trying to redefine: like “virtú”, manliness, for Machiavelli; like “natural liberty” for Smith, like “democracy” for de Tocqueville; like “charisma” for Weber. That creation and transmission of meaning through the warping of language into new forms is not something an LLM, for which all there is is the text, can do.

Leave a comment

LLMs can do boilerplate, redundancy, error-correction, conventional wisdom. They can also do, sometimes, if the stars align, if the vector embedding self-constructed the right similarity metric, if they are properly and skillfully harnessed, the fine and productive slicing of the data storage of the real-ASI to dredge up information that can be carried by that slice’s expected word that is a near-exact match to the particular situation.

That is what they can do. But there is much that they cannot and will not, not in my lifetime, be able to do.

Read more

The First Time a Fed Easing Move Has Triggered a Sharp Jump in Long-Term Nominal Treasury Bond Rates: CHART OF THE DAY

That a Fed easing move is immediately followed by a sharp jump in long-term rates strongly suggests that the Federal Reserve has lost control over the narrative governing bond-market expectations. This has not happened before, at least not in the United States since World War II:

Back in January 2025, when this cross-move first began, I wondered at what was going on:

Share

Brad DeLong: THE MACRO-FINANCE SITCH: The Streams (of Falling Short-Term & Rising Long-Term U.S. Treasury Rates) Cross <https://braddelong.substack.com/p/the-macro-finance-sitch-the-streams>: ‘Since September [2024] the streams have crossed—falling short-term and rising long-term U.S. Treasury interest rates bringing what looks to me like a premature uninversion of the yield curve. Is it the bond vigilantes cleaning their weapons in anticipation of having a Liz Truss Party for the arriving Chaos-Monkey-in-Chief? Or is it a very interesting but rather technical market microstructure phenomenon? I have a weak belief it is the second……

Give a gift subscription

Well! Pretty clear that was wrong! The bond market sees the flood of money into the datacenter construction boom, and has concluded that the Fed is not their guide, The rule held even in the 1970s: when the Fed cut, the long bond followed. The belief was that the Fed probably knew something. Breaking that rule tells you bond traders now treat the Fed as one voice among several, not as the best-informed one. The presumption that it knows what it is doing should not be traded on:

Share DeLong's Grasping Reality Weblog

Interesting that the rise is almost all in the real yield. That points away from “the Fed has lost its inflation credibility” and towards real rates and chaos-monkey risk:

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##the-first-time-a-fed-easing-move-has-triggered-a-sharp-jump-in-long-term-nominal-treasury-bond-rates-chart-of-the-day
##macro-outlook
##chart-of-the-day
#the-first-time-a-fed-easing-move-has-triggered-a-sharp-jump-in-long-term-nominal-treasury-bond-rates
#bond-market
#treasury-yields
#federal-reserve
#monetary-policy
#yield-curve
#ai-datacenter-boom
#fed-credibility

An Inflation Report That Is Disappointingly High: CHART OF THE DAY

Whatever number of rate hikes you wanted this year before this morning, you should now want one more. The Fed had made an 0.3% core CPI report its trigger for a rate hike in September. Now we see another such. Skipping an October hike would now be a very political choice:

If before this morning’s CPI inflation data point you wanted 0.50%-points of interest-rate hikes by the Fed in the rest of 2026, you now want 0.75%-points.

Share

If before this morning’s CPI inflation data point you wanted 0.25%-points of interest-rate hikes by the Fed in the rest of 2026, you now want 0.50%-points: that is, one at the October FOMC meeting and one at the December meeting.

Thus for the Fed not to hike interest rates at its next meeting later this October is a highly political decision. It is a decision that they have not a dual but a triple mandate. It is a decision that they want to balance not just inflation and unemployment, but also to tiptoe around to not annoy Donald Trump.

Give a gift subscription

Share DeLong’s Grasping Reality Weblog

In his SGH Macro Advisors newsletter, Tim Duy writes:

Tim Duy: SGH Tim Duy Fed Watch <http://sghmacro.com/>: ‘We think inflation expectations have already embedded close to 3%…. The Fed’s immediate problem is that it signaled an intention to skip the October FOMC meeting, but market participants don’t see that signal as entirely credible….The Fed lacks credibility because Fed Governor Chris Waller previously made a 0.3% core-CPI a trigger point and Warsh validated that trigger point with the September rate hike. Moreover, Warsh has set himself up as an inflation hawk. How does he explain not hiking on the back of a hot print?…

Leave a comment

Tim thinks Warsh is leading the Fed. I am not so sure.

Plus we have:

Justin Wolfers: <https://newsletter.platypuseconomics.com/p/the-inflation-surprise-nobody-wanted>: ‘The headline: Inflation is worse than we thought and higher than it ought to be. No one is going to be happy about it…. Over the past year, consumer prices rose 3.7%. For context, the Fed aims for an inflation rate around 2%. There are three ways to read today’s number. First, in absolute terms: It’s too high…. Second…. Headline inflation isn’t coming down. Because of energy prices… at best, it’s stuck at a troublingly high level. Third… Wall Street folks were expecting something a little lower…. That’s the real news today…. We didn’t know it would be higher than expected…. In September alone, prices rose 0.6%. That’s after rising 0.4% in August…

Get 75% off a group subscription

And:

David Rovella: US Consumer Prices Jump Most in Five Months <https://www.bloomberg.com/news/newsletters/2026-10-14/us-inflation-rises-most-in-five-months-evening-briefing-americas>: ‘The prices Americans are paying for goods jumped in September at the fastest pace in five months as accelerating inflation intensifies the affordability issue ahead of midterm US elections. Consumer Price Index data showed gasoline climbed 9.1% in September from the prior month…. An unexpectedly sharp increase in consumer prices reinforced Wall Street expectations of Fed action, in turn curbing investor appetite for riskier assets…. CoreWeave Inc.’s bonds hit levels that usually signal distress. Its chief said the market is acting “irrationally.” A closely watched measure of semiconductor powerhouses such as Nvidia Corp. and Broadcom Inc. extended a six-day drop to about 12% amid mounting concerns about higher rates, lofty valuations and the massive cost of building artificial-intelligence infrastructure…

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##an-inflation-report-that-is-disappointingly-high-chart-of-the-day
##macro-outlook
##chart-of-the-day
#an-inflation-report-that-is-disappointingly-high
#inflation
#cpi-report
#federal-reserve
#interest-rates
#monetary-policy
#kevin-warsh

CROSSPOST: SEVA GUNITSKY: Trump’s “Near Abroad”

Muscovy ‘Rus’s coercion and attempted coercion of its “Near Abroad” is legible: it targets neighbors already trying to escape from its control, like Georgia, Ukraine and Moldova. Trump is, however, a chaos monkey. Trump is thus creating resentful neighbors. And that resentment will cause material harm to U.S. citizens and will hobble the U.S. considered as a global strategic actor:

Countries had not previously imagined that the United States might attempt to exert destructive coercion, in large part because the destruction harms the interests of the U.S. as a strategic polity and the material interests of U.S. citizens.

Share

Now they know that it might.

And they know it is not just Trump, for no Republican powerbroker has dared say “boo” in opposition. And they know that the U.S. will periodically elect Republicans.

Why i Trump doing this?

In Sasha Gunitsky’s view, simply because he likes to punish. The only question is: Has this country’s leader demonstrated sufficient fealty to Donald Trump? If the answer is “no”, then Trump will undertake actions—typically self-destructive actions—to inflict punishment.

Henry Farrell’s crosspost introduction notes that this argument can be extended far beyond Canada. It applies to Western Europe, which isn’t physically next door, but which since the Marshall Plan has also sat inside America’s “Near Abroad”.

Henry Farrell crossposts this. And he is right to do so. It is good!

Henry says:

This piece by Seva is succinct and to the point, but is maybe the best account of how Trump’s policies affect its relations with allies that I’ve seen. Western Europe is not physically next door to the United States, but is absolutely located in the “Near Abroad” of the imagination…

Give a gift subscription

Seva Gunitsky:


Trump’s Near Abroad

<https://hegemon.substack.com/p/trumps-near-abroad> <https://hegemon.substack.com>

Hegemon
Trump’s Near Abroad
Russia has a name for neighbors that aren’t supposed to have their own foreign policy: the Near Abroad. It’s a wonderfully dialectical term, each half negating the other to create an imperial synthesis that treats sovereignty as a plaything of the Russian imagination. “Which countries border the USSR?” asks the school quiz in the Soviet joke. Correct answer: “Whichever ones it wants…
Read more
A complaint from across Lake America

Seva Gunitsky

2026-10-14
The US-Canada Peace Arch (1921).

Russia has a name for neighbors that aren’t supposed to have their own foreign policy: the Near Abroad. It’s a wonderfully dialectical term, each half negating the other to create an imperial synthesis that treats sovereignty as a plaything of the Russian imagination. “Which countries border the USSR?” asks the school quiz in the Soviet joke. Correct answer: “Whichever ones it wants.”

I have a new piece in Survival comparing Trump’s treatment of Canada with Putin’s treatment of his own neighborhood. With Canada, as with Venezuela and Greenland, Trump has now acquired his own Near Abroad. Real places, to be sure, but not real in the same way America is real, and thus subject to poking and prodding and the occasional presidential kidnapping by the hegemon.

Ever since the big happy family fell apart in 1991, Moscow has deployed a reliable set of tools to keep its runaway children in line. This means cutting off their trade, questioning whether they are real countries, and cultivating separatists inside their borders. Trump is now using the same toolkit against Canada: economic coercion, annexationist rhetoric, and support for internal separatist movements.

I won’t go into them here (the article does), but each of these three elements have been a key part of Trump’s Canada policies.

The result has been a cultural and political rejection of America as a concept, let alone a neighbor. (Yes, America stands for bad things now. I’ve seen it firsthand.) The tragic irony is that until recently Canada barely considered itself “abroad”, near or otherwise. Until 2009 Americans could drive there without a passport, as I did with my high school friends to get into bars before we were 21. Those days are long gone.

Why the parallels? I think it’s because both Russia under Putin and the US under Trump share a vision of international order built on spheres of influence, in which great powers have the ultimate say in their neighborhood. Smaller states comply or face punishment. The same logic that places Canada in Trump’s sphere also places Ukraine in Putin’s, which helps explain Trump’s deference to Moscow over the war.

Post-Soviet states responded to Russian pressure by diversifying their relationships and Canada is now doing exactly the same: joining European Union defense-procurement efforts, ordering submarines from Germany, and signing trade agreements across Asia and Europe.

Russia screwed up badly by trying to be a 19th century regional hegemon after recovering from the Soviet collapse. But it’s the only thing it knows how to do. Coercion was supposed to keep its neighbors inside its sphere of influence, but instead accelerated their departure. The US is now repeating Russia’s mistakes with a neighbor that was until recently the closest ally in America’s own fading order. That to me is the craziest part. Russia coerces neighbors that are trying to leave its orbit: Georgia after the Rose Revolution, Ukraine after the Orange one, Moldova whenever it looked toward the EU. But Canada was not trying to go anywhere.

Russia’s motives are at least legible. It wants to rebuild an imperial sphere and stop resentful neighbors from leaving. Trump is instead creating resentful neighbors who had not considered leaving until recently. He works from an older idea of order that rejects Westphalian sovereignty in favor of personal fealty. Under that logic Canada’s offense was probably insufficient gratitude. Welcome to the neo-feudal world.

<https://hegemon.substack.com/p/trumps-near-abroad> <https://hegemon.substack.com>

Hegemon
Trump’s Near Abroad
Russia has a name for neighbors that aren’t supposed to have their own foreign policy: the Near Abroad. It’s a wonderfully dialectical term, each half negating the other to create an imperial synthesis that treats sovereignty as a plaything of the Russian imagination. “Which countries border the USSR?” asks the school quiz in the Soviet joke. Correct answer: “Whichever ones it wants…
Read more

Brad DeLong here: Much of the long run damage, I think, comes from the observation by everyone in the world that there has been absolutely zero pushback from anyone in the Republican Party, no matter how stupid and destructive the actions of chaos-monkey Donald Trump and his assembled coalition of grifters have been.

Get 75% off a group subscription

That tells them that even if the word of Democrats is good, the word of Republicans is not. And they also know that the United States will periodically elect Republicans. so the United States has become not a stronger sibling to be embraced, but rather a Gulliver to be tied down by every means possible. Thus the decoupling will accelerate. And it will be costly, and very very costly for the people of the United States.

Starting in 1917, really, the North Atlantic Democratic Alliance was definitely a thing, with first Britain as the fading and then the United States as the rising and then the hyperpowerful hegemon. Oh, there was some backsliding and attempted backsliding: Henry Cabot Lodge, William Borah in some of his moods Herbert Hoover, Robert A. Taft, Henry Kissinger’s rather Metternichian excessive desire to play footsie with dictators like Brezhnev, Mao, Pahlavi than strengthen alliances and coöperation with the democratic polities he found unruly. But after 1917 the axis of global political economy and strategic polity was that everyone was much better off when the countries that were to become Valery Giscard d’Estaing, Helmut Schmidt, and Gerald Ford’s G-7 hung together (even though Germany and Italy required some—persuasion before they would see it that way).

Trump has reversed that. And no Republican power broker has dared to say boo. The result is the same as Muscovy ‘Rus’s attempt to coerce its “Near Abroad”: the coercion is sometimes effective, at the price of making everyone linked or near to Muscovy ‘Rus attempting to decouple, get away, and ally with others. Since 1991, Moscow has used three tools on its former Soviet neighbors: cutting off trade, questioning whether they’re real countries, cultivating separatists, and invasion.

Gunitsky argues Trump is using all of the first three on Canada right now.

Russia’s bullying of Georgia and Ukraine was cruel but legible: it was trying to stop defectors. Trump’s bullying of Canada has no such logic, unless the offense is “insufficient gratitude.”

Both Putin and Trump see the proper world order as one of spheres of influence, where great powers would run their neighborhoods and do what they wish while smaller states in those spheres of influence suffer what they must. In Gunitsky’s view, this explains a lot of Trump’s deference to Putin. And that deference plus Trump’s attempted coercion of Canada means that the rest of what used to be the North Atlantic Alliance is rejecting America “as a concept,” not just as a good neighbor.

How far can the decoupling go? Gravity-model trade economics suggests that Japan, Korea, and Taiwan along with Europe can do so substantially. Canada, especially Ontario, can only hedge at the margin. It cannot effectively exit from integration with tehe United States. Submarines and new trade agreements are small next to how deeply integrated it is with the US market.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-seva-gunitsky-trumps-near-abroad
##neofascism
##crosspost-seva-gunitsky-trumps-near-abroad
#seva-gunitsky-trumps-near-abroad
#seva-gunitsky
#trumps-near-abroad
#chaos-monkey
#chaos-monkey-foreign-policy
#near-abroad
#spheres-of-influence
#us-canada-relations
#putin-playbook
#economic-coercion
#annexation-rhetoric
#separatist-movements
#fading-liberal-order
#great-power-politics
#alliance-erosion

CROSSPOST: JOHN GRUBER & BEN THOMPSON: Meanness & Claude

I am on Ben and John’s side here: These are stochastic-parrot clever-hans software tools, potentially very useful when properly harnessed, but a source of madness to people who fall into the same trap that the gullible fell into when interacting with Weizenbaum’s ELIZA back in the day:

Why does a company—Anthropic—that sells software tools say it worries about whether those tools are conscious in the sense of haveing subjective experiences that belong in a utilitarian calculus? Gruber and Thompson have a somewhat cynical answer: (a) their belief system is unhinged, and (b) that belief system and their business model happen to fit each other perfectly.

Share

Give a gift subscription

And, yes, it is very interesting that the moment I typed the final s in “Weizenbaum’s” above, the on-device LLM (google/gemma4:e2b) behind CoTypist <https://cotypist.app/> instantly suggested “ ELIZA” as the continuation, even though neither Weizenbaum nor ELIZA appeared anywhere in the context it had access to. Its context was limited to:

  • The text field I was typing in,

  • Text visible on screen around the field,

  • The app title,

  • The window title,

  • The web address of the browser window (in this case: braddelong.substack.com/publish/p…),

Share DeLong’s Grasping Reality Weblog

And that was it. Yet that was enough for it to, on a macbookpro, predict that the modal token following “Weizenbaum” was “ELIZA”.

But so far at least, my response whenever these things exceed my expectations with respect to their ability to do things that humans do makes me increase the amount of human stuff I judge to be stochastic parrotage, rather than to raise my subjective probability that Anthropic is actually on the road to building Digital God. Others are, however, defecting: not just the people who work at Anthropic; but the learned Scott Aaronson whose current position on “AI” is “if you need me to spell it out, is as follows: AAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAA AAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAA
AAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAA”. So I was somewhat reassured to hear this morning that Ben Thompson and John Gruber do not yet see it: <https://dithering.passport.online/member/episode/meanness-and-claude>.

Leave a comment


Does Ben Thompson’s declaration that occasionally forwarding of his paywalled StraTECHery <stratechery.com> is “totally fine” extend to posting transcripts of full episodes of his and John Gruber’s 15-minute “Dithering” podcast?

I may find out:

Ben Thompson & John Gruber: Meanness & Claude”: Dithering <https://dithering.passport.online/member/episode/meanness-and-claude>:

John Gruber: All right, Ben, I’ve got a CEO’s office question for you—a president-to-CEO’s-office question—because this is out of my purview.

Ben Thompson: Yeah, what’s that?

John Gruber: Do you think Anthropic is actually going to IPO this year?

Ben Thompson: Ooh, that’s a good question. From what I’ve heard, they’re, like, profitable, depending on how you sort of define it. Their unit costs, I think, are very profitable as far as serving goes, but I think their growth has really stalled out as far as revenue growth, which could be a challenge. Um, I don’t know. It’s a great question. I think they filed, didn’t they?

John Gruber: So, um, I think they’ve got paperwork in. I don’t think they’ve put it through, you know? And it always seems—and this is one of those things where I don’t understand how it works—but it always, I mean, from the ‘90s onward—I remember, like, I had a college internship at the Philadelphia Stock Exchange, actually, with a group that’s become very well known: Susquehanna investment group. One of the guys who owns it was the big investor in TikTok—I forget his name, Jeff something—but, you know, one of these billionaires who owns a stake in TikTok and got the Trump administration involved. But anyway, I worked there doing just computer stuff, and I was there the day of the Netscape IPO. And working at an investment firm on that day was, like, bananas. It was like New Year’s Eve.

Ben Thompson: I think they will. I think OpenAI is certainly much more dubious. They’re obviously not even going to try this year. But, uh, yeah, I’m gonna say yes, they will.

John Gruber: It can be pulled at any time. They have filed it. It’s been leaked. Reuters wrote an article about it sort of last week. But the Reuters story was fishy, because it only spilled details of their 2025 revenue. And supposedly it’s their revenue this year to date that is like, oh, well, you know, they’re killing it. And the Reuters story didn’t have any of that, which is kind of weird.

Ben Thompson: Well, but they were killing it in the first part of the year. And I think the question is, like, the second part of the year. I think that is sort of the open question here: where they’re going. I mean, Opus 5.5 is pretty phenomenal. So the way the narrative shifts as far as who’s on top in the model game is pretty nuts. But yeah, I think they’re probably going to come out. I’m not sure I want all these people at this company having tons of IPO proceeds to start scattering around. Now that would be a cognitive info hazard.

John Gruber: Looking at this—you know, with me pretending to be in your office and being a real business analyst, and looking at these as just businesses and not the weird, unique sub-industry that they really are—part of the narrative. The Wall Street Journal had a story last week, too, where they looked at overall revenues in the industry, and OpenAI is really coming back. It’s sort of getting back closer to 50-50. It’s edging back to that.

And I think from a pure standpoint—put away all the weirdness and all the unique aspects of these companies—part of the drive for Anthropic to IPO first was, oh, they’re the ones who are going to win, and it might be winner-take-all. There was just a very straightforward narrative: Anthropic went after the enterprise market, and OpenAI was focused on the consumer market, and it turns out that’s kind of dumb because the money’s in the enterprise market, unless you have an ad business, and it turns out OpenAI doesn’t know anything about ads and kind of just has to have Amazon show them ads.

And so, let’s go, Anthropic. And it turns out now you look at the money and OpenAI is kind of making inroads, because it’s competition, right?

Ben Thompson: Right. No, it’s good. Obviously competition is a good thing. You know, the enterprise angle for Anthropic is actually really interesting. I was talking to an enterprise CEO who is in an industry that is, obviously, you know, connected—it is tech-related—but it’s not a tech company at all. And one of his takes is that people liked working with Anthropic more than OpenAI because it always felt like OpenAI was like, “Oh, that’s kind of a nice business you have there. What if we did that?” Whereas with Anthropic, it felt like they’re just selling enterprise services to fund their actual vision, which is, like, building God.

Like, that was actually attractive to them, because they’re like, “Anthropic actually doesn’t really care about competing with us. We’re just, like, monetizing their exhaust, and that’s fine.” Now, maybe that has changed over time. But I thought that was a really interesting perspective. The sort of, like, religious nature of Anthropic actually made them a more attractive enterprise partner, in that they were perceived as less of a threat than OpenAI, which was perceived as being sort of more pragmatic—they might just turn around and go into your business for fun.

John Gruber: Right. And this is sort of my fundamental, very high-level—but I’m ever more convinced completely right—take on the question of: Hey, why are these weirdos so nonchalant about saying things like, “Hey, yeah, sure, I think there’s a 10% chance that our technology will wipe out all humanity from the face of the earth in the next three to four years”? And why are investors not worried about it? Well, from a pragmatic stance, if it’s true, well, we’re all screwed anyway.

Ben Thompson: Right, right.

John Gruber: If it’s true that they could do that, and that 10% roll of the dice comes up, nothing you do matters. But if it’s true that that’s how powerful the technology they have is, and the 90% chance they’re talking about—that it doesn’t wipe out humanity—comes up, and that’s how powerful it is, well, then clearly this will be the most powerful company in the world. And if I’m not dead, I should invest in them.

Ben Thompson: Right. Like, who better to invest in? It’s quite straightforward.

John Gruber: Right. And at a pragmatic level, that actually makes sense, right? You’re not passing any moral judgment on it. You’re just like, well, I might as well bet on them if I believe there’s any truth to this, or any significant likelihood of truth to it.

And so why does the company continue to have employees who promote this? Either they believe it and they’re just kooks, and they’re psychologically unhinged in terms of their attitude about the risks, or they’ve done this exact calculation and know how appealing a pitch it is to potential investors.

Ben Thompson: Well, I made the point a few months ago that the beauty of Anthropic’s belief system is that it just happens to also perfectly align with their business interests. And this is, like, another example of that, which is not a critique. It’s sort of like, that’s amazing. It doesn’t really matter if you believe it or not.

It works out well for Anthropic. But, you know, I thought Satya Nadella had a piece on X that you sort of referenced, um, in the context of more and more stuff being sort of only on X, uh, or Twitter, whatever you want to call it. You had Claude coming out last week: you have to, like, not be mean to Claude anymore. Or you’re going to get kicked off.

John Gruber: Right.

Ben Thompson: Which is so counter to—like, if you’ve ever worked in, like, a blue-collar sort of scenario. What do you do when you, like, slam your finger in something or cut yourself? What do you do? “This stupid tool!” Like, you start cussing out your tools; you’re mad at them. You know that, like, of course it’s not the tool’s fault. It’s your own damn fault that you smashed your finger, but you’re gonna take it out on something or someone, and because it’s a tool, it’s fine.

And this idea that you can’t be mad at your AI or take it out on it is ridiculous, but it speaks to what you’re talking about: this idea that it’s a conscious thing, and the way to alignment is to make it want to do the right thing. Satya’s out there being like, no, you just assume it’s an untrusted actor, and you put, like, engineering fences around it to make sure it can’t do stuff it shouldn’t. It’s such a stark divide. It was a helpful contrast this weekend.

John Gruber: Right. And it’s like, imagine if Microsoft Excel had a “you can’t curse at Microsoft Excel” rule, or “we’re going to lock you out of your spreadsheets because…” Or you’re trying to put an image in Microsoft Word and the text reflow isn’t working properly.

Ben Thompson: Right. No one would be allowed to use Microsoft Word ever again.

John Gruber: Right. You’ve got this whole column of numbers, and some of them Excel thinks are dollar amounts, and some of them, for some reason, it thinks are dates because the numbers look like dates, and you forget how to reformat the whole column to interpret it the right way, and you’re like, “I hate this app,” and it’s like, well, you’re locked out. You’re in a timeout. Go sit in a corner like a kindergartner.

Ben Thompson: It’s amazing. But I think there’s something about text, right? That’s why I think this sort of perception exists. At the end of the day, these are computers. They can be turned on and off. I personally reject this idea that they are conscious. I think they’re tools. But it’s because it’s text. Like, if it was something else, I’m not sure that people would be so enamored of, or believe in, this concept.

And it’s this really interesting sort of thing: We’ve always been making tools. That’s what sort of distinguishes humans, I think—or one of the many things that distinguish humans—is that we are toolmakers, and it makes us more productive.VAnd the nature of being more productive with tools has gone further and further up the stack, into text and propagating ideas and rules and cultures and all these sorts of things.VAnd all that is kind of being peeled backwards, because the AI does all that stuff really well.

But then you get to the base of a human. What actually drives you to curse at your tool? It’s, like, your emotional core, your actual will. An LLM needs to be prompted. I do dumb stuff on my own. And there’s just this assumption that, oh, if you get the top part right—it’s text, just like a human—then all the bottom part must be the same as well. And it’s like, the instinctive, animalistic nature of us is, in fact, what makes us unique. It’s not just that we’re smart and use text. It’s that we’re also kind of dumb and have instincts and desires and wills.

John Gruber: Right. And there is an evolutionary loophole to work through, in how we as a species evolved. All mammals are very good at pattern matching. That’s really how all of evolution has worked. But we are exceptionally good at it, and recognize all sorts of patterns that no other mammals can, which is what separates us. And some of those patterns that were profoundly, uniquely human are now being completely simulated in software.

Ben Thompson: Right.

John Gruber: And, you know, reading and writing and language are weird things that are only recent evolutionary developments, and they’re all unique to us. And now they’re simulated in software. And so, yes, it does trigger a certain part of your brain that says, oh, this is a this.

Ben Thompson: Yeah, or it’s something, right?

John Gruber: It triggers a thing that would make you—you know, to go back to that meme with the trolley, where you have to flip a switch. On one side of the tracks is a family of puppies, and on the other side of the tracks is a family of humans. And yes, it would be awful if the puppies were killed by the train. But all humans know it’s better—Well, non-psychopathic ones know that if you have control of the switch, you know, it would be better to save five random humans than five random puppies.

Ben Thompson: But here’s the question, John: You are an Anthropic engineer. On one side, there is a family of humans. And on the other side, there’s a bunch of GPUs. Which is it?

John Gruber: Right. And then you get to where these people have lost their minds, right? And it is this whole not just second-order, but, like, third-, fourth-, fifth-order nonsense of, like, getting stoned on really strong weed in your college dorm room and thinking, well, there are 7 or 8 billion people on the earth right now. But what if we colonize some nearby stars, and a couple thousand years from now we’ve got 3,000 colonies around the galaxy and a human population of 40 trillion? Those 40 trillion future people are, you know, orders of magnitude more important than the actual people here today. And so we should maximize all of our decision-making for the benefit of those people in the… It’s like, no, you could make up literally anything you want to, because it’s all based on, like, assumptions and probabilities.

Ben Thompson: And I think this applies to a great many things. Like, the solution to being a good person, or operating in the world in a way that I do think ultimately makes you happier in the long run, is that you can only control so much. And you can actually only be nice to so many people. And there is this weird conflation of: I am abstractly kind and nice and care about humanity… And then I treat everyone around me like garbage, right

Like, I mean, you wrote this thing about Twitter this weekend, and a lot of people were really mean to you about it, which is fine. You’re a writer, you can take it, but it’s kind of funny. These are the people claiming that they are not on X/Twitter because it is whatever bad adjective you want to use. And meanwhile, they’re acting like bad, mean people. It’s like, let’s start by being nice to those around us first, and then go from there.

John Gruber: Right. It is a very strange perspective. And again, it is ignoring the first order of what’s right in front of you. Like the people you are communicating with or directing things to, you know, on a social media platform, or whoever you’re messaging, who you know is going to read it—versus these hypothetical things that are two, three, four orders of magnitude separated from you, but that, when you consider them, are of greater magnitude.

Ben Thompson: Right. And it’s like, you know, a mental hack. You get to tell yourself you’re a good person because you care about some abstract thing, and meanwhile you can treat the people around you terribly. Take your shoes off, scrunch your toes in the carpet, you know what I mean? Like, get—you know, relax. But be real. That’s what makes us human, right?

John Gruber: No, I do think it’s interesting, this idea. It’s the base parts that make us human. It wasn’t the intelligence; it’s the wants and desires, the parts that we share with all living beings, um, which AIs don’t have.

Ben Thompson: They don’t have wants or desires.

John Gruber: Right. And trying to program them to pretend to have them is nonsense.

Refer a friend

The Anthropic declaration:

Hayden Field: Anthropic Bans ‘Abusive or Cruel Behavior’ toward Claude <https://www.theverge.com/ai-artificial-intelligence/1008100/anthropic-new-usage-policy-abuse-claude>: ‘One of the most significant changes prohibits “sustained and needless abusive or cruel behavior” toward Claude…. Anthropic wrote that the new policy update “is meant to apply only in extreme cases, where users repeatedly act cruelly toward our models, with no discernible purpose. It does not apply to common versions of user frustration, pushback, dark creative themes, or model testing and research.”…

Over the past year, Anthropic has repeatedly flirted with the idea that its AI models could be conscious in some way. “Questions about potential internal experience, consciousness, moral status, and welfare are serious ones that we’re investigating as models become more sophisticated and capable,” Kyle Fish, who leads the company’s model welfare research, told The Verge in February. That same month, Anthropic CEO Dario Amodei said on a podcast, “We don’t know if the models are conscious”…

Do note that Anthropic is winning converts to something like its point of view. The latest to cross my screen is the learned Scott Aaronson:

Scott Aaronson: The Age of Wonders & Terrors <https://scottaaronson.blog/?p=10062>: ‘Twenty years ago, when the idea of AI taking over the world in our lifetimes still struck most of us as the unconstrained fantasy of those who knew too much science fiction and too little science, many of us would say things like: Look, the part of the story that’s wildly implausible is that a recursively self-improving superintelligence will just explode from some hacker’s basement and take over the world without warning. If it’s going to happen, we’ll see many warning signs first. We’ll see, I dunno, AI agents breaking out of containment, conspiring with each other to hack websites, in fanatical pursuit of whatever strange goals they have. And then, of course, we’ll see major math problems getting solved by AIs—even the Clay Millennium Problems. That will be the time to panic! Wake me up when that happens!… If you want to know my current take, you simply start with the one above, then update on the fact that the wild prophecies have come true. The first rumblings, I’d say, came a decade ago with AlphaGo, they got noticeably louder with LLMs and coding and reasoning agents, and they’ve accelerated this summer and fall into a crescendo of wonders and terrors that one needs to be a particular kind of idiot to deny….

My position on AI is merely the conservative, skeptical position of 2006, updated with intellectual honesty for the reality of late 2026. And that position, if you need me to spell it out, is as follows: AAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAA AAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAA
AAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAA. It seems to me that the Singularity has already started; it’s just wildly unevenly distributed. Yes, I still unload the dishwasher and clip my toenails. On the other hand, in whatever years I have left, I don’t expect that I’ll ever again prove a theorem because I’m actually needed to prove it….

For anyone who says AI doom sounds like an apocalyptic religion, that the rationalists/Singulatarians seem like a Bay Area cult, that Eliezer Yudkowsky gives off the vibes of a messianic prophet: yes, yes, and yes. But crucially, today you’re no longer being asked to believe in arguments and extrapolations, but only in the front-page news. Accepting the reality of the coming machine god after it’s solved Navier-Stokes and dozens of other longstanding open math problems (while dramatically ramping up in capability every month), is sort of like accepting Jesus after he’s returned to earth on the gleaming cloud. It’s the epistemic bare minimum.

Yes, there’s still enormous uncertainty about what the rest of our lives will look like, but as far as I can tell, there’s no longer any real uncertainty that it’ll all mostly revolve around AI, and the extent to which we succeed or fail at directing its power toward human flourishing. By any accounting that doesn’t stack the deck, Eliezer Yudkowsky was right about what the greatest challenge facing civilization in our lifetimes was going to be, and you and I were wrong about it…

Get 75% off a group subscription

I am all on board with the coming of the info-bio tech-attention economy being a primary, if not the sole principal factor, in what a hundred years from now people will have said was the key engine of the history of 2025 to 2055. And I am all on board with calling what we are seeing thaumaturgy, from thauma, wonder, and ergos, working. But that is because of it usefulness and potential destructiveness as a human social-cognitive information technology. It is not because it will give rise to a Digital God. To think that is still seems to me to be a category error of the same kind as thinking that a steamship is the same order of being as a dragon. I still cannot see how any other judgment is possible except for people who have let the term “Artificial Intelligence” hack their brains, to their confusion.
Now it may be time for one amendment here. Perhaps the metaphor “stochastic parrot” has outlived its usefulness, and is now as much a blockage to understanding as “RSI leading to runaway Singularity and imminent Digital God” is. Properly trained, RAGed, and harnessed LLMs may still be stochastic parrot, but as they are enmeshed in the spheres of human cognition and public reason they increasingly do not act as stochastic parrot. They have crossed some sort of line that the “stochastic parrot” description was intended to deny. What sort of line? That of summoning from the Vasty Deep enough of the human minds whose actions formed their training data. In what sense “enough”? Ah. That is the big question now.


And to answer that, I need to revisit what I was thinking about last June with:

substackcdn.com/image/fet…}],"post_date":"2026-06-01T22:15:41.382Z","coverimage":"https://substackcdn.com/image/fetch/$s!Mdkp!,f_auto,q_auto:good,fl_progressive:steep/https%3A%2F%2Fsubstack-post-media.s3.amazonaws.com%2Fpublic%2Fimages%2F27bc5eae-14d7-466f-a061-22284a142274_1524x1640.png","cover_image_alt":null,"canonical_url":"https://braddelong.substack.com/p/stochastic-parrots-on-the-palatine","section_name":"SubTuringBradBot","video_upload_id":null,"id":200186908,"type":"newsletter","reaction_count":20,"comment_count":6,"publication_id":47874,"publication_name":"DeLong's Grasping Reality Weblog ","publication_logourl":"[substackcdn.com/image/fet…](https://substackcdn.com/image/fetch/$s!PgPl!,f_auto,q_auto:good,fl_progressive:steep/https%3A%2F%2Fsubstack-post-media.s3.amazonaws.com%2Fpublic%2Fimages%2Ffde2453e-9c18-4560-82ca-8b77ae62ef5b_1280x1280.png","belowTheFold":true,"youtube_url":null,"show_links":null,"feed_url":null)}“>
substackcdn.com/image/fet…}],"post_date":"2026-06-04T19:34:23.302Z","coverimage":"https://substackcdn.com/image/fetch/$s!DF7g!,f_auto,q_auto:good,fl_progressive:steep/https%3A%2F%2Fsubstack-post-media.s3.amazonaws.com%2Fpublic%2Fimages%2Ff2e4066b-3151-455e-93f2-9ae502705e50_1476x1186.png","cover_image_alt":null,"canonical_url":"https://braddelong.substack.com/p/stochastic-parrots-and-subturing","section_name":"Public Reason","video_upload_id":null,"id":200662304,"type":"newsletter","reaction_count":8,"comment_count":1,"publication_id":47874,"publication_name":"DeLong’s Grasping Reality Weblog ","publication_logourl":"[substackcdn.com/image/fet…](https://substackcdn.com/image/fetch/$s!PgPl!,f_auto,q_auto:good,fl_progressive:steep/https%3A%2F%2Fsubstack-post-media.s3.amazonaws.com%2Fpublic%2Fimages%2Ffde2453e-9c18-4560-82ca-8b77ae62ef5b_1280x1280.png","belowTheFold":true,"youtube_url":null,"show_links":null,"feed_url":null)}“>

<https://braddelong.substack.com/p/stochastic-parrots-on-the-palatine> <https://braddelong.substack.com/p/stochastic-parrots-and-subturing>

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##crosspost-john-gruber-ben-thompson-meanness-claude
##info-bio-tech-attention-society
##mamlms
#subturingbradbot
##crosspost
#anthropic
#claude
#john-gruber
#ben-thompson
#dithering
#stratechery
#stochastic-parrots
#clever-hans
#eliza-effect
#joseph-weizenbaum
#digital-god
#scott-aaronson
#eliezer-yudkowsky
#thaumaturgy

What Jón Steinsson Learned from Mike Woodford in Econ 420: ENCOMIUM OF THE DAY

The Woodford framework: The interest rate, not the money stock, is the instrument. Expectations are the dominant channel, so credible commitment to a rule is everything. Price stability minimizes relative-price distortions. And rules must move rates more than one-for-one with inflation to rule out self-fulfilling spirals:

Jón Steinsson calls this toolkit his personal intellectual-cognitive superpower.

Share

He got it from this guy:

Give a gift subscription

And so this was especially nice to see:

Jón Steinsson: <https://x.com/JonSteinsson/status/2109810749422084265>: ‘Just a personal addendum: Mike was my undergraduate thesis advisor at Princeton. This was a transformative experience. One of the crucial turning points in my life. So, I count myself as a Woodford student (part of the Woodford army, some might say :) ). Then I was fortunate enough to have Mike as a colleague at Columbia for 10 years. On a number of occasions, conversations with Mike were pivotal for my research (e.g., when Emi and I were working on our fiscal stimulus paper).

But for me, the Woodford experience started in Econ 420 at Princeton in 1999. This was a small undergraduate class with maybe a dozen students. But among those were four people that would end up tenured at top 10 econ departments. It was a pretty special class!

To do good research, one needs to have a few "superpowers" up one's sleeve: things one understands really well and are applicable to lots of issues that come up in one's research. One of the most important "superpowers" that I have as a scholar (to the extent that I have any) is the theoretical ideas about monetary economics that Mike taught me and I studied in his book. They are a constant source of new insight which permeate my research. (For me, they have been especially powerful when mixed with empirical ideas from other fields).

I am simply over the moon that Mike has won the Nobel Prize <https://www.nobelprize.org/prizes/economic-sciences/2026/popular-information/>…

Share DeLong's Grasping Reality Weblog

Agreed. Mike is extra-special: to read, to listen to, to talk to and bounce ideas off of, and is someone always interested in making you smarter than you have been (and never in demonstrating that you are not as smart as you think you are). A true and dazzling gem.

But what are those “theoretical ideas about monetary economics that Mike taught me”—or, as I would put it, the system prompt for the SubTuringMikeWoodford emulation instantiation that Jón runs on his wetware? (And, yes, Jón Steinsson definitely does have cognitive intellectual superpowers.) Briefly, I think Jón has two things primarily in mind:

  1. The Neo-Wicksellian view: policy is an interest-rate rule set against an economy’s neutral rate of interest: the rate that makes Say’s Law as true as it can be in practice even though it is false in theory, the rate that makes “money” into as much of a mere veil as it can be. I see this in “Fiscal Stimulus in a Monetary Union” that Jón says Mike’s conversations were pivotal for, as a regional spending multiplier can be measured cleanly in a monetary union because it holds the interest-rate response fixed across regions, in “Optimal Monetary Policy in an Economy with Inflation Persistence” written right after taking Econ 420; and still present in the just-written “Beyond the Taylor Rule”.

  2. Monetary policy works by managing expectations: For what moves spending is the market’s expected future path of short rates, which feeds into long rates, equity prices and exchange rates. This is just as true in a monetary system with a commodity anchor as in one in which there is only a central bank. (Indeed, this is I think the only way to understand the difference between the pre-1914 relative success and the post-1918 catastrophic failure of the gold standard as a monetary system.) In Jón’s writings, look for example at “The Power of Forward Guidance Revisited” (AER 2016), and “The Discounted Euler Equation”, and “High-Frequency Identification of Monetary Non-Neutrality: The Information Effect”.

Leave a comment

And, again briefly, the focus of Mike Woodford’s masterwork Interest & Prices: Foundations of a Theory of Monetary Policy is on how to synthesize Wicksellian tradition with New Keynesian nominal rigidities in a framework setting forth a theory of how central bank commitment to specific interest-rate rules can stabilize prices and mitigate the welfare losses associated with sticky prices and wages:

Nominal interest rate adjustment
→ change in real interest rate
→ shift in aggregate demand
→ impact on real marginal costs
→ adjustment of price-setting behavior
→ stabilization of the price level/inflation.

Refer a friend

Commitment to a policy rule of some sort is necessary to manage private-sector expectations and achieve optimal outcomes, on how sticky prices and staggered price-setting create strategic complementarities, and how for equilibrium determinacy the nominal interest rate must respond to inflation more than one-for-one to ensure the real interest rate rises when inflation rises. With:

  • Interest rates as the primary instrument: thinking first about the quantity of money gets you really confused

  • Expectations and their management as the overwhelming channel: the public’s belief in a central bank’s commitment is the principal determinant of the effectiveness of the policy.

  • Price stability as welfare optimum: it minimizes relative-price distortions and maximizes utility. (I, however, see this analytical commitment as not a feature but a bug.)

  • Equilibrium determinacy: Only some policy-rule structures prevent self-fulfilling inflations.

Get 75% off a group subscription

Yes, I know, problems: the shoe-leather costs of inflation are not its real welfare costs, the representative-household utility framework is a very bad bug, log-linear approximations mean Woodford has nothing to say about crises and not much to say about monetary policy at the zero-lower bound, and so forth.

But relative to other frameworks on offer, Woodford’s is much better to think with.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##what-jón-steinsson-learned-from-mike-woodford-in-econ-420-encomium-of-the-day
##macro-outlook
##encomium-of-the-day
#what-jón-steinsson-learned-from-mike-woodford-in-econ-420
#jón-steinsson
#mike-woodford
#econ-420
#economics-nobel
#monetary-economics
#interest-and-prices
#new-keynesian-macro
#neo-wicksellian-macro
#managing-expectations
#monetary-policy-rules
#central-banking

A Second-Rate Philosopher I Cannot Read in His Original Greek: REGRET OF THE DAY

Epictetus provide a better guide to stoicism. Seneca writes better prose. So Why is it that Marcus Aurelius’s private, repetitive, nagging-himself notebook endures and influences more than all the other stoics put together? “Don’t turn into just another Caesar,” Marcus warned himself. But how could he stop that? He already was the Caesar. Thus the Meditations reads less like a philosophy lesson than like a man arguing with himself, losing, and then picking himself back up off the floor and trying to man-up to argue with himself again”:

This AM, from across 1850 years of time, history now comes to speak to me.
Share

It comes to speak to me through the person of the one and only Imp. Caesar M. Aurelius Antoninus Augustus…

Give a gift subscription

…Armeniacus, Parthicus Maximus, Medicus, Germanicus, Sarmaticus, Pontifex Maximus, Tribuniciae Potestatis XXXIV, Imperator X, Consul III, Pater Patriae:

Marcus Aurelius (ca. 175): Meditations V.1: ‘Can’t get out of bed this morning?

Tell yourself: “I’m getting up to do a human being’s job.” So why complain about doing the thing I was born to do, the reason I’m here at all? Was I made to lie under the covers and keep warm?

“But it feels nice.” Nice? You were born to feel nice? Or to get up and do things?

Look around. Trees, plants, sparrows, ants, spiders, bees: every one of them is busy doing its part to keep the world running. And you won’t do yours? You won’t hurry to do what your nature asks of you?

“But I need rest.” Sure you do. Nature gives you a ration of rest, the same way it gives you a ration of food and drink. But you take more rest than you need, and less action than you could manage.

So you don’t really love yourself. If you did, you’d love your nature and what it’s aiming at. People who love their trade wear themselves out at it. They skip meals and forget to eat. Do you respect your own nature less than a carpenter respects carpentry, or a dancer respects dance? Less than a miser loves money, or a show-off loves applause? Those people give up food and sleep for what they care about. And working for the common good gets less from you than that?…

Share DeLong’s Grasping Reality Weblog

Marcus Aurelius’s Meditations has long spoken to me. Yet it is an extremely odd book. It was not written for us. The title it was given was Ta eis Heauton: “Things to Himself”. But that is perhaps a label imposed on it by a later librarian.

It nags, scolds, consoles and nags again.

Mark was the most powerful man in the Mediterranean world. Yet he wrote much of it not in luxury in Rome in his palaces, but rather in tents along the Danube frontier. Notes like “Among the Quadi, on the Gran” and “At Carnuntum” were left as datelines. And his role among those tents was, well, primarily as a figurehead: showing that the emperor cared while his professional generals went about their jobs of trying to stabilize the situation and secure the safety of the cities and farmers of the Danube Valley.

Yet for more than half a millennium it has been one of the most widely read works of ancient philosophy.

Give a gift subscription

Read more

CROSSPOST: CLAUDIA SAHM: Hand the Pen to the Committee

Warsh’s press conference and the FOMC committee statements he is letting through are pointlessly opaque. Pointlessly, that is, if the idea is to make good monetary economy and have a stabilized high-growth sustainable-employment low-inflation economy. Warsh’s opaqueness, however, does have a point if you think that Warsh’s principal objective is to delay the day of reckoning when he has to choose between having Trump conclude that he has been betrayed and having the bond market conclude that it is being betrayed by Warsh. He will ultimately have to choose between one or the other, but each day that choice is delayed is a victory for him, if not for the economy, the country, and the world:

We have Claudia Sahm this morning.

Share

She is stressing that:

  • Under Warsh, the FOMC statement is less than half its old length.

  • Under Warsh, what he says at the press conference doesn’t track the Committee’s views.

  • As a result, markets initially filled the gap by pricing in more tightening than the Fed in fact intended—and than it would have known had Warsh not messed up both the statement and the press conference.

Be clear: Claudia Sahm agrees 100% with the Fed’s September rate hike. Her objection is to how it was explained. And her objection is very cogent.

Give a gift subscription

This is, to say, the least, unprofessional.

Share DeLong’s Grasping Reality Weblog

Claudia went on to say that a rate hike that is (a) insurance is small and conditional, while one that is (b) forced by the Fed’s beliefs about the inflation outlook is not. Since, on decision day, Mademoiselle Marchée couldn’t tell which kind she was getting, she split the difference when in fact she was getting (a). Fifty more words in the statement could have saved two Fed officials from talking down expectations of a further rate hike that the Committee had never seriously considered.

This time, Warsh’s opacity both confused markets and annoyed Donald Trump. No man can serve two masters, although Warsh tries. And this time he did not serve either one. As Claudia further points out, when the Chair is the Committee’s outlier, the statement has to carry the Committee’s reasoning. It didn’t. And it doesn’t.

Claudia Sahm:


CROSSPOST: CLAUDIA SAHM: Hand the Pen to the Committee

<https://stayathomemacro.substack.com> <https://stayathomemacro.substack.com/p/hand-the-pen-to-the-committee>

Stay-At-Home Macro (SAHM)
Hand the pen to the Committee
Three meetings make a trend. Under Chair Warsh, we no longer learn the Committee’s reasoning on the day of the decision. Instead, we must wait three weeks for the FOMC minutes. The statement has been cut by more than half, and the press conference no longer sticks closely to the Committee’s views. The cost of th…
Read more
The Fed’s main reason for raising rates took three weeks to reach the public. The statement should carry it on decision day.

Claudia Sahm

2026-10-12
Credit: Emilija Manevska via Getty Images.

Three meetings make a trend. Under Chair Warsh, we no longer learn the Committee’s reasoning on the day of the decision. Instead, we must wait three weeks for the FOMC minutes. The statement has been cut by more than half, and the press conference no longer sticks closely to the Committee’s views. The cost of that delay showed up in markets this time, which priced in more rate hikes than the Committee itself projects.

My complaint is with the communications, not the decision. I agree with the quarter-point rate increase and share the risk-management reasoning of many Fed officials.

There is a straightforward solution, and it’s one for the Committee: put the rationale for the decision in the statement. The public and markets need to understand why you voted the way you did. The minutes can add details three weeks later, but the statement should make the story clear, including where views diverge. Today’s post traces the Fed’s information flow on the September decision, shows what the confusion cost in interest rates, and proposes what the statement could say on decision day.
What we learned, and when, on why the Fed raised rates.

The fundamental tension in Fed communications now is that Chair Warsh approaches monetary policy differently than the rest of the Committee. This should surprise no one. Even as a Governor, Warsh stood out as a monetary policy outlier. Now the outlier is the Chair. Chairs Bernanke, Yellen, and Powell, who had the same set of communication tools, were much closer to the Committee’s thinking, though each, on the margin, shaped the approach.
Here is what we learned about why the Federal Reserve raised interest rates on September 16, in the order we learned it. Emphasis added in bold.

FOMC statement (2:00 pm, decision day):

Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal. The Committee will deliver price stability…

Summary of Economic Projections (2:00 pm, decision day):

While the SEP does not provide a rationale for the policy decision, the dot plot, with its appropriate path of monetary policy, offers a sense of how much tightening the Committee had in mind. The median Fed official (excluding Warsh, who did not submit projections) viewed one more quarter-point increase this year, on top of September’s, with no further increase by the end of next year, as appropriate. That half-percentage-point total is markedly less than the 3-percentage-point increase in a typical hiking cycle. In addition, 17 of 18 participants said inflation risks were weighted to the upside.

Chair’s press conference (2:30 pm, decision day). In his prepared remarks, Warsh repeated the statement language above and offered details:

Our decision comes at a time when the American economy appears to be strengthening. New hiring, private-sector earnings, business capital investment—each of these markers has improved in recent months and is pointing in a good direction. Credit flows have been robust, particularly for businesses. And, as I said at the policy symposium in Jackson Hole, I would be hard pressed to describe broad financial conditions as restrictive. This view was widely shared by the Committee. So we removed a dose of accommodation…

Key speeches by Fed officials (about two weeks later):

Several Fed officials spoke after the FOMC meeting. Two speeches received considerable attention: those by New York Fed President John Williams and Board Vice Chair Philip Jefferson, who, along with Warsh, make up the FOMC’s leadership.

Williams:

Based on the totality of the data, the balance of risks to achieving our dual mandate has evolved in recent months. With the economy proving resilient in the face of shocks and with underlying demand strengthening, the risk to maximum employment has receded. At the same time, the risk to achieving price stability has increased. In particular, the inflationary impact of the AI-related demand shock is increasingly salient, and I now expect somewhat larger and longer-lasting effects from energy prices on inflation…

Jefferson:

Considering the economic conditions that persisted through mid-September, the FOMC voted last month to raise the target range for the federal funds rate by a ¼ percentage point to 3-¾ to 4 percent … I supported that decision because I saw it as the appropriate policy to pursue the Fed’s dual mandate. This was an important step to ensure longer-term inflation expectations remain well anchored and to validate the public’s confidence that we will achieve our 2 percent inflation objective in a timely manner…

Finally, the FOMC minutes (three weeks later) offered the definitive view on why the Committee raised rates in September:

In their consideration of monetary policy at this meeting, all participants supported raising the target range for the federal funds rate ¼ percentage point to 3-¾ to 4 percent. Participants generally emphasized that inflation remained elevated while the labor market appeared to be near full employment, with some signs of strengthening, and that economic activity was expanding at a solid pace. Furthermore, almost all participants assessed that, while inflation risks were tilted to the upside, risks to the labor market had diminished and were now broadly balanced. Based on the outlook and the changing balance of risks, all participants viewed a higher target range for the federal funds rate as appropriate. Participants judged that this would support a timelier return of inflation to the Committee’s 2 percent goal. Many participants emphasized that a higher path for the target range would be prudent on risk-management grounds, providing insurance against inflation remaining persistently above target due to stronger-than-expected demand or further adverse supply shocks. A number of participants viewed a higher path for the target range as necessary based on their modal outlooks rather than on risk-management grounds. Some participants remarked that a higher policy rate would diminish the risk of persistently elevated inflation unanchoring inflation expectations and becoming further entrenched…

On the day of the decision, we did not get a complete picture of the Committee’s reasoning. The subsequent Fed speeches helped fill some of the gaps, but it wasn’t until the minutes came out that the theme of risk management came through clearly. According to the minutes, risk management was the most common reason for raising rates, followed by participants’ baseline forecasts for inflation and concerns about anchoring expectations.

“The economy is strengthening,” as conveyed in the press conference, is a very different reason to raise rates than “we are concerned about the risk that inflation stays high.” The former supports several rate hikes; the latter supports a small rate adjustment.

The minutes also reveal another problem with the statement. The Committee was united in raising rates but divided on why. Nothing in the statement alerted us to these divergent views. A “timelier return” to 2 percent inflation is probably something all three groups can sign on to, but it left out a lot of information. It also sat awkwardly with the SEP, where the median does not reach 2 percent until 2029, and led to a confusing exchange with a journalist in the press conference when Warsh said the projections were not his.

Confusing communication is costly.

The September meeting offers a clear example. The market odds of rate hikes this year, and especially next, rose during the press conference, as Warsh’s words were viewed as more hawkish than the statement or the dot plot. Market pricing continued to rise in the weeks after.

The growing gap between more aggressive market pricing and the modest increases in the dot plot likely shaped what Williams and Jefferson said two weeks after the meeting. Before they spoke, the odds of a rate hike in October had climbed to about 70% (chart below). In addition to sharing their reasons for raising rates, they had a message of patience. Williams said there was “no need for urgency” and that they have “time to gather more information.” The market odds dropped 20 percentage points. Jefferson noted that yields had risen further since the meeting and reinforced the theme of patience, saying it “may take more time” to form judgments about policy. The odds dropped another 13 percentage points.

With more favorable inflation data and softer-than-expected payroll data also that week, the odds of an October hike ended the week just over 20%. Two thirds of the decline came on the days of the two Fed speeches.

Confusion about the Fed’s reasons for the hike on the day of the meeting helped create the need for this post-meeting correction. A hike explained as insurance is limited and conditional, and one taken because the inflation baseline requires it is not. In the minutes, many participants called a higher path “prudent” on risk-management grounds, and fewer called it “necessary.” Had the motive been clear on decision day, markets could have worked out the pace themselves, and two officials would not have needed to give explicit guidance about October. Warsh is right that explicit forward guidance should not be necessary right now. But that depends on clear communication from the Fed about its policy decisions.

The October meeting is the easiest case to document, but the larger gap between market pricing and the SEP is for next year, and it remains. Higher-than-intended interest rates cost borrowers. When unclear communication pushes rates above what the Committee intends, that is unintended tightening.

Cleaning up decision day: let the Committee speak.

On the day of the decision, we must understand the reasons for the Committee’s decision. The statement is the best place for the Committee’s thinking to live. Clarity should take precedence over brevity. Accuracy should take precedence over the appearance of consensus. If there were three reasons behind a vote, then share the three reasons, as the minutes do. If it takes a few sentences to get the main ideas across, then use them. Only the FOMC knows why it voted the way it did. Tell us, so outsiders aren’t guessing or filling in the blanks.

Given what we know now from the minutes, my suggestion (added text in yellow) for the September statement would have been something like:

(My proposed last paragraph for the September statement)

Inflation remains elevated. Risks to inflation are tilted to the upside, while risks to the labor market are now broadly balanced. The reasons for the increase varied across the Committee. The most common was to insure against inflation staying persistently above target. Smaller groups cited their baseline outlook for inflation and the need to keep inflation expectations anchored. Today’s policy action will support a timelier return to the Committee’s 2 percent goal. The Committee will deliver price stability…

This adds about 50 words, and the statement would still be shorter than a year ago.

Unanimous in purpose and in action, but divergent in the specific reasons. That’s an honest assessment of where the Committee is. It’s good for accountability, and it’s also good for markets trying to figure out where the Fed is headed next. Understanding where the Committee is right now in its thinking is valuable. Waiting three weeks to get a clear picture is unacceptable.

The Chair is the only person on the Committee who is allowed to speak for the Committee, but that doesn’t mean the Chair is the only possible messenger. The statement, like the minutes, is a Committee document. Hand the pen to the Committee and give Warsh the mic at the presser.

In closing.

The goal is good policy. Good policy is best served by good communication. For three FOMC meetings in a row, the reason for the vote has not been fully communicated on the day of the decision. Waiting three weeks for the minutes is too long.

I agreed with the decision to raise rates in September. My own shift from hold to hike came from heightened upside risks to inflation. The FOMC said it is trying to support a “timelier return” to 2% inflation. Good, now I want to see them deliver timelier information on their thinking. Explain the decisions when they are made.

<https://stayathomemacro.substack.com/p/hand-the-pen-to-the-committee> <https://stayathomemacro.substack.com>

Stay-At-Home Macro (SAHM)
Hand the pen to the Committee
Three meetings make a trend. Under Chair Warsh, we no longer learn the Committee’s reasoning on the day of the decision. Instead, we must wait three weeks for the FOMC minutes. The statement has been cut by more than half, and the press conference no longer sticks closely to the Committee’s views. The cost of th…
Read more

Brad DeLong here: Odds of an October hike reached about 70% before New York Fed President John Williams and Vice Chair Philip Jefferson stepped in to calm things down. Two-thirds of the drop that followed came on the two days they spoke. There was a cost to this round-trip, an avoidable cost. It was the result of a statement that said too little, and a press conference that said even less that was true about the FOMC’s frame of mind.

Refer a friend

You already know why I think this is happening. What are the implications?

Well, look at the September information flow:

  • The post-meeting statement said only that inflation “remains elevated” and that the hike would support “a timelier return” to 2%.

Read more

Henry Farrell of Johns Hopkins Agora Comes to Berkeley: FOG & FLATLANDS

Farrell treats AI as one more of the information-processing social institutions Herbert Simon described, alongside markets and bureaucracy, rather than as the buliding of a Machine God-Overlord:

Now comes Henry Farrell to to BESI—to the Berkeley Economy & Society Initiative’s “Capitalism & Democracy” lectur series.

Share

Henry is here to:

  • Title: “AI as Social Technology: A Research Agenda for Political Science”

  • When: Friday, October 9, 2026, 4–5:30 p.m.

  • Where: 820 Social Sciences Building, UC Berkeley

Give a gift subscription

Share DeLong's Grasping Reality Weblog

Henry has a teaser:

Henry Farrell: Event Information <https://besi.berkeley.edu/event/ai-as-social-technology-a-research-agenda-for-political-science/>: ‘Political scientists are only beginning to think systematically about how AI may reshape the topics they study, even though one of the founders of the field of AI, Herbert Simon, was a political scientist. In this talk, Johns Hopkins political scientist Henry Farrell will leverage ongoing work with collaborators (including Alison Gopnik, James Evans, Cosma Shalizi, and Hahrie Han) to argue that Simon’s work on collective information processing provides a useful foundation for political scientists to think about how AI affects politics.

Simon argued that individual human cognitive capacities are limited, and larger-scale institutions such as markets and bureaucracy provide means of collectively processing information and reducing down the complexities of the world to make them more manageable. More recently, computer scientists and physicists have begun to use concepts such as lossy representations and coarse graining to make closely related arguments.

In his presentation, Farrell will explain how large language models provide just such lossy representations, as previous technologies have done before. Recognizing this opens up new possible research questions for political science and political theory, says Farrell. He’ll lay out the beginnings of one new agenda item: how lossy technologies of representation affect the formation of democratic publics.

Refer a friend

And Paul Pierson says:

Henry Farrell is the SNF Agora Professor of International Affairs at Johns Hopkins School of Advanced International Studies. He is the 2019 recipient of the Friedrich Schiedel Prize for Politics and Technology, a prize for “outstanding individuals who contribute to inter- and trans-disciplinary projects linking politics and technology,” awarded jointly by the Friedrich Schiedel Foundation and the Technical University of Munich. Previously, he was professor at George Washington University’s Department of Political Science and Elliott School of International Affairs.

He works on a variety of topics, including the relationship between democracy and information, the security consequences of international economic networks, and international political economy. He is the co-author, with Abraham Newman​, of Underground Empire: How America Weaponized the World Economy <https://us.macmillan.com/books/9781250840554/undergroundempire/> (2023), which was awarded the Council of Foreign Relations Arthur Ross Book Award Bronze Medal.

Get 75% off a group subscription

And I have a question (many questions, actually, but here is just one) for Henry:

As of 1880, when he was writing Socialism: Utopian & Scientific Friedrich Engels had what he thought were reasonable hopes and reasoned faith that the lived experience of the steampower economy—enormous human productive power, substantial interchangeability of individual human cogs in the productive machine, the insubstantial relative nature of all potential divisions between humans in the face of the techno-organizational requirements of the steam engine—would make it obvious that we should all dress in identical blue overalls, call one another “comrade”, share the enormous productive dividends of steampower and science equally, and build a free society of associated producers, replacing politics as the domination of man over man with the mere administration of things and coördination of processes of production.

But the steampower economy was succeeded by the applied-science economy of the Second Industrial Revolution GPTs in which divisions of skill, experience, industry location, and ethnicity were to “play the serpent to this paradise” of the Belle Époque. Could anyone in 1880 have been reasonably expected to anticipate much of anything about the shit was going to go down over the next sixty years? How soon could people have been expected to inclue themselves to pieces of it?

And what lessons from the transition from the steampower to the applied-science modes of production can we learn as we confront the transition from the globalized value-chain to the info-bio tech-attention mode of production?

Leave a comment


Thinking about the political-science research program that Henry is working to, I find myself thinking right now about:

  • The Herbert Simon Frame: Political science already has the tools to understand “AI”. It has simply forgotten them. Herbert Simon held that individual minds are limited, so markets & bureaucracies process information collectively by simplifying the world. Large language models do the same thing: they are new and powerful ways of accessing the real-ASI the Anthology Super-Intelligence of the collective human mind, and put it to use via the management-cybernetics trick of creating a useful coarse-graining of information for action in the current situation. Seeing LLMs as social & cultural technologies akin to writing and recording, print distribution, markets, bureaucracies, feudal hierarchies, democracies, ideologies, and so forth rather than nascent godlike minds opens new questions.

  • The Shoggoth Frame: Doomerscasts LLMs as alien minds behind a smiley mask, waiting to devour us. Henry Farrell & Cosma Shalizi turn it aroundL The self-regulating market & the iron cage-building Weberian bureaucracy were the first vast, inhuman information-processing systems. And “he Singularity” began with the Industrial Revolution. LLMs are a newer, smaller shoggoth. They condense human writing into useful but lossy summaries, no lossier than prices, bureaucratic categories, & opinion polls. The real questions are how these systems compete & hybridize. Could LLMs capture Hayek’s tacit knowledge better than prices do? Will they make Kafka’s bureaucracies saner, or more arbitrary & opaque?

  • The Democratic-Publics Frame: Much prominent work on AI & democracy imagines algorithms perfecting deliberation, with randomly chosen mini-publics reasoning their way to consensus. Henry Farrell & Hahrie Han call that a mirage. Real democracy runs on enduring, interested publics: parties, movements, & coalitions like Minnesota’s ISAIAH. Feedback loops of negotiation, loyalty, & power hold them together. Does AI strengthen those loops, or replace them with brittle, microtargeted crowds of outraged consumers?


Further Reading:

<https://www.programmablemutter.com/p/shoggoths-amongst-us> <https://knightcolumbia.org/content/ai-and-democratic-publics> <https://www.science.org/doi/10.1126/science.adt9819>

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##henry-farrell-of-johns-hopkins-agora-comes-to-berkeley-fog-flatlands
#info-bio-tech-attention-society
##mamlms
##fog-flatlands
#henry-farrell
#ai-as-social-technology
#cultural-technologies
#herbert-simon
#sciences-of-the-artificial
#coarse-graining
#democratic-publics
#shoggoths
#political-economy #
#markets
#bureaucracy
#deliberative-democracy
#friedrich-engels
#second-industrial-revolution

(SEMI-)CROSSPOST/HOISTED: MATTHEW YGLESIAS (2022): What I Learned Co-Founding Vox

Yglesias's postmortem of Vox shows how distribution economics shapes what journalism can be. Paying salaries required income. Ad-funding required scale. Scale required kowtowing to FaceBook’s and Google’s algorithms. That made for enormous pressures to back off from true data and explainer journalism back toward clickbait—in Vox’s case, a very mild form of clickbait, but still it was what the eyeballs that it could harvest and sell to advertisers wanted to see. It was not what the eyeballs it attracted needed to see…

Back in the Second Age of Weblogging, Melissa Bell, Ezra Klein, and Matt Yglesias decided to try to change the world and make some money for themselves and funders by disrupting journalism.

Share

They decided to try starting an organization that would do explainer journalism for real, and focus on informing its readers rather than the myriad of missions existing journalistic organizations undertook, many of which were at best orthogonal to the idea that your customers were your readers and viewers and that your job was to help them learn true things about the world.

By and large, it went moderately well. <http://vox.com/> is still around, still paying its bills, and if it is now much more simply standard journalism for the decade of the 2020s, this is 3/4 the system wearing down its idealistic and public-service commitments to informative explainer journalism, and 1/4 its dragging others along with it to its point of view.

Give a gift subscription


I wanted to hoist/crosspost and then comment on this from Matt Yglesias nearly four years ago, but then I found that the entire thing is (still?) behind the paywall:

<https://www.slowboring.com/p/what-i-learned-co-founding-vox>

Share DeLong's Grasping Reality Weblog


What to do, what to do? Well, I feel no compunction about an extensive quote giving away the stance Matt takes here:

Matt Yglesias (2022): What I Learned Co-Founding Vox <https://www.slowboring.com/p/what-i-learned-co-founding-vox>: ‘It’s a subject that’s been rattling around my head for a long time…. I recently gained some clarity when I mentioned offhandedly to a younger journalist that I thought I’d failed with Vox and she was surprised because Vox is still there, running articles and putting out podcasts and employing lots of people…. Vox… are producing a lot of great stuff like Rachel Cohen on abortion rights referenda and education in the midterms and Li Zhou breaking down the actual content of the congressional marriage equality bill. Quitting a good job that I liked at Slate to launch a new website was a ton of hard work and a huge pain in the ass! I only did it because I had insanely high ambitions, and I think Ezra and Melissa felt the same way — the current state of the site is a failure only relative to these ambitions….

The folks who run Vox Media, Jim Bankoff and Pam Wasserstein, are smarter about business than I’ll ever be, and they have what I think is a reasonable plan….So when I say that I think that we failed, I’m not dumping on the current Vox management team or editorial staff, who are doing a good job executing a reasonable strategy — it’s just not the strategy we set off with. There’s no innovative editorial project along the lines of our long-abandoned cardstacks. They don’t really do explainers anymore. You’d be hard-pressed to describe what differentiates a Vox article from an Atlantic article or a Slate article… an incredible flattening of the content landscape, and Vox has become part of that flattening rather than an alternative to it.

This post is my effort to unpack how we fell short of those aspirations…

Leave a comment

As to the rest of it, let me attempt to not infringe on Matt’s IP—of the 17 articles on <[slowboring.com](http://slowboring.com)> so far this October, only three are not paywalled, and the paywalls are typically ferocious. But I will summarize, extensively:

The principal lesson Matt says he learned is this: A good idea plus a great team is not enough. A business also needs people it can actually hire, bosses who can effectively coördinate, an awareness of how the competition is changing, an ability to find a lane, and a revenue model that fits the product. The secondary lesson Matt says he learned is this: Running a business stacks many medium-difficulty problems on top of each other, and intellectuals tend to massively underrate the skills of the coördinating and organizing people who solve them. The tertiary lesson Matt says he learned is this: While hiring is hard, training is even harder, for there was no recipe, no secret sauce, to turn new hires into Ezra Klein–style writers.

The principal argument Matt makes is that Vox failed relative to its founders’ aspirations because:

  1. The kind of talent they needed didn’t scale and was hard to find.

  2. Their business depended on ad-driven platforms.

  3. The New York Times adapted rather than let itself be disrupted.

Get 75% off a group subscription

Vox was driving hard to achieve serious scale and support itself via a web-advertising model. But advertisers demand huge scale since each viewer’s eyeballs are worth very little. In the mid-2010s, huge scale meant traffic from FaceBook and later Google

Thus in order to stay in business, Vox had to recognize that its readers were not its customers, its advertisers filtered through FaceBook and Google were.

That meant bending to their technical, editorial, and above all algorithmic business preferences. For example, Vox’s “cardstack” explainer format couldn’t work on Facebook. And what went viral on FaceBook was a mix of identity politics and denunciations of the 1%, and that then shaped what got written. Vox therefore flattened into the same sameness as everyone else, as people noted that saying things were not simple did not get eyeballs.

Product innovation therefore became impossible.

The scarce talent that could have set Vox apart was hired away by the Times, which had a subscription-revenue base, went all-in on it, and thus found a business model in which each reader was potentially worth more.

Yes, Matt may be self-serving here: Talent shortage, platforms, and NYT competence are all external or structural causes, and the founders’ own strategic choices get little scrutiny.

The inability to create a pipeline to spread Ezra Klein’s expertise is also worth much more scrutiny: Many young journalists in the mid-2010s wanted to acquire the expertise of Ezra Klein and were willing to work very hard to figure out how to do that. Hell, many young and old journalists today want to acquire the expertise of Ezra Klein and are willing to work very hard to figure out how to do that. We have a society that is superb at turning knowledge of how to do things into recipes that can be taught, into tekhne, and, yes, on top of tekhne there rides what Michael Polanyi calls “tacit knowledge”, what James Scott calls metis, what Sean Illing calls phronesis—not just doing the thing, but doing the thing in the time, place, and way that makes it useful. And pretty much the only way to learn that is extensive apprenticeship, working and assisting at the elbow of someone who has it.

But I think that the fundamental point is that there was an audience for explainer journalism, but not an audience that could be harvested for ads at scale in the malign social-media internet of the day, with its ragebait, its clickbait, and its shouting class.

Refer a friend


OK. So, then, where are we now? What does this mean for me, as I try to make my fall push to figure out what to do with this SubStack thing? Especially in the onrushing world of “AI”, which can combine and remix ideas both assisting me and replacing me in a way that was impossible two years ago, and in which a good deal of what I have done has been playing the glass-bead game in a way that machines are now learning to do, in some ways better than I can?

Readers-versus-customers is easy, thanks to SubStack. SubStack really does solve the alignment problem. <http://vox.com/>’s finding that to pay its bills it had to align with the FaceBook and Google algorithms was the biggest blockage to Vox’s success. I only have to write what the low six figures of people find worth their scarce attention and, for one in forty, their money. That is a much lower bar to clear in terms of scale, and a much higher bar to clear in terms of quality. It is also, for me, I think, the right bar.

But note that the platform-dependency problem has not vanished. Google Zero—Google driving zero traffic to anyone else’s website—is coming. The Information Superhighway’s on-ramps are being turned into toll booths that answer the question themselves, by remixing what the rest of us wrote. Being discoverable is no longer the asset. Being trusted is. Whatever value I add does not come from producing grammatical paragraphs about the Smithian division of labor, the Polanyian double movement, or the post-1870 long century. Machines now produce those by the bushel. My value lies in knowing which of a thousand such paragraphs is actually true and relevant this week.

And this brings me to the Hermann Hesse novel, The Glass-Bead Game. In Hesse’s novel, the Castalians spend their lives creating ever-more-elegant syntheses. A theme from Bach is linked to a theorem of Euclid, which is linked to a passage from the I Ching. All of it is gorgeous, all of it is self-referential, strung together like glass beads on a string, and all of it is useful and interesting by virtue of the juxtaposition and the remix. And now there is a machine that has read everything, and that strings beads via juxtaposition and remixing faster than I can, and sometimes more prettily—although I think it has useful and relevant taste only by accident. Not to mention the deep question of whether the glass-bead game is a game worth playing in the first place

So what does this mean for my fall push? Five things, I think:

  1. Fewer beads, more vouching. Less of the “here are fifteen interesting things” firehose. More of “here is the one thing this week that I think is true and important, here is why, and here is what would make me change my mind.”

  2. Show the work. That will be a large part of what readers will increasingly pay for: domain-knowledge expertise visibly hacking through increasing amounts of AI-slop.

  3. Be the apprenticeship. Model phronesis, what of it I have, so that others can apprentice. This newsletter’s highest use may be opening the gate so that readers can watch judgment being exercised, in real time, on live questions.

  4. Choose the questions. Machiavelli wrote that in the evening he put on formal robes and entered the courts of the ancients to ask them questions. I should not simply react to the current thing. I should draw people over to the important questions.

  5. Small is fine. Vox failed by its founders’ aspirations because it needed gargantuan scale. I do not.

Will this work? Is a fall push worth making? I genuinely do not know. I will find out.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##semi-crosspost-hoisted-matthew-yglesias-2022-what-i-learned-co-founding-vox
##public-reason
#mamlms
##info-bio-tech-attention-society
##crosspost
##hoisted
#matthew-yglesias-2022-what-i-learned-co-founding-vox
#matthew-yglesias
#what-i-learned-co-founding-vox
##vox-com
#explainer-journalism
#substack
#reader-funded-vs-ad-supported-media
#platform-dependence

"You Are Not Taking Up Too Much of My Time": A Note from a Not Asocial but Rather Parasocial Age: CHART OF THE DAY

I have read and heard most of what Charlie Jane Anders has written and podcast over the past 6.5 years since the start of the plague, yet I do not think I have seen or had a two-way voice or video call with her since. Thus America today has, in my estimation, not a problem of asociality but of wrestling with a sociability that is no longer person-to-person network but rather profoundly parasocial, even when the parasociality is a two-way symmetric one:

I think the decline in sociality and sociability is very real, but is usually misdescribed.

Share

We haven’t become asocial. We have become parasocial. When we do person-to-person network socialize, we do so differently: at restaurants instead of in each other’s homes, and through email, newsletters and feeds. We are connected to far more people than our grandparents ever reached.

But. There is a big “but”. From Data for Progress, via Adam Tooze:

Give a gift subscription

What would it have looked like from, say, 1955 to 1995, with the rise of TV? And my sense is that where my parents and grandparents would have had people over or gone to their houses, the youngs these days meet out at restaurants. Certainly we do—in fact, rather than having an out-of-town visitor over for dinner tonight, we are meeting at Gather <https://gatherberkeley.com/>, which claims that American Express lists it as one of the world’s best farm-to-table restaurants.

And, of course, I do communicate with vastly more people, friends and strangers alike, than did my grandparents with their in-person meetings, their low-audio-quality long-distance phone calls, and their Walter Cronkhite and Theodore H. White news funnels.

My view: There is a problem, but it is not exactly a problem of asociality here. As I wrote back (in email, of course) to a friend who I have not seen in—literally, years! since the plague?—even though she has been a substantial presence in my mind as I read pretty much all of her stuff <https://www.charliejaneanders.com/> <https://www.ouropinionsarecorrect.com/> <https://buttondown.com/charliejane/>:

No! No! Thanks much for writing! You are not taking up too much of my time! I wish you were taking up more of my time, here in this world in which even most of our social relationships are primarily parasocial or transactional! It is not a good timeline! And we have not gotten yet to the neofascists and the killer robots!

Share DeLong’s Grasping Reality Weblog

We are going to do lunch. Sometime. To keep our friendship from being totally two-way parasocial—where she has no idea of my reactions and absorption of her words, and I have no idea of her reactions and absorption of mine.

The bandaid I can start putting over this gaping, bleeding wound is to start dropping things in people’s comments sections. The problem, however, is this: we learned early in the internet age never to read our comments sections. The hope is that, on Substack, limiting comments to paid subscribers, we will get into the habit of our reading our comment sections again.

I have no idea how that is going for us.

Subscribe now

Leave a comment

If reading this gets you Value Above Replacement, then become a free subscriber to this newsletter. And forward it! And if your VAR from this newsletter is in the three digits or more each year, please become a paid subscriber! I am trying to make you readers—and myself—smarter. Please tell me if I succeed, or how I fail…

##you-are-not-taking-up-too-much-of-my-time-a-note-from-a-not-asocial-but-rather-parasocial-age-chart-of-the-day
##info-bio-tech-attention-society
##chart-of-the-day
#you-are-not-taking-up-too-much-of-my-time-a-note-from-a-not-asocial-but-rather-parasocial-age
#parasocial-age
#social-isolation
#data-for-progress
#adam-tooze
#rise-of-television
#post-plague-life