The First Time a Fed Easing Move Has Triggered a Sharp Jump in Long-Term Nominal Treasury Bond Rates: CHART OF THE DAY
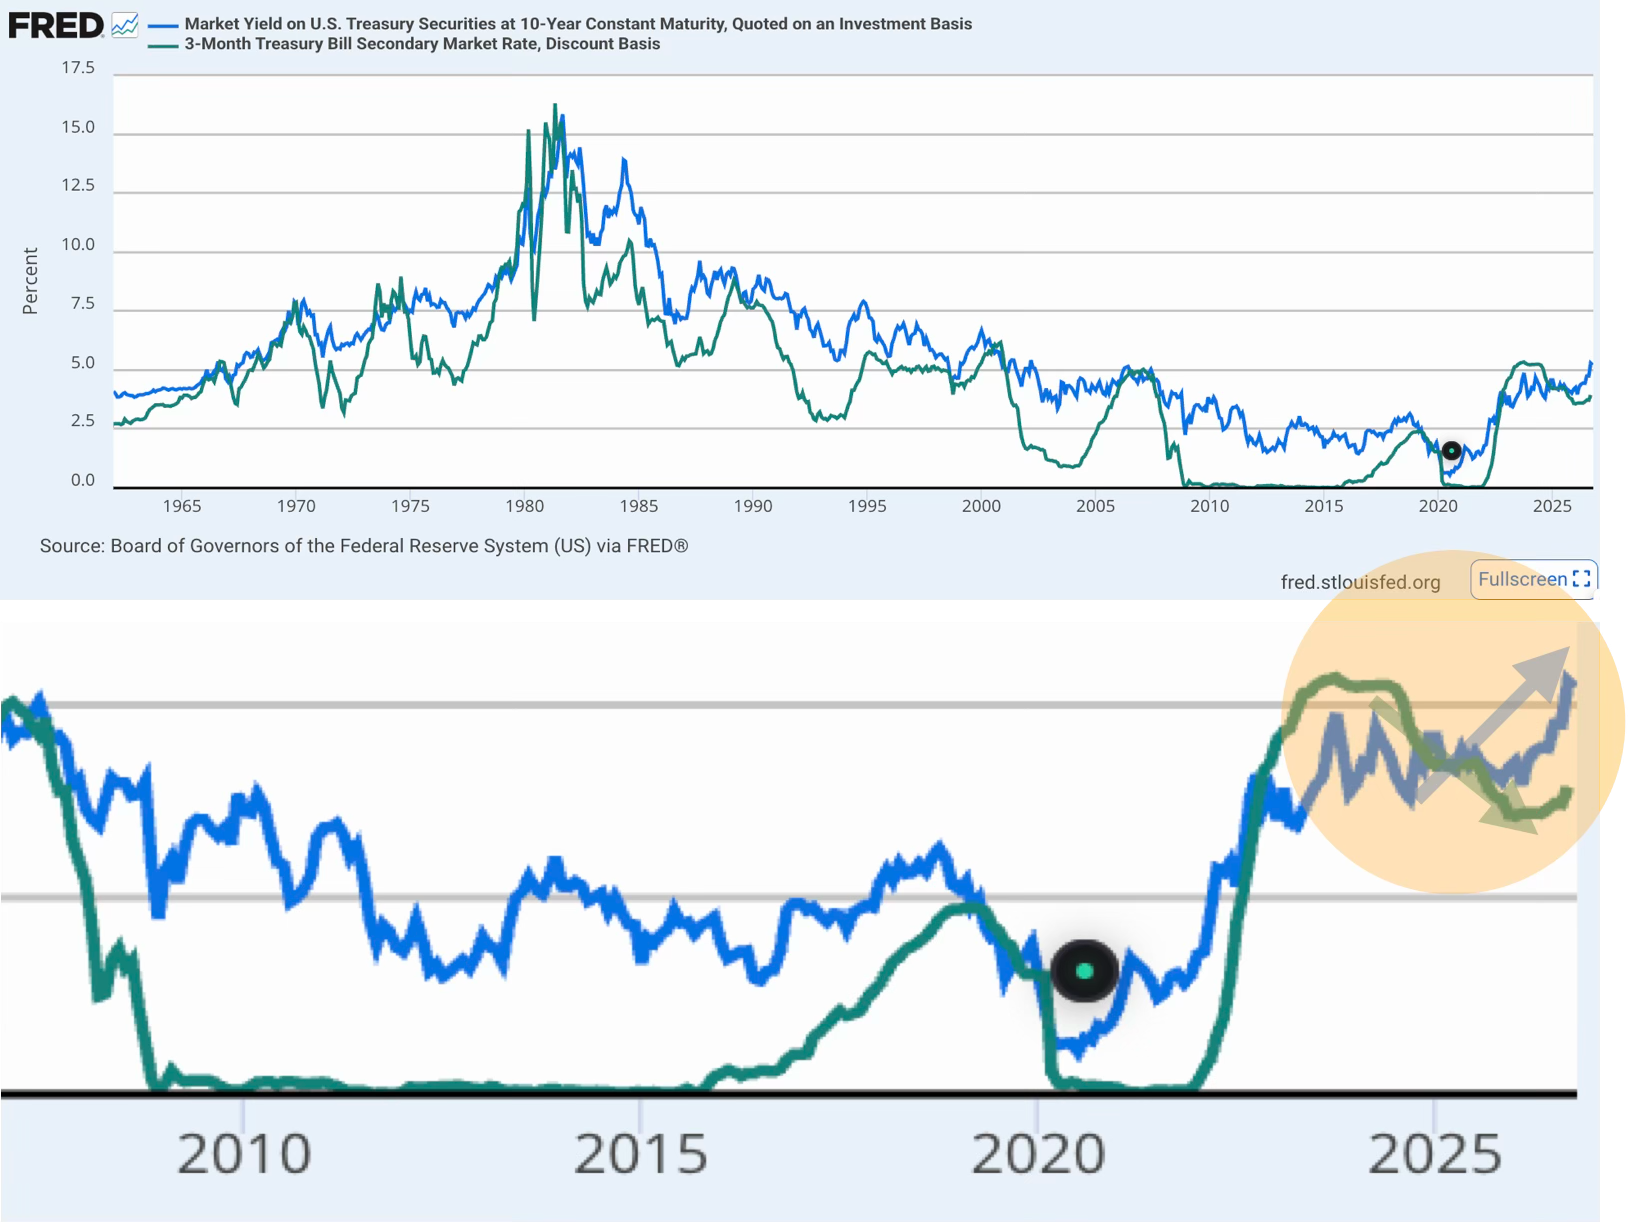
That a Fed easing move is immediately followed by a sharp jump in long-term rates strongly suggests that the Federal Reserve has lost control over the narrative governing bond-market expectations. This has not happened before, at least not in the United States since World War II:
Back in January 2025, when this cross-move first began, I wondered at what was going on:
Brad DeLong: THE MACRO-FINANCE SITCH: The Streams (of Falling Short-Term & Rising Long-Term U.S. Treasury Rates) Cross <https://braddelong.substack.com/p/the-macro-finance-sitch-the-streams>: ‘Since September [2024] the streams have crossed—falling short-term and rising long-term U.S. Treasury interest rates bringing what looks to me like a premature uninversion of the yield curve. Is it the bond vigilantes cleaning their weapons in anticipation of having a Liz Truss Party for the arriving Chaos-Monkey-in-Chief? Or is it a very interesting but rather technical market microstructure phenomenon? I have a weak belief it is the second……
Well! Pretty clear that was wrong! The bond market sees the flood of money into the datacenter construction boom, and has concluded that the Fed is not their guide, The rule held even in the 1970s: when the Fed cut, the long bond followed. The belief was that the Fed probably knew something. Breaking that rule tells you bond traders now treat the Fed as one voice among several, not as the best-informed one. The presumption that it knows what it is doing should not be traded on:
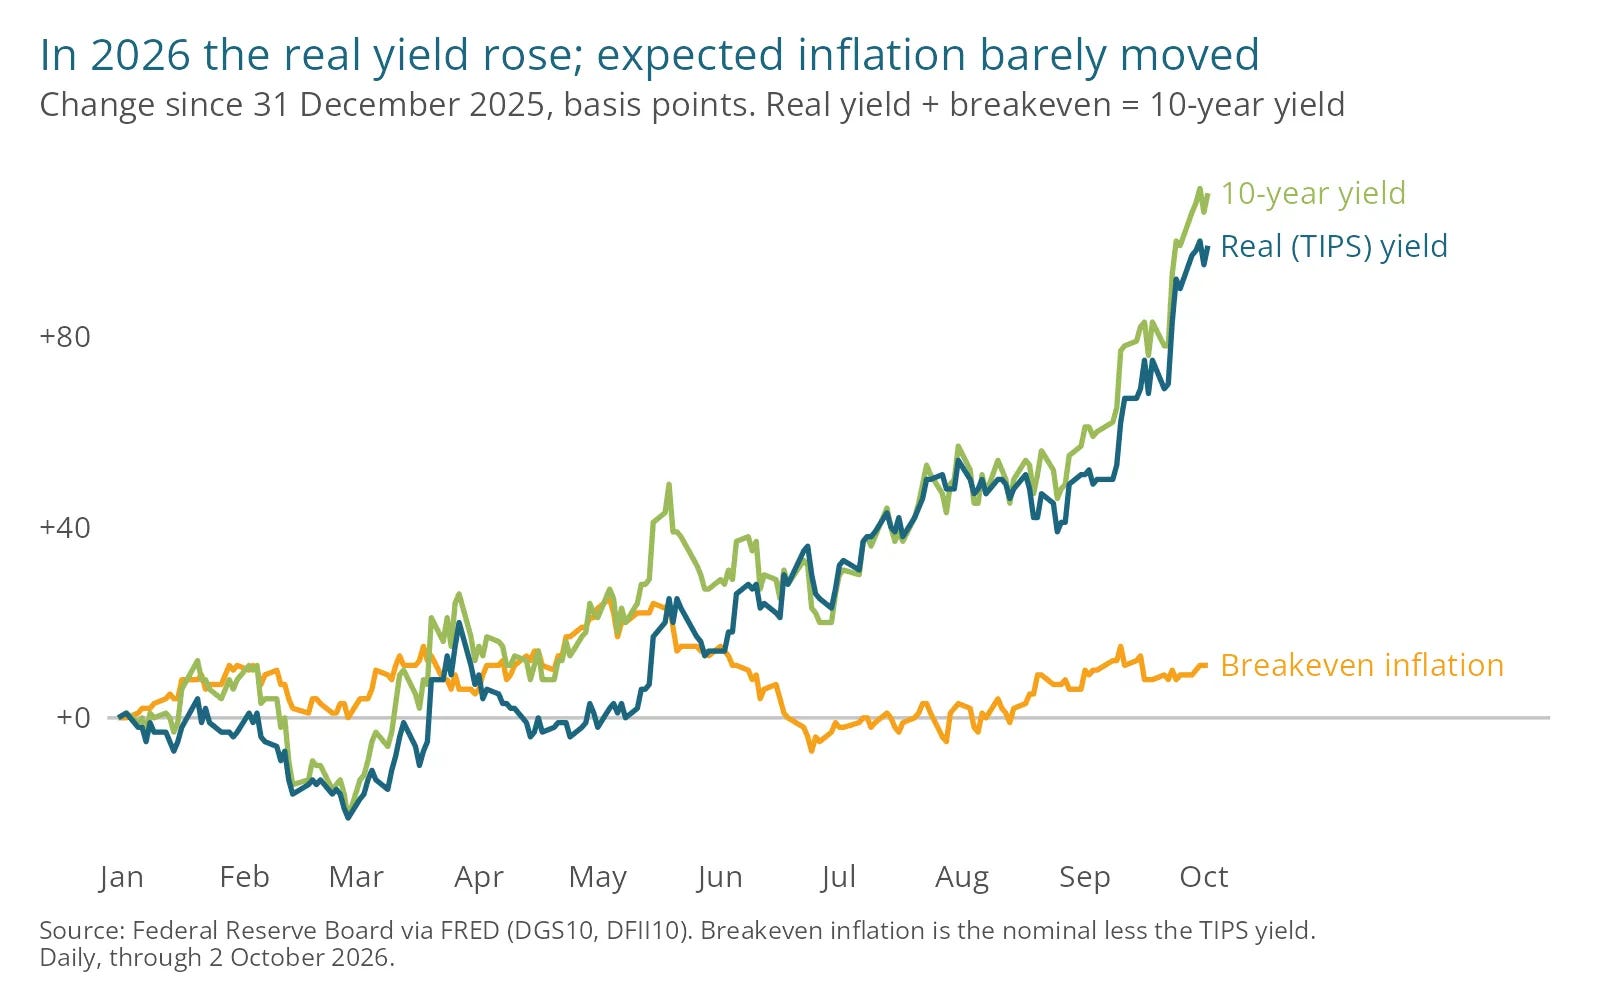
Interesting that the rise is almost all in the real yield. That points away from “the Fed has lost its inflation credibility” and towards real rates and chaos-monkey risk: